AnnualCreditReport.com step by step: your free reports
How to get your free credit reports online, by phone or by mail, what information they ask for, what to check and how to freeze your credit.
Verified against official sources on October 17, 2026 17 official sources
Show contents
In short
What you need to know
Quick answer
AnnualCreditReport.com is the only site authorized by the federal government for your free credit reports from Equifax, Experian and TransUnion. You can view them free every week online, or request them by phone at (877) 322-8228 or by mail with the official form, which is processed within 15 days. They must confirm your identity before giving you the report; if they cannot, they must tell you what is missing. Protection starts there too: freezing your credit is free, but you request it at each agency.
What matters most
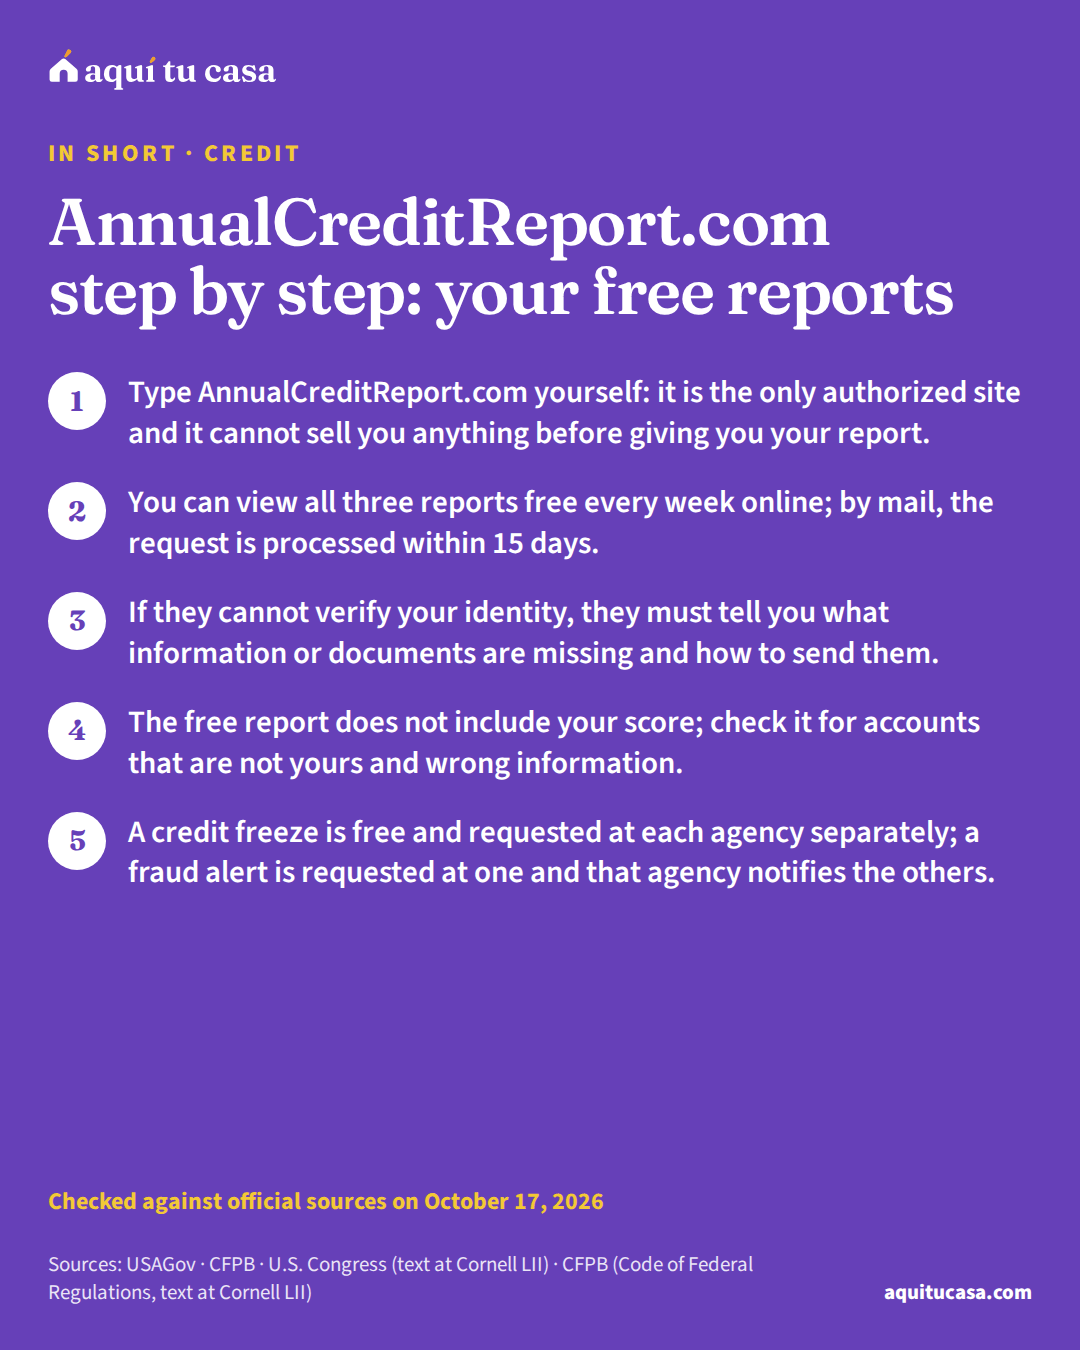
- Type AnnualCreditReport.com yourself: it is the only authorized site and it cannot sell you anything before giving you your report.
- You can view all three reports free every week online; by mail, the request is processed within 15 days.
- If they cannot verify your identity, they must tell you what information or documents are missing and how to send them.
- The free report does not include your score; check it for accounts that are not yours and wrong information.
Is this for you?
This guide is for you if…
- You are getting your credit reports for the first time and want to do it on the right site.
- You prefer to request them by phone or by mail, or the website could not verify your identity.
- You want to freeze your credit or place a fraud alert, for yourself or for your children.
Get direct help first if…
- You already have your reports and want to understand each part: the guide How to read your credit report goes line by line.
- You already found an error: the guide to disputing errors tells you what to send and to whom.
- You already know someone used your identity: start today at IdentityTheft.gov, the federal site for reporting it, and come back to this guide to freeze your credit.
Your credit reports are free, and there is only one site authorized by the federal government to request them. This guide is for anyone doing it for the first time, for anyone who prefers the phone or the mail, and for anyone who wants to protect their credit (or their children’s) with a freeze or a fraud alert. We walk you through it step by step, with what the CFPB (the federal consumer financial protection agency), federal law and the official form say.
What AnnualCreditReport.com is
AnnualCreditReport.com is the only website authorized by the federal government to give you the free annual reports from the three credit reporting agencies.1 It is the “centralized source” the law calls for, so that a single request gets you the reports from all the nationwide credit reporting agenciescredit reporting agencyA credit reporting agency, also called a credit bureau or credit reporting company, is a company that gathers information about people and sells credit reports to other businesses. The three nationwide ones are Equifax, Experian and TransUnion. The businesses that buy those reports use them to decide whether to give you credit, a job, a rental home or insurance. There are also specialty agencies, for example for rental history or check writing. The federal Fair Credit Reporting Act (FCRA) gives you the right to request a copy of your report and to dispute information that is wrong.See the full definition, and those agencies run it together. By regulation, it offers three routes: one website, one toll-free number and one mailing address.5
The law gives you the right to a free credit reportcredit reportA credit report is a statement that has information about your credit activity and current credit situation: your loans and cards, the balances, whether you have paid on time, accounts in collection and who has checked your credit. Credit reporting companies, also called credit bureaus, compile it from what banks and creditors report; your credit score is computed from it. When you apply for a mortgage, the lender pulls your report from the three bureaus. You have the right to see it for free and to dispute anything that is wrong.See the full definition from each agency once in any 12-month period when you request it through that source.3 On top of that, according to the CFPB, you can view them online for free once a week.2 Requesting your own report is a soft inquirysoft inquiryA soft inquiry is a review of your credit file that does not affect your score. It includes reviews of your existing accounts by your lenders or insurers, prescreened offers from prospective lenders, employment screening and your own requests for your credit report. Only you see it when you review your report; businesses that buy your report do not. That is why checking your own credit report, even often, does not lower your score.See the full definition: it does not affect your scores and only you can see it.7
The official site has to tell you that you have reached the place to request the free reports required by federal law.5 And it cannot sell you anything first: advertising and product offers have to wait until you have received your report. After that it may show ads along with it.5 If you see an offer for a score or monitoring at the end, it is optional.
Before you start: what you will need
To give you your report, the agency must require proper identification: that is how it makes sure it does not hand your data to someone else.4 The official source may only ask for the personal information reasonably necessary to identify you.5
The official mail request form shows which information is used. It asks for your Social Security number, your date of birth, your name and your current address. If you have lived at that address for less than two years, it also asks for the previous one. It has a box for the urbanization name, for Puerto Rico only, and another to ask that the report show only the last four digits of your Social Security number. The form says this information is required to process your request and that leaving anything out may delay it.6
Also have your own computer or phone and a private connection at hand. You will be typing very personal information: better not to do it on public Wi-Fi or someone else’s device.
You can ask whether your report is available in your preferred language.2 It is worth asking if reading it in Spanish is easier for you or your family.
Step by step online
Your three reports, online
1. Type the address yourself
Step 1
AnnualCreditReport.com is the only site authorized by the federal government for the free annual reports.1
2. Fill in your information
Step 2
They ask only for what is needed to identify you, and the site must show you how your request is progressing.5
5. Read and save each report
Step 5
Check that it contains only items about you. Your report includes directions for disputing anything wrong.10
The regulation also requires the site to have a help or FAQ screen, with instructions for filing a complaint with the official source and with the CFPB.5 If something does not work, look for it before giving up; you can also switch to the phone or the mail.
By phone or by mail
You do not need the internet. You can call 1-877-322-8228 (TTY: 1-800-821-7232) or fill out the request form and mail it to Annual Credit Report Request Service, PO Box 105281, Atlanta, GA 30348-5281.1 The CFPB links to the form from its page and tells you to download and complete it.2
The form has its own rules:6
- Use a black or blue pen and write in printed capital letters, inside the boxes.
- Fill in everything it asks for: if information is missing, your request may be delayed.
- Mark the agencies you want: Equifax, Experian, TransUnion or all three.
- If you like, shade the box so your report shows only the last four digits of your Social Security number.
- Fold it without staples or tape, put it in a #10 envelope with a stamp and mail it.
Your request is processed within 15 days of receipt, and the report is then mailed to you. If more information is needed, the agency contacts you by mail.6
Three ways to request your reports
Fastest
Online
No computer needed
By phone
All three are free and reach the same three agencies.5
What to check once you have it
The CFPB suggests checking that your report contains only items about you and looking for wrong or incomplete information.10 Check these first:
- Your personal information. Name, phone and address. A misspelled name counts too.9
- Accounts that are not yours. They may belong to someone with the same or a similar name (a mixed file) or come from identity theft.10
- The status of each account. Closed accounts shown as open, late payments you did not make, the same debt twice, wrong balances or limits, or an account where you are only an authorized user but appear as the owner.10
- Collections. A collection you settled and paid that was not updated.9
- Who requested your report. You will see a list of anyone who requested it within the past year, such as lenders, card companies or landlords, and of employers who requested it within the past two years.11
It is a good idea to check them at least once a year, and also before a major purchase with a loan (a house or a car), before applying for a new job and whenever you suspect identity theft.9 The free report does not include your credit scorecredit scoreA credit score is a number that predicts how likely you are to pay back a loan on time. It is computed from the information in your credit report: whether you pay on time, how much you owe relative to your limits, how long you have used credit and how many new accounts you opened. FICO is one brand of score; VantageScore is another, and each lender decides which one it uses. A higher score usually brings a lower interest rate and more loan options; each program publishes the minimum it accepts. You can check your report for free and dispute errors.See the full definition.8 The guide What moves your credit score tells you where to see one without paying.
To read each part, line by line, follow How to read your credit report. If you find an error, a disputecredit report disputeA credit report dispute is the complaint you make when your credit report has wrong or incomplete information. You have the right to dispute it, and the investigation is free. It is usually done in two places: with the credit reporting company and with the company that supplied the information, called a furnisher, such as your bank, your landlord or your credit card company. You explain in writing what is wrong and why, with copies of your documents. The credit reporting company must investigate, generally within thirty days, and delete or correct anything found to be inaccurate, incomplete or unverifiable.See the full definition is free: How to dispute credit report errors tells you what to send.
Freezing your credit or placing a fraud alert
Protection starts from those same reports. There are two free tools, and they are not the same thing.
A credit freezesecurity freezeA security freeze, also called a credit freeze, keeps new creditors from seeing your credit file, which helps stop an identity thief from opening new accounts in your name. By law it is free to place and to lift, and you must ask each of the three nationwide credit reporting companies separately. While it is on, only a few can see your file, such as creditors on accounts you already have, and you can still review your reports. It does not affect your score. Because creditors rarely lend without checking your file, it stops you too; you can lift it for free for a period of time when you need to.See the full definition (security freeze) keeps prospective creditors from seeing your file. It is free at all three agencies, but you have to request it at each one separately, on their websites. If you ask online or by phone, the agency must place it within one business day; by mail, no later than three business days after receiving your request. It must send you written confirmation no later than five business days later and tell you how to remove it.12 The freeze stays in place until you ask for it to be removed.13
To lift it, the agency has one hour if you ask online or by toll-free phone, and three business days if you ask by mail. You can also lift it just for a period you choose, at no charge. While it is in place you can still request and review your reports, and it does not affect your scores.12 But if you apply for credit with the freeze in place and do not allow access, the lender may treat your application as incomplete.13
A fraud alertfraud alertA fraud alert is a note in your credit file that requires creditors who check your report to verify your identity before opening a new account, issuing an additional card or raising your credit limit. You only need to ask one of the nationwide credit reporting companies, which must notify the others. An initial alert is for anyone who suspects they are, or are about to become, a victim of fraud or identity theft, and it lasts one year unless you ask to remove it sooner. An extended alert requires an identity theft report and lasts seven years. When you place one, you are entitled to free copies of your report.See the full definition does not close your file: it requires creditors to make sure it is you before they open a new account, issue an additional card or raise your limit. You place it with one agency and that one must notify the other two.14
Freeze or fraud alert
Closes the door
Freeze
Asks for confirmation
Initial fraud alert
A freeze does not stop someone from using an account you already have: keep watching your statements too.14
Servicemembers on active duty also have a special alert that lasts 12 months.14 And the free-freeze law does not apply to someone requesting your report for a job, tenant screening or insurance.12
Your children may need it too
Children under 18 generally do not have a credit report. One can exist because of an error with a similar name, identity theft, or because the child is an authorized user or joint holder on an adult’s account. If you are a parent or guardian, you can ask the three agencies to search for a report in the child’s name. Warning signs include bills, card offers or collection calls in the child’s name.16
The law also protects children under 16: someone with authority to act for them can request a freeze, and if the agency has no file on the child, it creates one just to freeze it.12
If something goes wrong
- The site cannot verify your identity. They must tell you they could not verify you and explain what information or documents are missing and how to send them.5 Meanwhile, you can try by phone or by mail.1
- An agency denies your request. Contact it first to resolve it; if that does not work, go to the CFPB.1
- You find accounts you did not open. The CFPB says to close the affected accounts, contact your bank’s fraud department and report it to the FTC at IdentityTheft.gov, where you get an identity theftidentity theftIdentity theft happens when someone uses your personal information without your permission to commit fraud: for example, your name, your Social Security or Medicare number, or your credit card or bank account number. With that information, a thief can rent a home, get credit cards, receive government benefits or tax refunds, or open other accounts in your name. You often find out when your credit report or a statement shows accounts or charges you do not recognize, or when a debt collector calls. The federal site IdentityTheft.gov takes reports and gives you a recovery plan.See the full definition report and a recovery plan. With that report, the agencies must block fraudulent information within four business days after receiving your request.14
- You already used your free report and need another one. There are additional free reports, for example if you were denied credit because of your report (ask within 60 days), if you place an initial fraud alert or if you receive public assistance. If none applies, the agency may charge you, and the law sets a limit: currently no more than $16 per report, an amount that may change.2
A HUD-approved housing counselorHUD-approved housing counselorA HUD-approved housing counselor works at an agency HUD has approved to provide housing counseling: independent, expert advice customized to your situation about buying a home, renting, a missed mortgage payment, a foreclosure or credit problems. The agencies usually charge little or nothing; many serve in Spanish and offer the homebuyer education course several assistance programs require. They are not lenders or real estate agents and sell you nothing. Your county page lists the official agencies with phone numbers.See the full definition can go over your reports with you; they give independent advice on credit, often at little or no cost.17
HUD-approved housing counselors by state
| State | HUD-approved counselors |
|---|---|
| Alabama | 25 |
| Alaska | 1 |
| Arizona | 21 |
| Arkansas | 14 |
| California | 81 |
| Colorado | 26 |
| Connecticut | 13 |
| Delaware | 12 |
| District of Columbia | 17 |
| Florida | 98 |
| Georgia | 42 |
| Hawaii | 17 |
| Idaho | 10 |
| Illinois | 81 |
| Indiana | 21 |
| Iowa | 11 |
| Kansas | 3 |
| Kentucky | 19 |
| Louisiana | 26 |
| Maine | 7 |
| Maryland | 41 |
| Massachusetts | 37 |
| Michigan | 59 |
| Minnesota | 33 |
| Mississippi | 16 |
| Missouri | 18 |
| Montana | 11 |
| Nebraska | 8 |
| Nevada | 8 |
| New Hampshire | 5 |
| New Jersey | 34 |
| New Mexico | 7 |
| New York | 93 |
| North Carolina | 52 |
| North Dakota | 3 |
| Ohio | 54 |
| Oklahoma | 6 |
| Oregon | 25 |
| Pennsylvania | 75 |
| Puerto Rico | 9 |
| Rhode Island | 5 |
| South Carolina | 13 |
| South Dakota | 13 |
| Tennessee | 32 |
| Texas | 51 |
| Utah | 7 |
| Vermont | 7 |
| Virginia | 49 |
| Washington | 15 |
| West Virginia | 8 |
| Wisconsin | 26 |
| Wyoming | 1 |
They give advice on credit, among other topics, often at little or no cost.17 Source: HUD
If this is you
You have an ITIN and no SSN
Before you mail the form, call the official line and ask how to make your request.1 If they cannot verify you, they must tell you what is missing.5
You live in Puerto Rico
The mail form has a box for your urbanization name.6
You want to protect your children
You can ask the three agencies to search for a report in your child's name,16 and freeze the credit of a child under 16.12
You would rather read it in Spanish
You can ask whether your report is available in your preferred language.2
Costly mistakes
Mistake: Searching for 'free credit report' and clicking the first ad.
Instead: Type AnnualCreditReport.com yourself: it is the only authorized site.1 Others charge you or sign you up for services.2
Mistake: Paying for monitoring because you think it prevents identity theft.
Instead: Most only alert you afterward; a freeze and your weekly reports are free.15
Mistake: Freezing your credit at only one agency.
Instead: Request it at all three: one does not notify the others.14
Mistake: Applying for a loan while your credit is frozen.
Instead: Lift it first, even for a few days: otherwise your application may be treated as incomplete.13
Mistake: Stapling the mail form or leaving boxes blank.
Instead: Fold it without staples or tape and fill in everything: missing information delays your request.6
Mistake: Giving your information to someone who calls 'from the FTC'.
Instead: The FTC never threatens you; contact each organization yourself through its official numbers.14
What to do this week
- Type AnnualCreditReport.com into your browser yourself and request your three reports.1
- If you cannot do it online, call 1-877-322-8228 or mail the form.1
- Check your personal information, your accounts and the list of who requested your report.11
- If you see something you do not recognize, follow the steps at IdentityTheft.gov and consider freezing your credit at all three agencies.14
- If you are not applying for credit soon, consider a freeze; remember it can be lifted for free when you need it.12
- Put the next check on your calendar: you can view your reports free every week. To plan your next steps, use the credit plan.2
Your situation
If you have never had a card or a loan in the U.S., choose "None".
Your credit plan
12 steps
You have done 0 of 12.
This week
Get your three credit reports for free
At AnnualCreditReport.com you can get the Equifax, Experian and TransUnion reports for free once a week. Checking your own report does not lower your score. If it comes up empty, that is not an error: you simply have no history yet.
Source: CFPB: How do I get a free copy of my credit reports? ↗ · CFPB: Does requesting my credit report hurt my credit score? ↗
Dispute any error in writing
Write to the credit bureau and to the company that reported the item, with copies of your proof, by certified mail. By law, the bureau must investigate again for free and resolve it within 30 days of receiving your notice.
Source: CFPB: How do I dispute an error on my credit report? ↗ · Congreso de EE. UU. (texto en Cornell LII): Fair Credit Reporting Act, 15 U.S.C. §1681i, Procedure in case of disputed accuracy ↗
Talk to a HUD-approved housing counselor
They give independent advice on buying, renting, defaults and credit, often free or at low cost. You can go over your report and your plan with them.
Source: CFPB: Find a Housing Counselor ↗
This month
Open a secured card
You deposit an amount (for example, $500) and can spend up to that amount. With on-time payments, the limit can go up, and the deposit comes back. Before signing, ask whether they report to all three bureaus and compare the annual fee and the rate: they can be high.
Source: CFPB: What are some ways to start or rebuild a good credit history? ↗ · CFPB: How to rebuild your credit ↗
Or a credit builder loan
The bank or credit union holds the money as savings while you make small payments, usually for six to 24 months; when you finish, you get it. You build history and savings at the same time.
Source: CFPB: What are some ways to start or rebuild a good credit history? ↗
Ask for your rent to be reported
On-time rent payments can help build your credit. Ask your landlord whether they take part in a rent reporting program (often through a payment app) and check its fees.
Set up automatic payments
An automatic payment or a reminder before the statement date prevents the costliest kind of slip: payment history is the main factor in most models.
What does not build credit
Paying with a debit card or cash, prepaid cards and payday loans do not build history, according to the CFPB. They are ways to pay, not accounts that get reported.
From here on
Do not close your first account
A long history of on-time payments helps your score. When a better card comes along, keep the first one open and current.
Only apply for the credit you need
Opening several accounts in a short time is a risk signal for lenders, and each application leaves a hard inquiry that does affect your score.
Source: CFPB: How do I get and keep a good credit score? ↗ · CFPB: What is a credit inquiry? ↗
Watch your debt-to-income ratio
Lenders divide your monthly debt payments by your gross monthly income to see whether you can handle a new loan. While you prepare, avoid new payments, such as a car.
Watch out for "credit repair"
It is a scam if they charge before doing anything, promise to remove accurate negative information, tell you not to contact the bureaus or to dispute everything. Disputing errors is free by law, and if you already signed up for something like this, you can cancel within three business days.
Source: CFPB: How can I tell a credit repair scam from a reputable credit counselor? ↗
An educational plan built on what the CFPB, the NCUA and the federal credit reporting law publish; not individual advice. We recommend no brands and are paid for no product.
Ready to see the numbers? Find your county here
See how this applies in your county: its loan limits, prices and rents, from the official data.
Printable checklist
Frequently asked questions
How often can I see my credit report for free?
According to the CFPB, you can see it free once a week at AnnualCreditReport.com, from each of the three agencies. The law also gives you the right to one free report from each agency every 12 months.
Does requesting my report lower my score?
No. Requesting your own report is a soft inquiry: it does not affect your scores and only you can see it.
Does the free report include my credit score?
No. The free reports from the nationwide agencies do not include a score. Our guide on what moves your score tells you where to see one without paying.
What do I do if the website cannot verify my identity?
The regulation requires the official source to tell you it could not verify you and explain what information or documents are missing and how to send them. You can also request by phone or mail. If an agency denies your request, contact it first and, if that does not resolve it, take it to the CFPB.
Can I request my report if I have an ITIN and no Social Security number?
The mail form asks for a Social Security number. Before you send it, call the official line, (877) 322-8228, and ask how to make your request. If they cannot identify you, the regulation requires them to tell you what information or documents are needed and how to send them.
How long does it take by mail?
The official form says your request is processed within 15 days of receipt and the report is then mailed to you. If information is missing, the agency contacts you by mail, which can delay it.
Does freezing my credit cost money?
No. Under federal law, freezing and unfreezing are free at all three agencies, but you have to request it at each one. The credit locks the agencies sell are no more effective than a freeze.
What is the difference between a credit freeze and a fraud alert?
A freeze keeps prospective creditors from seeing your file, and you request it at each agency. A fraud alert does not block access, but it requires creditors to confirm it is you; you request it at one agency and that one notifies the others. An initial alert lasts one year.
Sources
Every figure in this guide comes from one of these official sources. The number next to a sentence leads to the source behind it.
Each source on one line: who publishes it, its title, its address and the date we read it.
- 1. USAGov · Learn about your credit report and how to get a copy · usa.gov · Accessed October 17, 2026
- 2. CFPB · How do I get a free copy of my credit reports? · consumerfinance.gov · Accessed October 17, 2026
- 3. U.S. Congress (text at Cornell LII) · Fair Credit Reporting Act, 15 U.S.C. §1681j, Charges for certain disclosures · law.cornell.edu · Accessed October 17, 2026
- 4. U.S. Congress (text at Cornell LII) · Fair Credit Reporting Act, 15 U.S.C. §1681h, Conditions and form of disclosure to consumers · law.cornell.edu · Accessed October 17, 2026
- 5. CFPB (Code of Federal Regulations, text at Cornell LII) · Regulation V, 12 CFR §1022.136, Centralized source for requesting annual file disclosures from nationwide consumer reporting agencies · law.cornell.edu · Accessed October 17, 2026
- 6. Central Source LLC (AnnualCreditReport.com) · Annual Credit Report Request Form · annualcreditreport.com · Accessed October 17, 2026
- 7. CFPB · What is a credit inquiry? · consumerfinance.gov · Accessed October 17, 2026
- 8. CFPB · I got my free credit reports, but they do not include my credit scores. Can I get my credit score for free too? · consumerfinance.gov · Accessed October 17, 2026
See the other 9 sources
- 9. CFPB · When should I review my credit report? · consumerfinance.gov · Accessed October 17, 2026
- 10. CFPB · What are common credit report errors that I should look for on my credit report? · consumerfinance.gov · Accessed October 17, 2026
- 11. CFPB · How can I find out who has accessed my credit report? · consumerfinance.gov · Accessed October 17, 2026
- 12. CFPB · What is a credit freeze or security freeze on my credit report? · consumerfinance.gov · Accessed October 17, 2026
- 13. U.S. Congress (text at Cornell LII) · Fair Credit Reporting Act, 15 U.S.C. §1681c-1, Identity theft prevention; fraud alerts and active duty alerts · law.cornell.edu · Accessed October 17, 2026
- 14. CFPB · What do I do if I am a victim of identity theft? · consumerfinance.gov · Accessed October 17, 2026
- 15. CFPB · What is a credit monitoring service? · consumerfinance.gov · Accessed October 17, 2026
- 16. CFPB · How do I check to see if a child has a credit report? · consumerfinance.gov · Accessed October 17, 2026
- 17. CFPB · Find a Housing Counselor · consumerfinance.gov · Accessed October 17, 2026
Keep reading
Related guides
If this guide helped, these follow the same path.

Credit 13 minute read
How to read your credit report, line by line
Where to get your free credit reports, what each part says, how long negative items can stay and how to spot errors or identity theft.
- AnnualCreditReport.com is the only site the federal government authorizes for free reports; right now you can view them every week.
- The report is not the score: the report is your history; the score is a prediction calculated from it, and in most cases it is not included.
- Check five parts: personal information, accounts, collections, public records and inquiries. Requesting your own report does not lower your score.
- Credit How to dispute errors on your credit report How to fix credit report errors for free: what to send each bureau and the company that reported it, legal deadlines, and credit repair scams. 14 minute read
- Credit Credit from zero: how to start your history in the U.S. What credit reports and scores are, how to get them for free, and how to start a history from nothing with a secured card or a credit-builder loan. 16 minute read
- Credit What moves your credit score: the five factors What raises and lowers your credit score according to the CFPB, FICO and VantageScore: on-time payments, credit use, age, new credit and account mix. 15 minute read
Tools for this topic
Was this guide useful?
Thank you. Your answer stays in your browser; nothing is sent.