Renting Essential guide
How to rent without a Social Security number or credit
What a landlord can ask for, what to offer instead of an SSN and credit, how much rent fits your income and your rights if you are turned down.
Verified against official sources on October 17, 2026 17 official sources
Show contents
In short
What you need to know
Quick answer
You can rent without a Social Security number and without a credit history: each landlord decides what to accept, within what your state's law allows. Show up with what you do have: photo ID (passport or consular ID), your ITIN if you have one, proof of income, bank statements and references; sometimes you will be asked for a cosigner, a larger deposit or rent in advance. If a report gets you rejected or put on conditions, you have the right to know, to a free copy and to dispute errors. And never pay before seeing the place.
What matters most
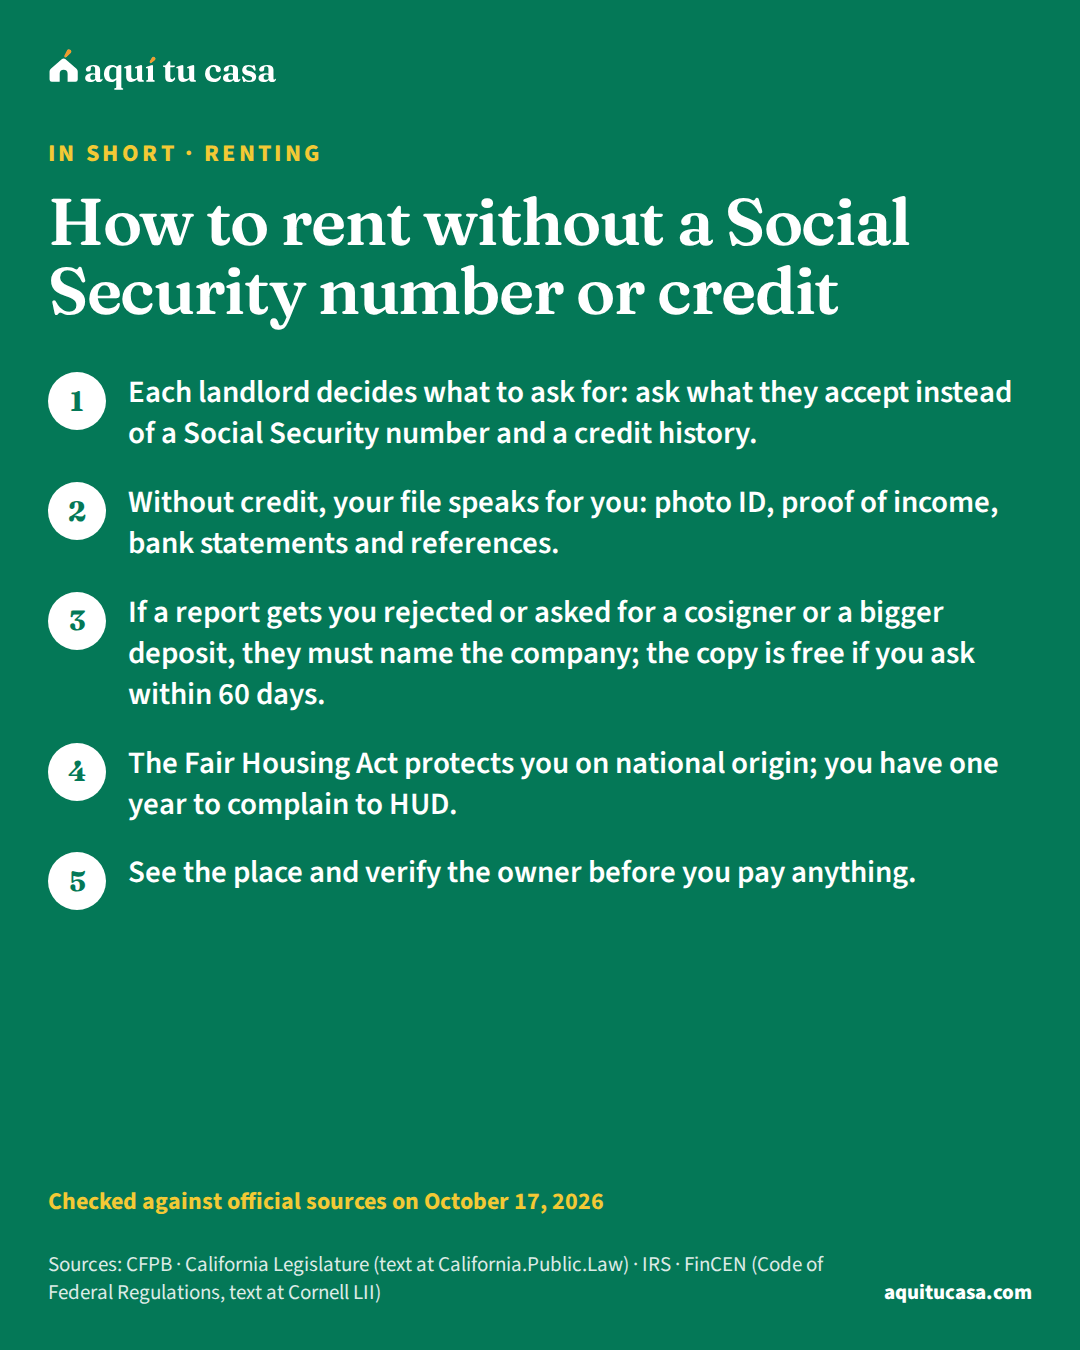
- Each landlord decides what to ask for: ask what they accept instead of a Social Security number and a credit history.
- Without credit, your file speaks for you: photo ID, proof of income, bank statements and references.
- If a report gets you rejected or asked for a cosigner or a bigger deposit, they must name the company; the copy is free if you ask within 60 days.
- The Fair Housing Act protects you on national origin; you have one year to complain to HUD.
Is this for you?
This guide is for you if…
- You just arrived or have never had credit in the United States and need to rent.
- You do not have a Social Security number and rental applications ask for one.
- An application was rejected and nobody told you why.
Get direct help first if…
- You already have an eviction notice or a lawsuit: find a free legal aid office today; that is another guide.
- You are looking for subsidized housing or a rent voucher: start with your local public housing authority.
- You have a question about your immigration case: talk to a Department of Justice accredited representative or an immigration attorney.
Renting without a Social Security number and without a credit history can be done. There is no single rule: each landlord decides what to ask for and what to accept, within what their state’s law allows. This guide explains what landlords check, what you can offer instead of a Social Security number and credit, how much rent fits your income and what to do if the answer is no.
What the landlord checks
According to the CFPB, when you apply to rent, many landlords use a tenant screeningtenant screening reportA tenant screening report is a report many landlords use to decide whether to rent to you and how much to charge for the security deposit. Specialty companies prepare it, and it can include your credit report, your rental history including eviction cases and lawsuits, employment verification, criminal history and a score or recommendation. It is not the same as a credit report. If a landlord denies you, or asks for a larger deposit or higher rent, because of the report, federal law requires the landlord to tell you, name the company and explain your right to a free copy and to dispute errors.See the full definition report to decide whether to rent to you and how much to charge for the deposit. That report may include your credit history, your rental history (with evictions and lawsuits), employment verification and criminal history.2 The credit reportcredit reportA credit report is a statement that has information about your credit activity and current credit situation: your loans and cards, the balances, whether you have paid on time, accounts in collection and who has checked your credit. Credit reporting companies, also called credit bureaus, compile it from what banks and creditors report; your credit score is computed from it. When you apply for a mortgage, the lender pulls your report from the three bureaus. You have the right to see it for free and to dispute anything that is wrong.See the full definition is a common part: businesses other than lenders use it to decide whether to rent a house or apartment to you.1
Screening companies also verify your identity, income and employment. The CFPB explains that most of them have no information on you until you apply for rental housing.3 If the application asks for a Social Security number and you do not have one, ask what they accept instead to look up your history.
What a landlord may ask for depends on your state. In California, for example, the law prohibits asking about your immigration or citizenship status, or requiring you to state it. The same law lets a landlord request the information or documents needed to verify your identity and your ability to pay, and comply with federal legal obligations, such as those of federal rental assistance programs.4 Other states have different rules: according to the CFPB, your rights as a tenant are usually spelled out in your lease and in your state or local laws.5
What you can offer instead of a Social Security number and credit
If you have no Social Security number or credit history, the landlord decides what to accept. These are the pieces you can bring, and what official sources say about each:
- Photo ID. A valid passport, a consular IDconsular ID cardA Matricula Consular is an official Mexican government ID document issued by Mexico's consulates in the United States. Other countries offer similar IDs, sometimes called consular identification (CID) cards. According to the CFPB, many banks require a U.S. or state government-issued photo ID; if you do not have one, some banks and credit unions accept foreign passports and consular IDs such as the Matricula, but not all, and the CFPB suggests asking first. You usually also need another document, such as a bill with your name and address, and an interest-bearing account requires an SSN or ITIN.See the full definition or a driver’s license. In California, a landlord may request documents to verify your identity.4
- ITIN. An ITINITIN (Individual Taxpayer Identification Number)An ITIN is a nine-digit number the IRS, the federal tax agency, issues to people who need a U.S. taxpayer identification number to file taxes and are not eligible for a Social Security number. It is for tax purposes only: it does not authorize you to work in the United States, does not qualify you for Social Security benefits or the Earned Income Tax Credit, and says nothing about your immigration status. You apply with Form W-7, and it expires if it goes unused for several years. Some lenders accept an ITIN for a mortgage.See the full definition is a 9-digit number the IRS issues for federal taxes to people who cannot get a Social Security number. The IRS makes clear it does not serve as identification outside the tax system, so bring it together with your photo ID.6
- Proof of income. Pay stubs, an employer letter or a tax transcriptIRS tax transcriptAn IRS tax transcript is a free official summary of the information on your tax returns and tax account. It is not a photocopy of your return. There are several types: the tax return transcript shows most line items from your Form 1040 as filed and usually meets the needs of mortgage lenders; the tax account transcript shows changes made after you filed; the wage and income transcript shows what your W-2s and 1099s reported. You can get one through your IRS online account, by mail, by phone or with Form 4506-T.See the full definition. The IRS explains that a transcript partially masks your personal information but keeps financial data visible for income verification; you can view it online or request it by mail, and it arrives in 5 to 10 calendar days.7
- Bank statements. They show that the rent money comes in regularly. The federal rule lets a bank identify you with your ITIN, your passport number or another official photo document; the guide to opening a bank account without a Social Security number explains how.8
- References. Previous landlords or your employer. Screening companies look at rent payment history, so a good record counts.3
- A cosignerco-signerA co-signer is a person who signs another person's loan or credit account to back it up, and by doing so becomes responsible for the debt. If the borrower does not pay, the creditor can collect up to the full debt from the co-signer, plus late fees or collection costs, without first trying to collect from the borrower, and the default may become part of the co-signer's credit record. A federal FTC rule calls for the co-signer to get a written notice explaining these risks before signing. On a mortgage, according to Fannie Mae, a co-signer signs the note and shares liability for the debt with the borrower but has no ownership interest in the home on the title.See the full definition, a larger deposit or rent in advance. These are conditions a landlord may set when your history is not enough for them.3 If they set them because of what a report says, the CFPB explains it is an adverse action and they must give you a notice.11
Your application, step by step
1. Work out your rent ceiling
The federal reference is 30% of your monthly income.14
Try it with your numbersHow much rent can I afford?2. Check your credit report first
Look for errors before you apply. If you have no history, check that there is no one else's information on it.3
3. Gather your documents
Photo ID, your ITIN if you have one, proof of income, bank statements and references.6
4. See the home and verify the owner
Before you sign or pay anything. That is how you avoid fake listings.15
5. Ask before you apply
What they accept instead of a Social Security number and whether they will check your credit with a hard inquiry.3
6. If you are rejected, ask for the notice
It must say which company made the report. Request your free copy within 60 days.11
If this is you
You have an ITIN but no Social Security number
An ITIN is for taxes and the IRS says it does not serve as identification outside that system.6 Bring it with your passport or consular ID. The ITIN guide explains what else it is for.
You have never had credit here
Most screening companies have no data on you until you apply.3 The Credit from zero guide explains how to start your history.
If a report gets you rejected, you have rights
Under the federal Fair Credit Reporting Act, anyone who denies you something, or gives it on worse terms, based on a consumer report must give you an adverse action notice with the name, address and telephone number of the agency that made the report, tell you of your right to a free copy within 60 days and of your right to dispute the accuracy of the information.9
The FTC spells it out for renting: if a landlord rejects your application, charges you more rent, requires a cosigner or a larger deposit because of your report, they must give you that notice (in writing, electronically or orally) with the screening company’s details; the company must give you a free copy if you request it within 60 days, and must investigate a dispute within 30 days and tell you the results in writing.10
The CFPB lays out the steps if you are denied. First, ask the landlord what information in the report was the problem, in case you can explain it. Then ask for a copy of the report, from the landlord or from the company that made it. Review it and dispute anything inaccurate or outdated. The company generally has 30 days to investigate, and in some cases 45.11 If the report mixed your data with someone else’s, that dispute is how you clean it up. The guide How to dispute credit report errors explains how to write it.
Your rights against discrimination
The Fair Housing ActFair Housing ActThe Fair Housing Act is the federal law that makes it illegal to refuse to sell or rent a dwelling, or to discriminate in its terms, because of race, color, religion, sex, familial status (having children), national origin or disability. It applies to landlords, real estate agents and managers, and also to banks and lenders when their practices make housing or credit unavailable for those reasons. National origin covers your language and the country you come from, regardless of immigration status. If you believe you were discriminated against, you can file a complaint with HUD at no cost; many states add protections.See the full definition makes it unlawful to refuse to rent a dwelling, or to make it unavailable, because of race, color, religion, sex, familial status or national origin, and also because of a handicap.12 The CFPB explains that a landlord generally cannot set different rules in your lease for those reasons either. National origin covers your country of origin or ancestry, and familial status covers pregnancy and families with children.5
A discrimination complaint is filed with HUD not later than one year after the practice occurred or ended.13 Keep ads, messages and names. You may qualify for free legal aidlegal aidLegal aid is the free civil legal help that nonprofit organizations and their lawyers provide to low-income people in civil, not criminal, matters. In housing, that includes representing families facing eviction or foreclosure, alongside matters such as custody, child support, protection from domestic violence and access to benefits. In the United States, the Legal Services Corporation, created by Congress, funds a nationwide network of these organizations; its finder points you to the one in your area. Each sets its own income limits.See the full definition based on your income;16 legal aid offices know your state’s or city’s protections. If your question is about your immigration case, look for a Department of Justice accredited representative or an immigration attorney.
How much rent you can pay
HUD’s housing-program rule sets the tenant’s payment at the highest of several amounts, including 30% of the family’s monthly adjusted income; that is the federal reference we use to talk about affordable rent.14 Above it, rent weighs; at 50% or more, it weighs a lot.
Example with real numbers
How much rent fits a typical income
With the typical US household income and the federal reference for affordable rent.
- Typical household income, per month
- $6,728
- Federal reference
- 30% of income
- Typical rent in the United States
- $1,413
- Rent that fits that reference
- $2,018
This is an example with national Census numbers. The 30% reference comes from HUD's rule for its housing programs.14 Your real ceiling depends on your income and your other expenses.
Run it with your numbersHow much rent can I afford?Many renting families go over that reference. According to the Census Bureau’s American Community Survey, 51% of renter households pay 30% or more of their income on rent, and 26% pay 50% or more. The rent burden page has the numbers for your area.

The how much rent can I afford calculator turns it into dollars with your income. Your county’s page under Places shows the fair market rentfair market rent (FMR)The fair market rent (FMR) is the rent HUD estimates every year for each area and each unit size, including the cost of utilities (except telephone). It is neither the lowest nor the highest rent: by rule it is set at the 40th percentile, the dollar amount below which 40% of the area's standard-quality rental units rent. HUD uses it to set the payment standards of the Housing Choice Voucher program (Section 8) and for other programs; on aquitucasa we use it as the benchmark for what renting costs in your county and for the wage needed to pay it.See the full definition HUD calculates for your area, useful to tell whether a price is normal.
The deposit and the lease
The security depositsecurity depositA security deposit is money you pay the landlord when you start renting as security that you will follow the lease: pay the rent and take care of the home. The money still belongs to you. The landlord holds it and, when you move out, must return it minus the charges the law allows, such as past-due rent or damage beyond normal wear and tear. You should not be charged for damage that was already there when you moved in. The maximum amount and the deadline to return it depend on your state's law and sometimes your city's.See the full definition, its cap and the deadline to return it depend on each state’s law and, sometimes, the city’s; your rights are in your lease and in those laws.5 Always get a receipt, take photos of the place the day you move in and read in the lease when and how it is returned. The security deposits guide has the rules for several states.
Sign only what you understand. If the lease is in English and you do not read it well, ask for time to go through it with someone you trust; the guide Your lease explained says which clauses to check. A housing counselor or a legal aid office can review it with you.17
Rental scams, in three signs
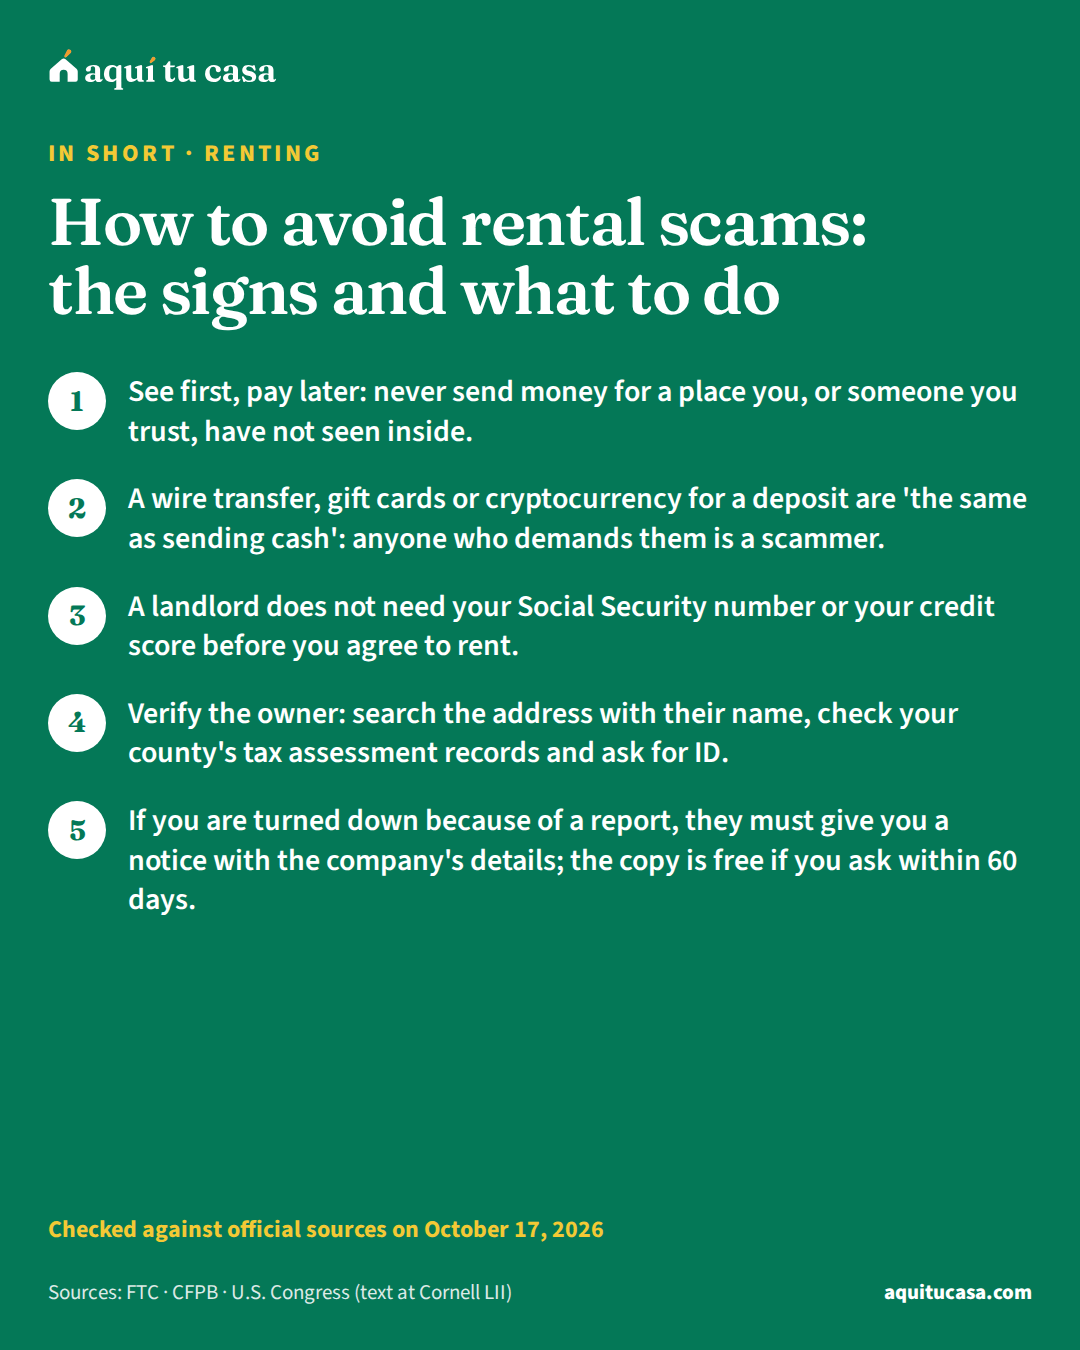
The FTC describes the signs of a rental listing scam: pressure to pay by wire, gift cards or cryptocurrency before seeing the place, an “owner” who claims to be out of the country and surprisingly low rent.15 Its advice is simple: look at the property before you sign or pay, and remember that paying by wire, gift card or crypto is the same as sending cash.15
Costly mistakes
Mistake: Sending copies of your passport or ITIN to an “owner” who has not shown you the home.
Instead: See the property before you sign or pay, and hand over documents only with a formal application.15
Mistake: Using your ITIN as if it were an ID.
Instead: The IRS says it does not serve as identification outside the tax system; bring your passport or consular ID.6
Mistake: Sending many applications the same day without asking how they check credit.
Instead: A hard inquiry can lower your score; ask before you apply.3
Mistake: Accepting a rejection, or a bigger deposit, without asking for the notice.
Instead: Ask for the adverse action notice and your free copy of the report within 60 days.11
Mistake: Paying months up front without the lease saying so.
Instead: Ask for the lease to state how much you paid and for which months, and get a receipt for every payment.3
Where you get free help
HUD-approved housing counselorsHUD-approved housing counselorA HUD-approved housing counselor works at an agency HUD has approved to provide housing counseling: independent, expert advice customized to your situation about buying a home, renting, a missed mortgage payment, a foreclosure or credit problems. The agencies usually charge little or nothing; many serve in Spanish and offer the homebuyer education course several assistance programs require. They are not lenders or real estate agents and sell you nothing. Your county page lists the official agencies with phone numbers.See the full definition give independent advice on buying, renting, defaults and credit, often at little or no cost.17 The CFPB says you may qualify for free legal aid based on your income, and that HUD’s counseling program can be reached at 800-569-4287.16 Both links are at the end of this guide, and the guide to HUD-approved housing counselors explains how to find one, including in Spanish.
What to do this week
- Put your file together with the list below and make copies.3
- Work out your rent ceiling with the calculator and compare it with your county’s fair market rent.14
- Check your credit report before you apply.3
- When you see a listing, verify the owner or the management company before paying anything.15
- If you are rejected, ask for the adverse action notice and the free copy of the report.10
- If you suspect discrimination, keep everything and call a free legal aid office.13
Your income
Let's do the math
Rent that fits your budget (30% of income)
$2,018
With an income of $6,728 a month. Up to $3,364 would already be a severe burden (50% of income).
Compared with HUD’s Fair Market Rent in the United States
- 2 bedrooms$1,750Fits · 26%Needs $33.65 an hour
The wage needed pays that rent without going over 30% of income, working 40 hours a week all year.
The typical rent households actually pay in the United States is $1,413 a month (Census).
A reference to give you an idea. Each landlord and each program sets its own requirements.
Ready to see the numbers? Find your county here
See how this applies in your county: its loan limits, prices and rents, from the official data.
Printable checklist
Frequently asked questions
Can they ask for my immigration status to rent?
It depends on the state. In California, the law prohibits a landlord from asking about your immigration status or requiring you to state it, but allows them to request documents to verify your identity and ability to pay. Nationwide, the Fair Housing Act prohibits refusing to rent to you because of your national origin. If you think you were treated differently because of your origin, keep the messages and find free legal aid.
Can I rent with just my ITIN?
An ITIN is a number for federal taxes: the IRS says it does not serve as identification outside the tax system. Also bring photo ID, such as your passport or consular ID, and ask the landlord what they accept to check your history.
How much rent can I pay?
The federal reference is 30% of monthly income: above that, rent weighs; at 50% or more, it weighs a lot. With the typical US household income ($6,728 a month), that comes to $2,018. The how-much-rent calculator does it with your income.
Can they charge me a bigger deposit because I have no credit?
According to the CFPB, many landlords use the tenant screening report to decide how much to charge for the deposit. If you are asked for a larger deposit than other applicants because of what a report says, that is an adverse action: they must give you the notice naming the company that made the report. How large the deposit can be is set by your state's law.
How do I prove my income if I am paid in cash?
Deposit your money in an account so your bank statements show it: the federal rule lets a bank identify you with your ITIN, your passport or another official photo document. If you file taxes, you can ask the IRS for a transcript of your return, which keeps your financial data visible for income verification.
Should I pay several months up front?
The CFPB mentions paying months of rent in advance as one of the conditions a landlord may set when your report has negative information. If you accept, ask for the lease to state how much you paid and for which months, and get a receipt for every payment. A housing counselor or a legal aid office can review it with you.
What do I do if my report has errors or someone else's information?
Ask the company that made it for a copy, review it and dispute what is wrong. The company generally has 30 days to investigate, and in some cases 45. The CFPB recommends checking your credit report before you apply, so you can fix errors in time.
Sources
Every figure in this guide comes from one of these official sources. The number next to a sentence leads to the source behind it.
Each source on one line: who publishes it, its title, its address and the date we read it.
- 1. CFPB · What is a credit report? · consumerfinance.gov · Accessed October 17, 2026
- 2. CFPB · What is a tenant screening report? · consumerfinance.gov · Accessed October 17, 2026
- 3. CFPB · List of consumer reporting companies · consumerfinance.gov · Accessed October 17, 2026
- 4. California Legislature (text at California.Public.Law) · California Civil Code §1940.3 (tenant immigration status) · california.public.law · Accessed October 17, 2026
- 5. CFPB · Your tenant and debt collection rights · consumerfinance.gov · Accessed October 17, 2026
- 6. IRS · Individual Taxpayer Identification Number (ITIN) · irs.gov · Accessed October 17, 2026
- 7. IRS · Get transcript · irs.gov · Accessed October 17, 2026
- 8. FinCEN (Code of Federal Regulations, text at Cornell LII) · 31 CFR §1020.220, Customer identification program requirements for banks · law.cornell.edu · Accessed October 17, 2026
See the other 9 sources
- 9. U.S. Congress (text at Cornell LII) · Fair Credit Reporting Act, 15 U.S.C. §1681m, Requirements on users of consumer reports · law.cornell.edu · Accessed October 17, 2026
- 10. FTC · Tenant Background Checks and Your Rights · consumer.ftc.gov · Accessed October 16, 2026
- 11. CFPB · What should I do if my rental application is denied because of a tenant screening report? · consumerfinance.gov · Accessed October 17, 2026
- 12. U.S. Congress (text at Cornell LII) · Fair Housing Act, 42 U.S.C. §3604, Discrimination in the sale or rental of housing · law.cornell.edu · Accessed October 17, 2026
- 13. U.S. Congress (text at Cornell LII) · Fair Housing Act, 42 U.S.C. §3610, Administrative enforcement · law.cornell.edu · Accessed October 17, 2026
- 14. HUD (Code of Federal Regulations, text at Cornell LII) · 24 CFR §5.628, Total tenant payment · law.cornell.edu · Accessed October 17, 2026
- 15. FTC · Rental Listing Scams · consumer.ftc.gov · Accessed October 16, 2026
- 16. CFPB · Help for renters · consumerfinance.gov · Accessed October 17, 2026
- 17. CFPB · Find a Housing Counselor · consumerfinance.gov · Accessed October 17, 2026
Keep reading
Related guides
If this guide helped, these follow the same path.
ITIN 15 minute read
What an ITIN is and what it is for
The ITIN is the IRS number for filing taxes without a Social Security number: what it does and does not do, how to apply with Form W-7, timing and expiry.
- The ITIN is a tax number, nothing more: not a work permit, not a status and not an ID.
- You can apply regardless of immigration status, with the W-7 in the same package as your federal return; the passport is the only document that works on its own.
- It is free at an IRS center or a VITA site with ITIN services; an acceptance agent charges a fee.
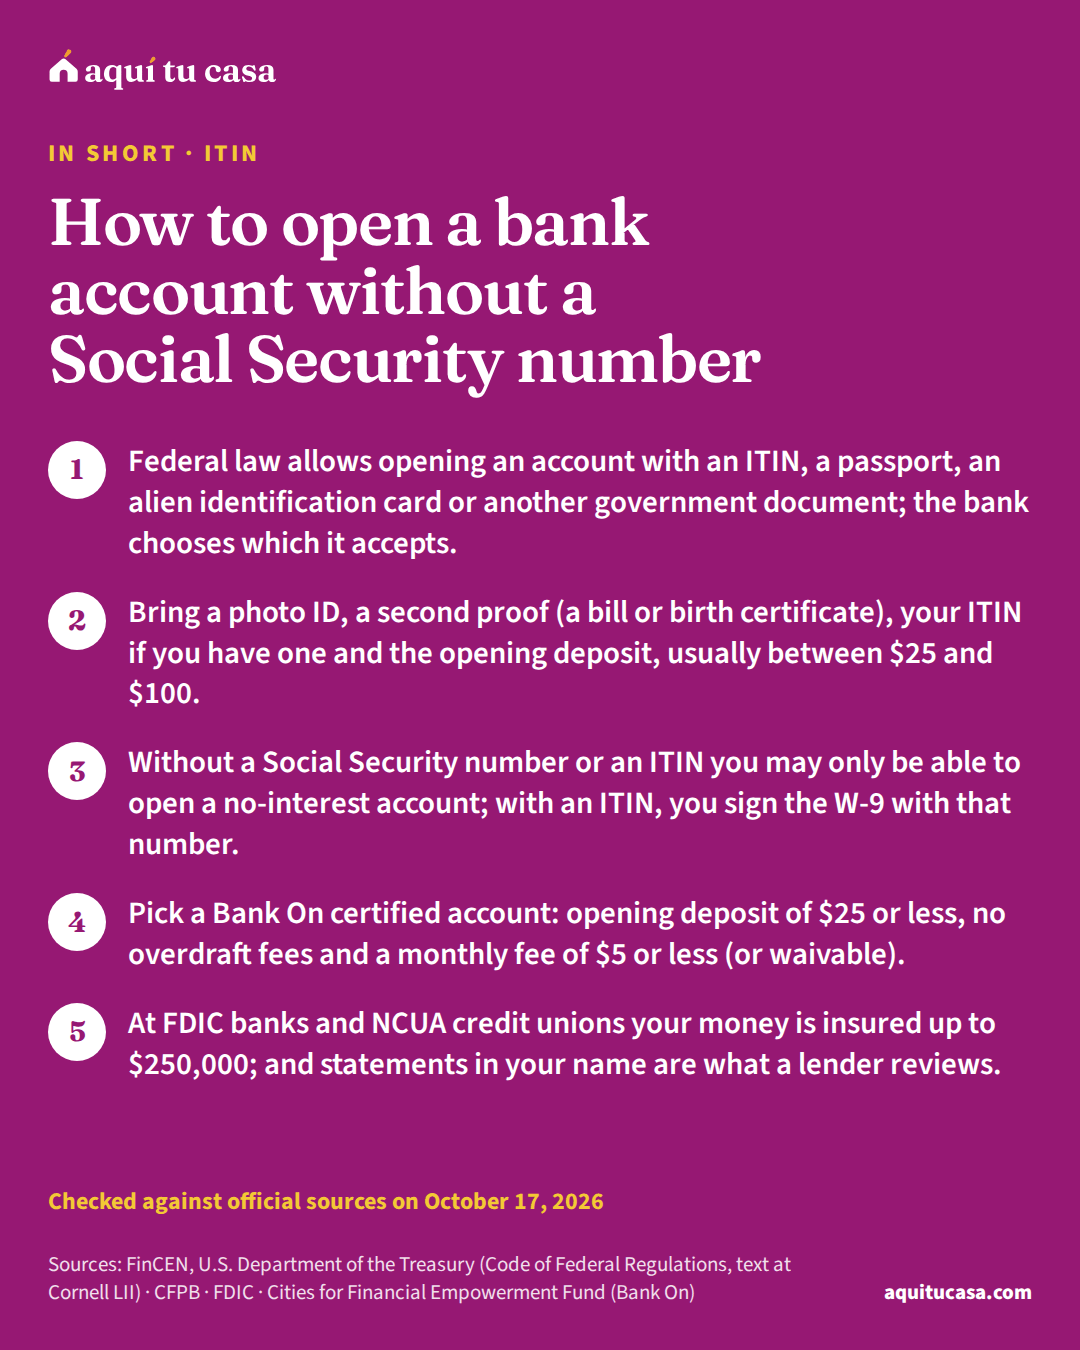
- ITIN How to open a bank account without a Social Security number What banks and credit unions ask for to open an account without a Social Security number (ITIN, passport or consular ID) and which account to pick. 11 minute read
- Renting How to avoid rental scams: the signs and what to do The signs of a fake rental listing, what never to pay up front, what not to share before you sign and where to report, according to the FTC and CFPB. 12 minute read
- Renting Security deposits: how much and how to get yours back What a security deposit is, how much a landlord may charge in your state, what can be deducted, when it must be returned and where to complain if it isn't. 14 minute read
Tools for this topic
Was this guide useful?
Thank you. Your answer stays in your browser; nothing is sent.