Owning a home Essential guide
Home insurance explained: what it covers, how much to buy
What home insurance covers, why the lender requires it, how to choose the amount and the deductible, why flood is separate and what happens if it lapses.
Verified against official sources on October 17, 2026 14 official sources
Show contents
In short
What you need to know
Quick answer
Home insurance pays for damage to your property from unexpected events (fire, theft, storm) and for your liability if someone is hurt there; the lender requires it while you have a mortgage, and you almost always pay it through the escrow account. You choose the company: compare the same coverage across several and ask your state insurance department. Insure for the cost of rebuilding, not the purchase price, and remember that flood and earthquake are separate. If your policy lapses, the loan servicer can buy you a more expensive policy, but only after notifying you in writing.
What matters most
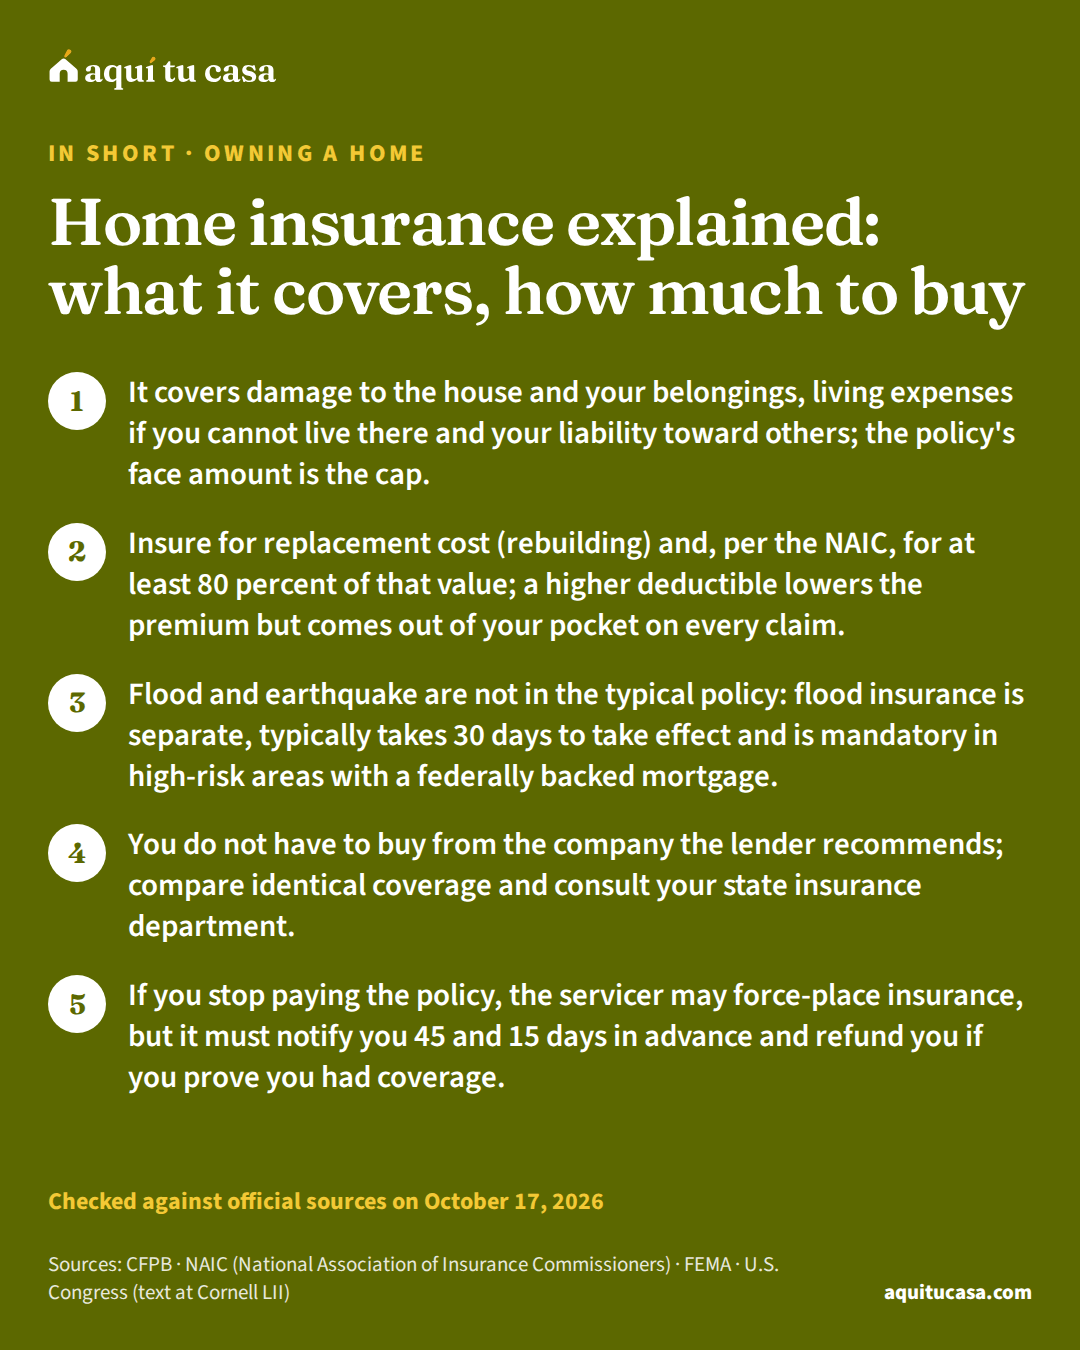
- It covers damage to the house and your belongings, living expenses if you cannot live there and your liability toward others; the policy's face amount is the cap.
- Insure for replacement cost (rebuilding) and, per the NAIC, for at least 80 percent of that value; a higher deductible lowers the premium but comes out of your pocket on every claim.
- Flood and earthquake are not in the typical policy: flood insurance is separate, typically takes 30 days to take effect and is mandatory in high-risk areas with a federally backed mortgage.
- You do not have to buy from the company the lender recommends; compare identical coverage and consult your state insurance department.
Is this for you?
This guide is for you if…
- You are about to close and the lender asks for 'proof of insurance' and you do not know what to buy.
- You already own and want to understand your policy, lower the cost or know whether you are properly insured.
- You live in a hurricane, river or wildfire area and are being asked about flood insurance.
Get direct help first if…
- You just had a loss and the insurer denied the claim: call your state insurance department's consumer line; the link is at the end.
- Your question is about mortgage insurance (PMI or MIP): that is a different insurance, which protects the lender; the loan types guide explains it.
Home insurance is the bill people understand least and pay most without looking. It arrives with the closing, gets collected along with the mortgage and only becomes important the day something happens. This guide explains, using what the CFPB, the NAIC (the association of each state’s insurance regulators), the Texas and California insurance departments and FEMA publish, what you buy when you buy a policy, how much to insure, how much it adds to your payment, what is left out and what rights you have if the policy lapses.
- Of premiums you usually pay at or before closing when you buy a home
- 6 to 12 months9
- How long an NFIP flood policy takes to go into effect, with exceptions
- 30 days12
- The two written notices you must get before you are charged for force-placed insurance
- 45 and 15 days6
- The most the NFIP covers for flood damage to a home's building
- $250,00012
What it is and why you are asked for it
According to the CFPB, homeowner’s insurancehomeowners insuranceHomeowners insurance pays for losses and damage to your property if something unexpected happens, like a fire or a burglary, and usually includes liability coverage if someone is hurt at your home. Lenders require it as long as you have a mortgage, because the home is their collateral, and almost always collect it inside your monthly payment through the escrow account. The price depends on the location, the rebuilding cost, the deductible and your history. A standard policy does not cover floods or, in many states, earthquakes: those risks are insured separately.See the full definition pays for losses and damage to your property if something unexpected happens, like a fire or burglary; it is also called “hazard insurance”. When you have a mortgagemortgageA mortgage is an agreement between you and a lender (a bank, a credit union or a mortgage company) that gives the lender the right to take your property if you do not repay the money it lent you, plus interest. Mortgage loans are used to buy a home or to borrow money against the value of a home you already own. You repay it in monthly payments that cover the principal (the money borrowed) and the interest, and often the property taxes and insurance as well. In Spanish, "hipoteca" and "préstamo hipotecario" mean the same thing.See the full definition, the lender wants to make sure the property is protected by insurance and generally requires proof of coverage; many homeowners pay for it through the escrow account as part of the monthly payment. And it is yours: you can shop separately and choose the provider and plan that suit you.1 In Texas, for example, the Department of Insurance explains that the law does not require you to have home insurance, but that if you still owe money on your home, your lender will require it.10
The escrowescrow accountAn escrow account is an account set up by your mortgage lender to pay certain property-related expenses on your behalf, mainly property taxes and homeowners insurance. The money comes from a portion of your monthly mortgage payment: each month you contribute a share and the loan servicer pays the bills when they come due. That is why your payment is higher than principal and interest alone, and why it can change when taxes or the insurance premium go up. In some states the word also names the period between the offer and the closing.See the full definition account is set up by your lender to pay certain property expenses; many lenders require taxes and insurance to be paid through it, and the loan servicerloan servicerThe loan servicer is the company that sends you your mortgage statements and handles the day-to-day tasks of the loan: it processes your payments, answers your questions, keeps track of principal and interest paid and manages your escrow account, if you have one. It can also offer options if you fall behind and, in certain cases, start a foreclosure. It may be the same company that lent you the money or a different one, and it is common for another company to take over the loan after closing.See the full definition pays those bills for you.7 That is why, when the insurance premiuminsurance premiumAn insurance premium is what you pay the insurance company in exchange for your policy's protection. It can be paid in one lump sum or, more often, in periodic installments for the life of the contract. Each company decides whether to sell you a policy and how much to charge. For home insurance it usually looks at the cost to rebuild the home, building materials, location, nearness to a fire station, your past claims and, at some companies, your credit score. Discounts can lower it. If you stop paying the premium, the company can cancel your policy.See the full definition goes up, your monthly payment goes up even if your rate is fixed. When you buy, the CFPB says you usually pay the first 6 to 12 months of premiums at or before closing.9
What a typical policy covers
The NAIC describes the parts of a homeowners policy:2
| Part of the policy | What it covers |
|---|---|
| Damage to the house | The structure; the policy’s face amount is the most you will receive |
| Other structures | A detached garage, a shed, the fences |
| Personal property | Your belongings: furniture, clothes, appliances |
| Additional living expense | What you spend extra if you cannot live in the house while it is repaired |
| Personal liability | Protects you against claims from accidents to other people on your property |
| Medical expense | Paid regardless of legal liability |
Each part has its own limit. When you compare policies, compare the limits of all six, not just the price.
How much to insure: replacement, actual value and deductible
Here is the decision that changes a claim’s outcome the most. According to the NAIC, replacement cost is the amount it would take to replace or rebuild your home or repair damages; actual cash value is the amount it would take to repair or replace it after depreciation. The NAIC says it is important to insure your home for at least 80 percent of its replacement value. The deductibledeductibleA deductible is the part of an insurance claim you pay yourself. When you have a covered loss, the insurance company subtracts the deductible from the claim amount and pays you the rest. You may have a different deductible for each type of coverage. You will find it on the first page of your policy, called the declarations page, along with your coverages and limits. In taxes, the word "deductible" means something else: an expense that can lower the taxes you owe.See the full definition is the amount you pay out of pocket on each claim, and higher deductibles may be available at a reduced price.2
The Texas Department of Insurance explains it with a roof. The difference comes out of your pocket:10
Replacement cost or actual cash value, with the Texas example
Today's prices
Replacement cost
Ask which kind of coverage your policy has, for the house and for your belongings, before you compare prices.
What about the face amount? The California Department of Insurance points out that home insurance generally does not cover the value of the land, so the figure should reflect the cost of labor and materials to rebuild, not swings in the real estate market. Each company uses its own formula, so two insurers may suggest different limits.11
How much it adds to your monthly payment
The premium is set by the insurance company you choose, not the lender, so the only real figure is the one in your quotes.9 To show how insurance fits into your payment, our mortgage calculator uses an example rate. It is not an average or a quote: it shows the order of magnitude.
Example with real numbers
Insurance in the payment on a typical home, per the calculator's example
With the typical US home value and an example insurance rate; your real premium comes from your quotes.
- Typical US home value (Census, ACS)
- $332,700
- Home insurance per month, at the calculator's example rate
- $139
- Property tax per month, at the typical effective rate (Census)
- $261
With escrow, the insurance and the tax are collected in your monthly payment and the servicer pays them for you.7 Replace the insurance figure with your quote to see your real payment.9
Run it with your numbersMortgage calculator
If the premium goes up at renewal, your escrow payment goes up. The property tax guide explains how the servicer reviews that account every year, and the mortgage calculator lets you enter your real premium.
What it does not cover: flood and earthquake
The NAIC notes that floods and earthquakes are not covered by a typical homeowners policy,2 and the CFPB adds that you may be able to add that coverage.1 For flooding there is a federal program: FEMA’s National Flood Insurance Program (NFIP). Most homeowners insurance does not cover flood damage; homes and businesses in high-risk areas with federally backed mortgages are required to have flood insuranceflood insuranceFlood insurance is a separate policy that can cover a building, its contents, or both, when flood water causes damage. Most homeowners insurance policies do not cover that damage. Most of these policies are backed by FEMA's National Flood Insurance Program (NFIP) and bought through insurers and agents. If your home is in a high-risk flood area and your mortgage is backed by the federal government, the lender is required to demand it; outside those areas it is optional, but floods happen there too.See the full definition; there is typically a 30-day waiting period for an NFIP policy to go into effect; and you buy it by calling your insurance company or agent, the same person who sells your home or auto insurance.3
FloodSmart, the NFIP’s website, gives the details. For a home, building policies cover up to $250,000 of flood damage and contents policies up to $100,000 of damage to your belongings; the two are bought separately and have separate deductibles. Every company selling NFIP policies charges the same rates. The policy lasts one year, and it does not cover, among other things, what you keep in a basement or temporary housing while repairs are made. The 30-day wait has exceptions: there is no wait if you buy the insurance while making, increasing, extending or renewing a mortgage.12
The requirement comes from federal law: a regulated lending institution may not make a loan secured by real estate in a special flood hazard area where flood insurance is available unless the building is covered by flood insurance for the term of the loan, in an amount at least equal to the loan balance or the maximum coverage available, whichever is less. If the lender finds coverage missing, it must notify you to buy it at your expense and, if you do not buy it within 45 days of the notice, it may buy it and charge you.5 Some banks require it even if you don’t live in a high-risk area.13
To find out which zone you are in, FEMA’s Flood Map Service Center is the official public source: you search by address, place or coordinates to see the official map, and printed information may be superseded by new maps.4 High-risk zones are the ones marked A or V on those maps; if you don’t have a government-backed mortgage, FEMA still strongly recommends flood insurance in those zones.14
How to compare and pay less
The NAIC is clear: you are not required to buy insurance from the company your lender recommends; there are unbiased sources to find out what insurers charge for identical coverage, including your state insurance department; you should check with your agent at least once a year that your coverage is adequate; and a home inventory helps you decide how much coverage you need and should be stored in a safe, accessible place.2 The California Department of Insurance says to compare each company’s prices, coverage, conditions and complaint information.11
For the comparison to be useful, ask for quotes with the same numbers: the same face amount, the same deductible and the same optional coverages. Ask about discounts for a new roof, alarms, storm shutters or having your car with the same company, and ask what happens to the premium after the first claim. The link to each state’s insurance department is at the end of the guide.
If the policy lapses: force-placed insurance
If you stop paying the premium or do not send proof of coverage, the CFPB warns that the lender may buy insurance and charge you, and that policy may protect only the lender and cost more.1 But there are rules. Under Regulation X, force-placed insurance is hazard insurance the servicer buys on behalf of the loan’s owner on your property; it may not charge you for it unless it has a reasonable basis to believe you failed to maintain the required insurance and has delivered or mailed you a written notice at least 45 days before charging and a reminder at least 15 days before. And within 15 days of receiving proof that you did have coverage, it must cancel that policy and refund the premiums and fees for the period when the two coverages overlapped.6
In practice: open the servicer’s letters, send the declarations page of your new policy every time you switch insurers and keep proof that you sent it. If you were charged for force-placed insurance while you had your own, claim the refund with that proof.
When something happens: the claim step by step
From the damage to the payment, per the Texas Department of Insurance
1. Tell your company
As soon as possible
Most companies have deadlines to file a claim. The number is on your policy's declarations page.10
2. Document the damage
Before repairs
List what was damaged and, if you can, take pictures or videos before any repairs.10
3. Temporary repairs only
While you wait
Board up windows or tarp the roof. If you make permanent repairs before they see the damage, the company might deny the claim.10
4. Keep the receipts
Always
For what you buy to make repairs and what you replace: you may need them to get full payment.10
5. Be there with the adjuster
Inspection day
Try to be present when the adjuster looks at the damage.10
6. If you disagree
After the offer
Tell the company why. Appraisal is for disputes about the amount, not about whether the policy covers the loss.10
Ask in writing what is covered and what is not, and why. In Texas, if it is not resolved, you can file a written complaint with the Department of Insurance;10 your state insurance department’s consumer line can tell you how it works where you live. And a HUD-approved housing counselorHUD-approved housing counselorA HUD-approved housing counselor works at an agency HUD has approved to provide housing counseling: independent, expert advice customized to your situation about buying a home, renting, a missed mortgage payment, a foreclosure or credit problems. The agencies usually charge little or nothing; many serve in Spanish and offer the homebuyer education course several assistance programs require. They are not lenders or real estate agents and sell you nothing. Your county page lists the official agencies with phone numbers.See the full definition can advise you if the damage complicates your mortgage payments: they give independent advice on missed payments and credit, often free or at low cost.8
Depending on your situation
If this is you
You are about to close
The lender asks for proof of insurance, but you choose the company.1 You usually pay the first 6 to 12 months at or before closing.9
You rent your home
The NFIP also has policies for renters that protect your belongings from floods.12 Ask about renters insurance too.
You got a force-placed insurance letter
Send your proof of coverage: within 15 days they must cancel that insurance and refund the charges for the overlapping period.6
You just had damage
Tell your company as soon as possible, take photos and make only temporary repairs.10
If you just bought, the first year as a homeowner guide puts insurance together with the home’s other bills and dates.
Costly mistakes
Mistake: Insuring the house for the purchase price.
Instead: Think about the cost of labor and materials to rebuild, not the real estate market.11
Mistake: Choosing a deductible you could not pay.
Instead: The deductible comes out of your pocket on every claim: pick one you can really cover.10
Mistake: Buying flood insurance when the storm is already coming.
Instead: An NFIP policy usually takes effect 30 days after you buy it.12
Mistake: Making permanent repairs before the adjuster comes.
Instead: Make only temporary repairs and document the damage with photos.10
Mistake: Ignoring the servicer's letters about your insurance.
Instead: Answer with your proof of coverage: they must notify you 45 and 15 days before charging you for force-placed insurance.6
What to do this week
- Look up your address at FEMA’s Flood Map Service Center and note your zone.4
- Ask your agent for the estimated rebuilding cost and compare it with your policy’s face amount.11
- Ask whether your policy pays replacement cost or actual cash value, and what your deductible is.10
- Get two more quotes with the same numbers and consult your state insurance department.2
- Record your home inventory and upload it to the cloud.10
- If you live in a flood or hurricane area, ask about an NFIP policy today: it takes about 30 days to go into effect.12
Your numbers
Starts at the typical home value in the United States. Change it to the price you have in mind.
That is $11,645 (3.5% of the price). The usual minimum for this loan is 3.5%.
This week's average ± a quarter or half point.
National average as of November 5, 2026 (Freddie Mac); your rate may be different.
Adjust advanced details
Let's do the math
Estimated monthly payment
National figure$2,759
at 7.18% · 30 years
- Loan amount
- $326,673
- Total interest
- $470,006
- Paid off in
- November 2056
Includes $5,618 FHA upfront mortgage insurance premium.
Does it fit the income?
Comfortable
up to $1,884 a month
Tight
$1,884 to $2,422 a month
Hard
more than $2,422 a month
Your payment · 41%
Compared with the typical household income in the United States ($80,734 a year). Reference: HUD calls paying more than 30% of income for housing a cost burden.
| Principal & interest | $2,213 |
|---|---|
| Property tax | $261 |
| Home insurance | $139 |
| FHA mortgage insurance (MIP) | $147 |
How does it compare with incomes?
For this payment to be 28% of your income, you'd need to earn about $118,260 a year. With your other debts, to stay under 36%: about $91,980 a year.
You need at least $11,645 for the down payment, plus closing costs.
This is an estimate to give you an idea, not a loan offer. Your real payment depends on your rate, your credit, and the insurance and taxes on the home you buy.
Total monthly payment $2,759; principal and interest $2,213.
Ready to see the numbers? Find your county here
See how this applies in your county: its loan limits, prices and rents, from the official data.
Printable checklist
Frequently asked questions
Can I choose my own insurer even if the lender recommends one?
Yes. You can shop separately and choose the provider and plan; the NAIC reminds you that you are not required to buy from the company your lender recommends. What the lender can require is proof of coverage.
How much do I insure the house for: what I paid or what it would cost to rebuild?
For replacement cost, that is, what it would cost to rebuild or repair it, which is not the purchase price (the land does not burn). The NAIC says to insure at least 80 percent of that value and to review it with your agent at least once a year.
Do I need flood insurance if I do not live near a river?
The typical policy does not cover floods. Look up your address at FEMA's Flood Map Service Center: if you are in a special flood hazard area and have a federally backed mortgage, it is mandatory, and some banks require it even if you don't live in a high-risk area. If it is not required, the decision is yours; an NFIP policy takes effect 30 days after you buy it, with exceptions such as buying it when you take out the mortgage.
What happens if I forget to pay the policy?
The loan servicer may buy force-placed insurance and charge you, and it is usually more expensive and may protect only the lender. First it has to notify you in writing at least 45 days ahead and remind you 15 days ahead; if you prove you had coverage, it must cancel it and refund the overlapping period.
How much does home insurance cost?
It depends on the home, the location, the coverage and the deductible, and the premium is set by the insurance company you choose, not by the lender. Get quotes using the same numbers. The insurance figure in our calculator comes from an example rate: it shows how your payment changes, but it is not a quote or an average.
When do I pay for insurance when buying a home?
According to the CFPB, you usually pay the first 6 to 12 months of premiums at or before closing. After that, if you have an escrow account, the insurance goes into your monthly payment and the loan servicer pays it for you.
What is the difference between replacement cost and actual cash value?
Replacement cost pays to repair or replace at today's prices; actual cash value pays that minus depreciation. In the Texas Department of Insurance's example, for a 10-year-old roof that costs $10,000 to replace today and a $2,000 deductible, you pay $2,000 out of pocket with replacement cost and $5,000 with actual cash value.
What do I do if I disagree with what the insurer offers?
The Texas Department of Insurance recommends telling the company why you disagree. If that does not resolve it, one option is appraisal, which is for disputes about the amount, not about whether the policy covers the loss. In Texas you can also file a written complaint with the Department; ask your state insurance department how it works where you live.
Sources
Every figure in this guide comes from one of these official sources. The number next to a sentence leads to the source behind it.
Each source on one line: who publishes it, its title, its address and the date we read it.
- 1. CFPB · What is homeowner's insurance? Why is homeowner's insurance required? · consumerfinance.gov · Accessed October 17, 2026
- 2. NAIC (National Association of Insurance Commissioners) · Homeowners Insurance (consumer guide) · content.naic.org · Accessed October 16, 2026
- 3. FEMA · Flood Insurance (National Flood Insurance Program) · fema.gov · Accessed October 16, 2026
- 4. FEMA · FEMA Flood Map Service Center · msc.fema.gov · Accessed October 17, 2026
- 5. U.S. Congress (text at Cornell LII) · Flood Disaster Protection Act, 42 U.S.C. §4012a, Flood insurance purchase and compliance requirements · law.cornell.edu · Accessed October 17, 2026
- 6. CFPB (Code of Federal Regulations, text at Cornell LII) · Regulation X, 12 CFR §1024.37, Force-placed insurance · law.cornell.edu · Accessed October 17, 2026
- 7. CFPB · What is an escrow or impound account? · consumerfinance.gov · Accessed October 17, 2026
- 8. CFPB · Find a Housing Counselor · consumerfinance.gov · Accessed October 17, 2026
See the other 6 sources
- 9. CFPB · Loan Estimate Explainer · consumerfinance.gov · Accessed October 17, 2026
- 10. Texas Department of Insurance (TDI) · Home insurance guide · tdi.texas.gov · Accessed October 17, 2026
- 11. California Department of Insurance (CDI) · Residential Insurance: Homeowners and Renters · insurance.ca.gov · Accessed October 17, 2026
- 12. FEMA, National Flood Insurance Program (FloodSmart) · What you need to know about buying flood insurance · floodsmart.gov · Accessed October 17, 2026
- 13. FEMA, National Flood Insurance Program (FloodSmart) · Flood insurance eligibility · floodsmart.gov · Accessed October 17, 2026
- 14. FEMA, National Flood Insurance Program (FloodSmart) · What is my flood zone? · floodsmart.gov · Accessed October 17, 2026
Keep reading
Related guides
If this guide helped, these follow the same path.
Owning a home 13 minute read
Property tax explained: how it is calculated and paid
Who charges property tax, how it is calculated, how it is paid through escrow, which exemptions and appeals exist and what part is deductible.
- It is a local tax: assessed value of the home × the rates of the county, city and school district, minus exemptions. Your county sets the bill.
- With a mortgage you pay it through escrow: the servicer collects it in your monthly payment, pays it for you and reviews the account every year; a shortage is repaid over at least 12 months.
- Exemptions (such as the primary residence one) and the appeal of the assessed value have deadlines; they are on your state's page with their source.
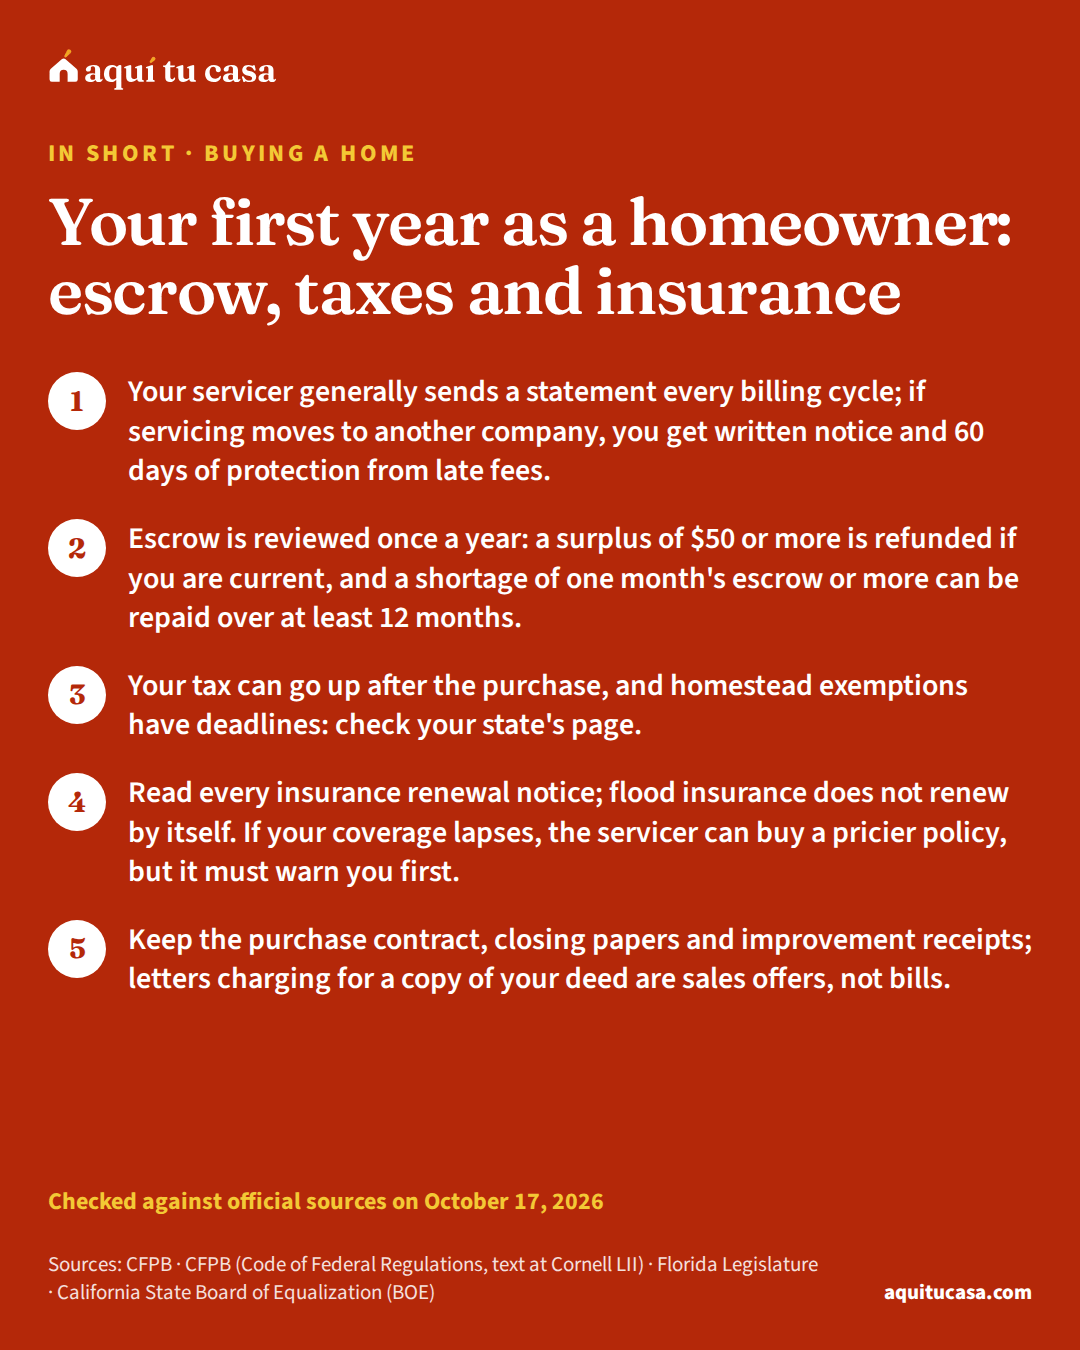
- Buying a home Your first year as a homeowner: escrow, taxes and insurance Who collects your mortgage and what happens if that changes, the yearly escrow review, taxes, exemptions, insurance, records and scams aimed at new owners. 13 minute read
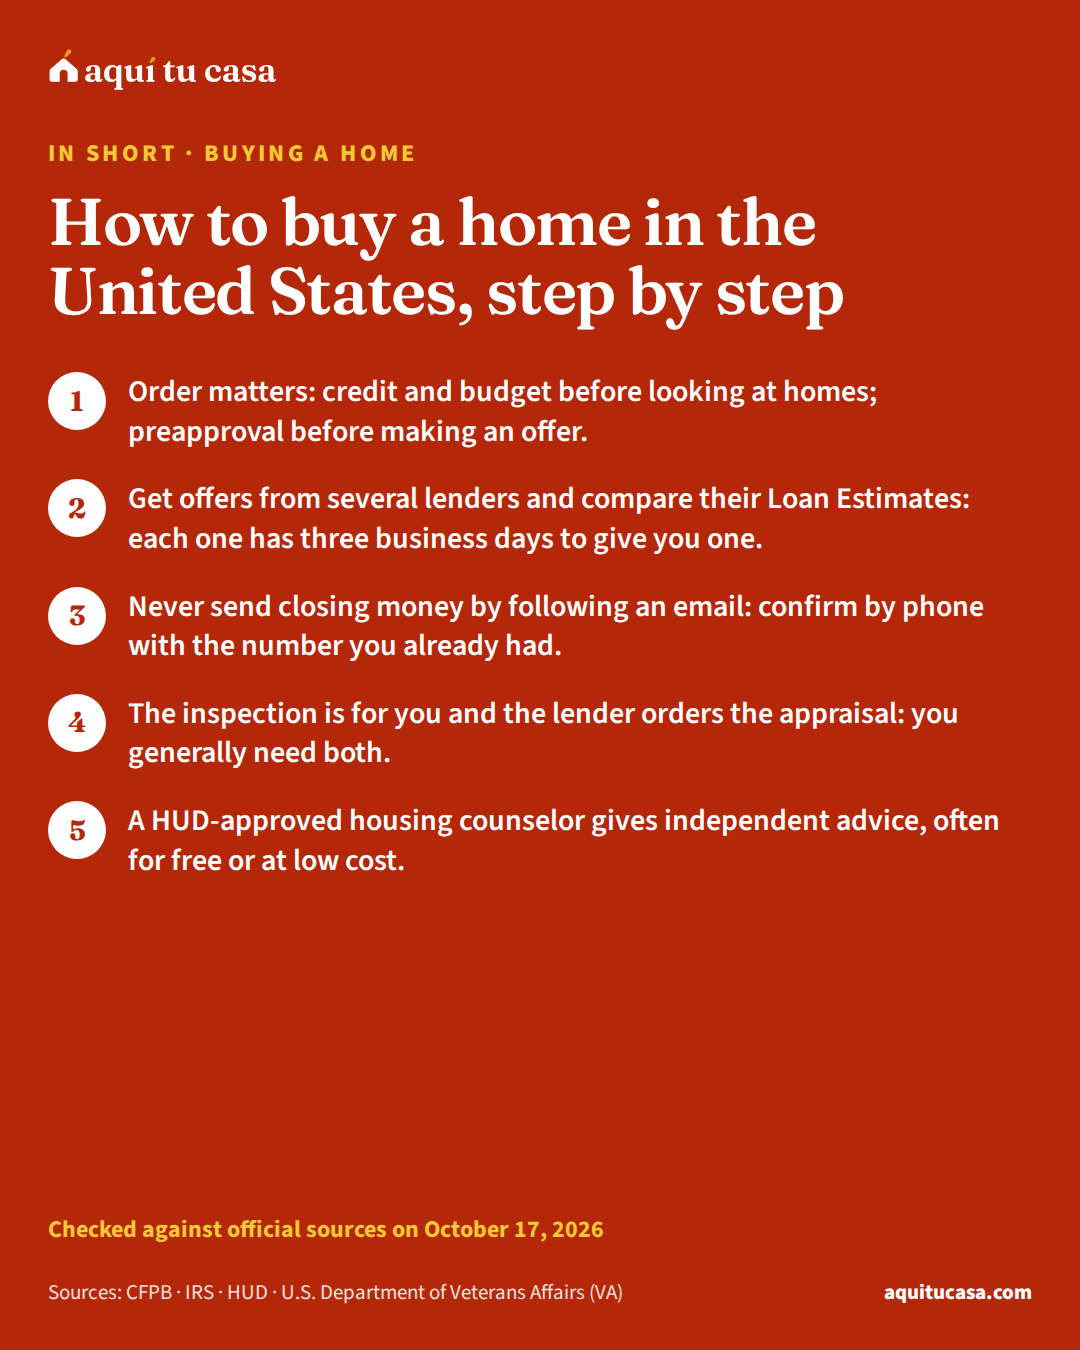
- Buying a home How to buy a home in the United States, step by step The nine steps to buying a home: paperwork, credit, budget, assistance, preapproval, offer, inspection, closing and the first year, with official sources. 15 minute read
- Buying a home Closing costs explained: what you pay and what can change What closing costs are, how to read them on your Loan Estimate, which charges cannot go up before closing and how to compare offers to pay less. 14 minute read
Tools for this topic
Was this guide useful?
Thank you. Your answer stays in your browser; nothing is sent.