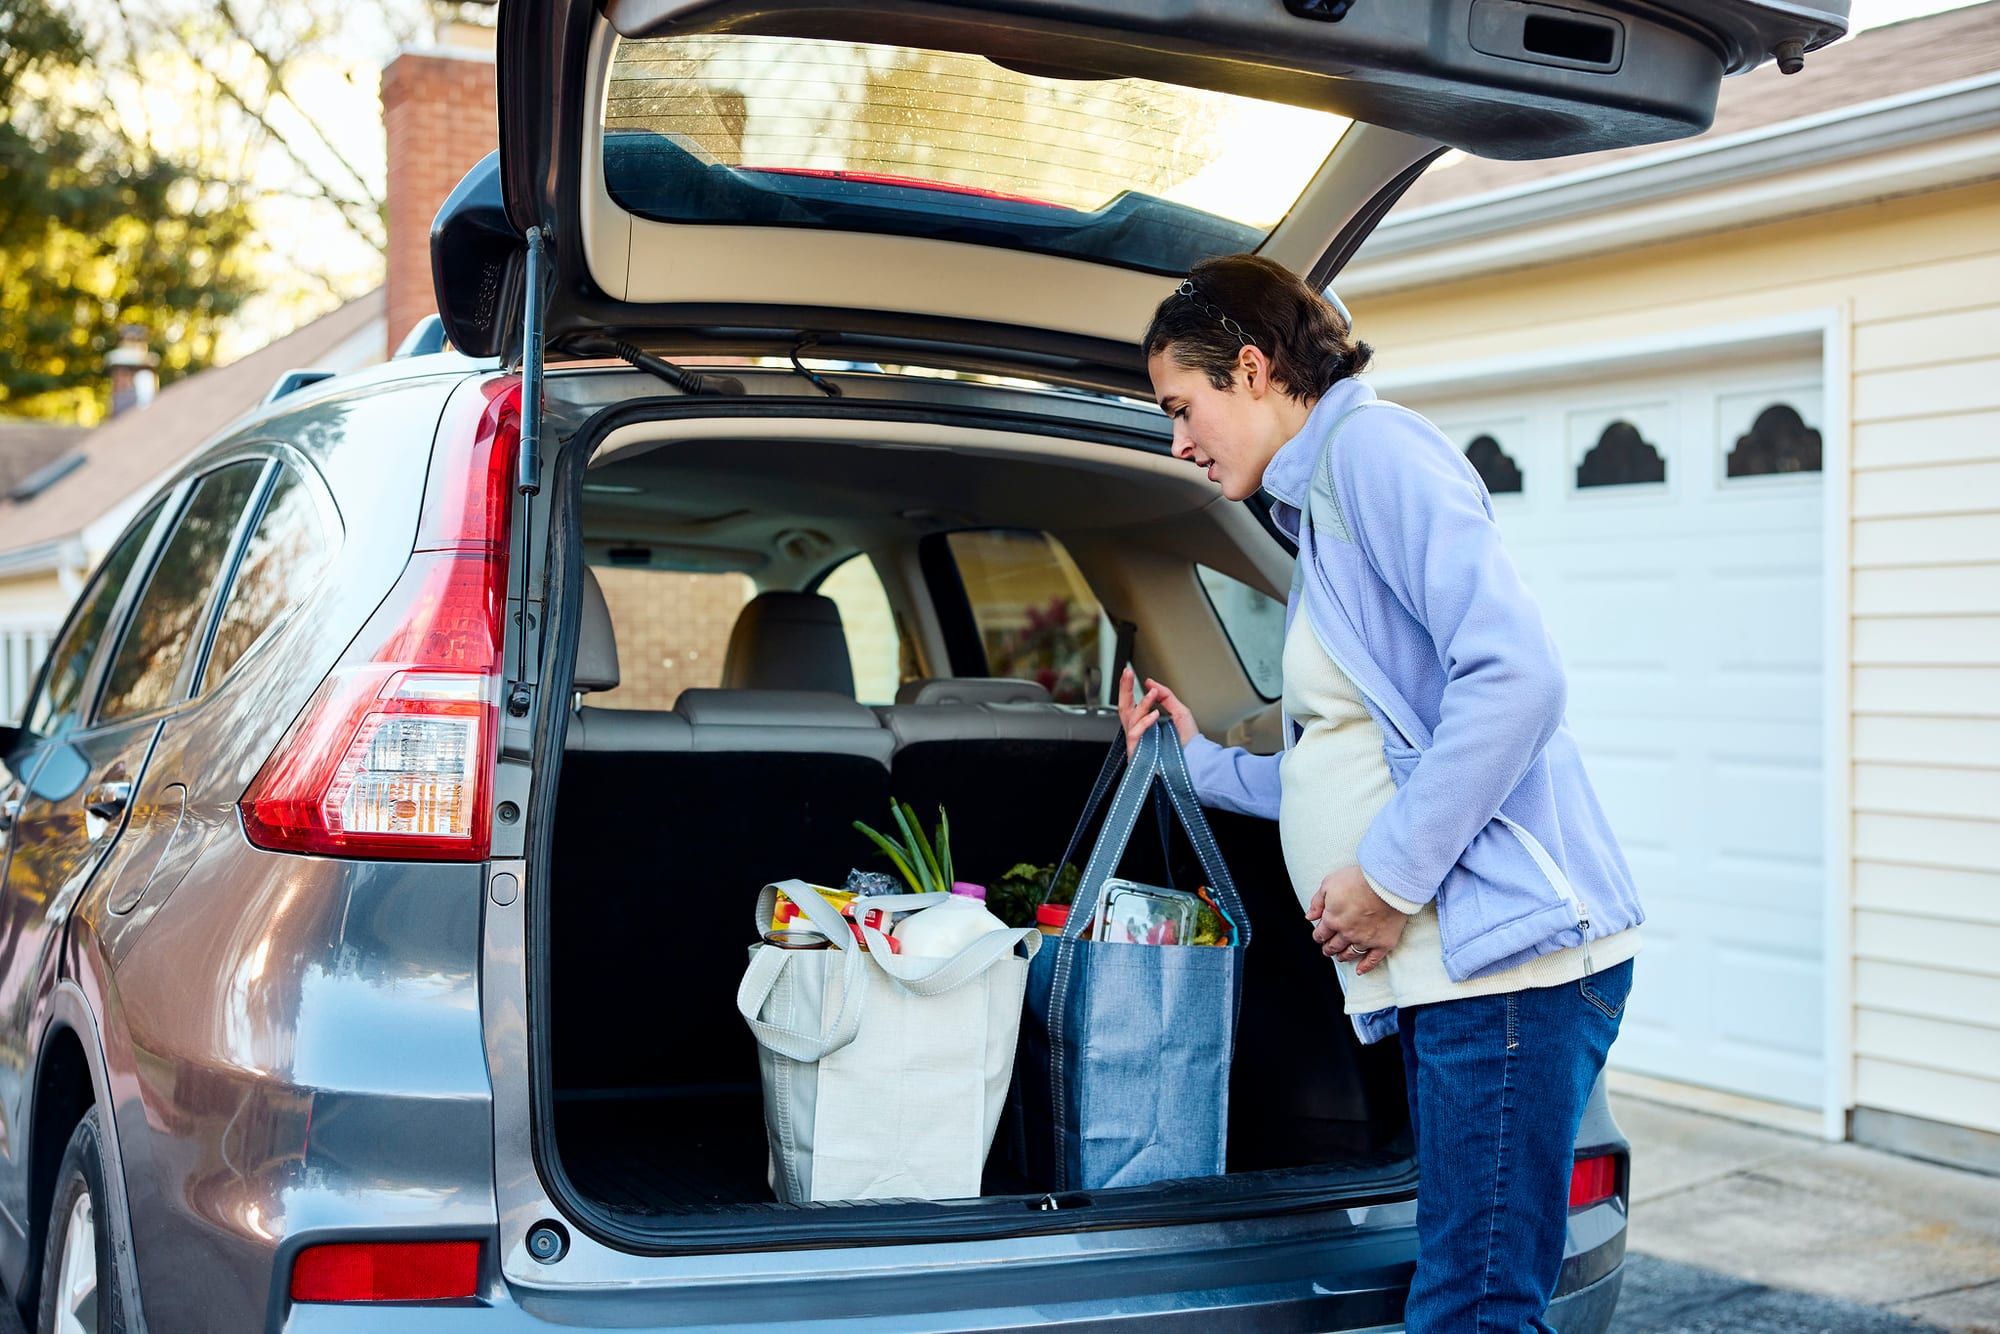
What moves your credit score: the five factors
What raises and lowers your credit score according to the CFPB, FICO and VantageScore: on-time payments, credit use, age, new credit and account mix.
Verified against official sources on October 17, 2026 21 official sources
Show contents
In short
What you need to know
Quick answer
What moves your score the most is paying on time: most scoring models treat it as the number one factor. After that come how much of your limit you use (experts cited by the CFPB advise staying at or below 30%), how long your accounts have been open, new applications and the kinds of credit you handle. FICO and VantageScore publish these factors on their own scales, and neither uses your national origin or your salary. Checking your own report or score does not lower it.
What matters most
- Paying on time weighs the most: FICO gives it 35% of its score and VantageScore calls it extremely influential.
- Use little of your limit: experts cited by the CFPB advise staying at or below 30%, and you do not need to carry a balance for a good score.
- Closing an old card or opening several accounts in a row can lower your score.
- Checking your own report or score, or freezing your credit, does not lower your score.
Is this for you?
This guide is for you if…
- You already have a card or a loan and want to understand why your score goes up or down.
- You plan to apply for a mortgage in the coming months and want to know what the lender looks at.
- You saw different numbers at your bank, in an app and in a letter, and you do not know which one is right.
Get direct help first if…
- You do not have any credit account yet: start with the Credit from zero guide.
- You found a wrong item on your report: the guide to disputing errors tells you what to send and to whom.
- A debt collector is calling you: that situation has its own rules and its own guide.
Your credit score goes up and down for concrete reasons, and almost all of them are in your credit report. This guide is for anyone who already has an account, or is about to open the first one, and wants to understand what moves the score. We put what the CFPB (the federal consumer financial protection agency) publishes next to what the two companies behind the most widely used scores, FICO and VantageScore, say about their own models.
What the score is and who calculates it
Your credit scorecredit scoreA credit score is a number that predicts how likely you are to pay back a loan on time. It is computed from the information in your credit report: whether you pay on time, how much you owe relative to your limits, how long you have used credit and how many new accounts you opened. FICO is one brand of score; VantageScore is another, and each lender decides which one it uses. A higher score usually brings a lower interest rate and more loan options; each program publishes the minimum it accepts. You can check your report for free and dispute errors.See the full definition is a prediction: how likely you are to pay a loan back on time, calculated from what your credit reportscredit reportA credit report is a statement that has information about your credit activity and current credit situation: your loans and cards, the balances, whether you have paid on time, accounts in collection and who has checked your credit. Credit reporting companies, also called credit bureaus, compile it from what banks and creditors report; your credit score is computed from it. When you apply for a mortgage, the lender pulls your report from the three bureaus. You have the right to see it for free and to dispute anything that is wrong.See the full definition say. A formula called a scoring model creates it. Companies use it to decide whether to give you a mortgage, a card or a car loan, and also to screen tenants and price insurance. Most scores range from 300 to 850, and a higher score usually makes it easier to qualify and may get you a better rate.1
You do not have just one score. Each one depends on the model, the credit reporting agency the data comes from and even the day it is calculated.1 The two names you will see most often are:
- FICOFICO scoreFICO is a brand of credit score: a number that helps lenders gauge how likely you are to pay back a loan. There are several versions of the FICO score, and each weighs the information in your credit report a little differently, which is why you do not have just one score. For a long time, mortgages sold to Fannie Mae and Freddie Mac used a version called Classic FICO; the FHFA now lets lenders choose between Classic FICO and VantageScore 4.0. To keep a good score, the CFPB advises paying on time and not using too much of the credit available to you.See the full definition. A brand of credit score. It has several versions, and each one weighs the information in your report a little differently. Fannie Mae, Freddie Mac and others use certain versions for home loans.2
- VantageScoreVantageScoreVantageScore is a credit scoring model separate from FICO. Like any score, it uses a mathematical formula (a scoring model) to estimate, from the data in your credit report, how likely you are to pay on time. The FHFA, the federal agency in charge of Fannie Mae and Freddie Mac, approved the VantageScore 4.0 version, which takes into account additional sources of data, such as rent payment history. Today, for mortgages sold to those two companies, lenders may use VantageScore 4.0 or Classic FICO, but they must use the same model for every borrower on the same loan.See the full definition. Each of the three nationwide agencies (Experian, Equifax and TransUnion) calculates it using rules VantageScore provides. The company makes clear it is not a credit bureau and does not hold your data.5
That is why it is normal to see slightly different numbers at your bank, in an app and in a lender’s letter: lenders use different scores for different kinds of loans.17
The five factors, side by side
The CFPB lists what scoring models usually look at: whether you pay your bills on time, what you owe now, how many accounts you have and of what type, how long they have been open, how much of your available credit you use and your new applications. It also counts whether you have had a debt sent to collection, a foreclosure or a bankruptcy, and how long ago.1
FICO and VantageScore group that data in similar ways, but each publishes its own scale. FICO gives percentages;3 VantageScore ranks its factors from most to least important, in words.4
| Factor | What it looks at | FICO (published weight) | VantageScore (published level) |
|---|---|---|---|
| Payment history | Whether you pay on time, late payments and collections | 35% | Extremely influential |
| Amounts owed | Your balances and how much of your limits you use | 30% | Total credit usage: highly influential. Balance and available credit: less influential |
| Length of history | How long your accounts have been open | 15% | Grouped with credit mix: highly influential |
| New credit | Recently opened accounts and applications | 10% | Moderately influential |
| Credit mix | Cards, installment loans, mortgage | 10% | Grouped with length of history |
FICO makes two important points. First, those percentages show each group’s general importance, and that importance can vary from one person to another. Second, there is no way to measure the exact effect of a single item without looking at the whole report.3 Be wary of anyone who tells you, without seeing your report, how many points you will gain.
FICO and VantageScore, in their own words
Weights in percent
FICO
- Groups your data into five categories: payment history (35%), amounts owed (30%), length of history (15%), new credit (10%) and credit mix (10%).3
- Only counts inquiries from the last 12 months, although they stay on your report for two years.3
- Does not use your race, national origin, marital status or salary.3
Both reward the same habits: paying on time and using little of your limit.7
Payment history: what weighs the most
Most credit scores treat repayment history as the number one factor.7 FICO explains why: how you have paid tends to be the strongest predictor of whether you will pay your debts as agreed.3
“On time” means the payment reaches the company by the day the bill is due. If you pay by mail, send it a few days early.8 An automatic payment or an electronic reminder keeps you from forgetting; if you have already fallen behind, get current and stay current.7
One late payment does not erase everything else. FICO says an overall good history can outweigh one or two late credit card payments.3 And the CFPB says recent negative information generally affects your score more than older information.8 Negative marks do not last forever, but they do last a while: credit reporting companies can generally report negative payment information for up to seven years, and a bankruptcy for up to ten. Positive information can be reported for longer.12
Power, water, phone and cable companies rarely send your on-time payments to the big three agencies. But if you stop paying one and the debt goes to a collectioncollection accountA collection account is a past-due debt that the original creditor (the company that gave you the loan or credit) handed to a debt collector or sold to another company. A debt collector is a person or company that regularly collects debts owed to others, such as a collection agency, a lawyer or a debt buyer. The account can show up on your credit report; once you pay it, it should generally show a zero balance as a paid collection. Most negative information can be reported for up to seven years. If you think you do not owe the debt or the amount is wrong, you can dispute it with the collector and with the credit reporting company.See the full definition agency, it can show up on your reports.13
How much of your limit you use
Scoring models look at how close you are to being maxed out.7 That proportion is called credit utilizationcredit utilizationCredit utilization is how much of your credit limits you are using: it compares what you owe on your cards with your total available credit. Scoring models look at how close you are to being maxed out; if you use too much of your limit, your score can drop. According to the CFPB, experts advise using no more than 30% of your total credit limit. If you close cards and move the balances onto one, the share you use can go up. You do not need to carry a balance to have a good score: paying in full each month helps.See the full definition: the credit you are using divided by the total you have available.9
The CFPB cites experts who advise using no more than 30% of your total limit, and others who say less than 10%.8 VantageScore gives this example: with a card that has a $1,000 limit, it is best not to carry a balance of more than $300.4 And you do not need to carry a balance to get a good score: paying the full balance each month helps you get the best scores and keeps your interest low.7
Example with real numbers
How your utilization is calculated
An example in words: the math is the same with any numbers.
- What you owe today on all your cards
- Your total balance
- What you can borrow in total (the sum of your limits)
- Your total limit
- Your utilization
- Total balance ÷ total limit
If you close a card, your total limit goes down and your utilization can go up.9 Experts cited by the CFPB advise keeping it at 30% or less.7 Plan your steps with your own numbers in the credit plan.
Run it with your numbersCredit planThat is why moving all your balances onto one card and closing the others can lower your score, if you end up using a large share of your total limit.7
Closing a card is not an automatic improvement either. The CFPB says not to assume it will raise your score: it can push your utilization up. Many people keep an old account with a good history open because it may help maintain a higher score. Closing it can make sense if it charges an annual fee or has poor terms, if it helps you avoid running up debt you cannot pay, or if you do not plan to apply for credit soon. If you keep it open without using it, watch your statements.9

Length of history, new credit and account mix
Length of history. A long history helps: the longer your report shows you paying as agreed, the more information there is to score.7 FICO looks at the age of your oldest account, your newest account and the average of all of them. It says a longer history is generally positive but is not required for a good score.3
New credit. Scoring models treat recent applications as a sign that you need credit. Many in a short time may make lenders think you are dealing with financial setbacks.7 That includes getting a new card to transfer balances or opening a store card to get a discount.8
When you apply for credit, the lender makes a hard inquiryhard inquiryA hard inquiry happens when a lender checks your credit report because you applied for a loan or a card, to decide whether to approve you. It can affect your score, because most scoring models look at how often and how recently you apply for credit, and other businesses that buy your report can see it. A single inquiry has little impact. Scoring models also allow for comparison shopping: several inquiries for the same type of loan, such as a mortgage, within a short period usually count as one.See the full definition, and that one does affect your score, because most models look at how recently and how often you apply for credit. Soft inquiriessoft inquiryA soft inquiry is a review of your credit file that does not affect your score. It includes reviews of your existing accounts by your lenders or insurers, prescreened offers from prospective lenders, employment screening and your own requests for your credit report. Only you see it when you review your report; businesses that buy your report do not. That is why checking your own credit report, even often, does not lower your score.See the full definition do not: your own check, prescreened offers and reviews of accounts you already have.10 FICO only counts inquiries from the last 12 months, although they stay on your report for two years.3 VantageScore says the effect of one inquiry is likely minor and temporary.5
Credit mix. FICO considers your mix: credit cards, retail accounts, installment loans, finance company accounts and mortgages. It also says you do not need one of each.3 Opening an account just to “round out the mix” adds a new application, and that counts too.7
What does not count in your score
Your score comes from your credit report, not from your whole life. FICO says it calculates its score only from the information in your report.3 It does not consider your race, color, religion, national origin, sex or marital status, or your salary, occupation or employer. A lender can still look at your income and job when deciding whether to lend to you, separately from the score.3 VantageScore says the same about its model and adds your age, where you live and your assets.4
These things do not lower your score:
- Checking your own report or score. Checking your own credit does not affect your scores.11
- Freezing your credit. A credit freezesecurity freezeA security freeze, also called a credit freeze, keeps new creditors from seeing your credit file, which helps stop an identity thief from opening new accounts in your name. By law it is free to place and to lift, and you must ask each of the three nationwide credit reporting companies separately. While it is on, only a few can see your file, such as creditors on accounts you already have, and you can still review your reports. It does not affect your score. Because creditors rarely lend without checking your file, it stops you too; you can lift it for free for a period of time when you need to.See the full definition does not affect your scores in any way.16
And these do not raise it: paying with a debit card or cash, or using a prepaid card, does not help rebuild your credit.8
Something that does count even if you do not expect it: a joint account, such as a card in both your names, affects both people’s scores.15 Creditors report voluntarily and you cannot ask them to stop reporting your accounts; what you can do is dispute anything that is wrong.14
If you are applying for a mortgage
For a mortgagemortgageA mortgage is an agreement between you and a lender (a bank, a credit union or a mortgage company) that gives the lender the right to take your property if you do not repay the money it lent you, plus interest. Mortgage loans are used to buy a home or to borrow money against the value of a home you already own. You repay it in monthly payments that cover the principal (the money borrowed) and the interest, and often the property taxes and insurance as well. In Spanish, "hipoteca" and "préstamo hipotecario" mean the same thing.See the full definition, the model may be different from the one you see in your app. According to FHFA (the federal agency that oversees Fannie Mae and Freddie Mac), lenders can currently choose between Classic FICO and VantageScore 4.0 for loans sold to those two companies, and they must use the same model for everyone who signs the loan. FHFA says the newer models take into account more data, including rent payment history, and that another newer model, FICO 10T, is not yet eligible for those loans.20 These rules are changing, which is why we review this guide more often.
Shopping around does not punish you. An inquiry typically has a small negative effect, and within 45 days multiple inquiries from mortgage lenders count on your report as one. That lets you get several preapprovalspreapproval letterA preapproval or prequalification letter is a document from a lender saying it is generally willing to lend you up to a certain amount. It is not a guaranteed loan offer. Lenders use the two words differently: some issue a prequalification based on information you report, without verifying it, and only issue a preapproval after reviewing your documents; others use the words the other way around or interchangeably. That is why it pays to ask what the letter is based on. Sellers often ask for one before accepting an offer.See the full definition and Loan Estimates. What you should avoid is applying for another card or a car loan right before or during the process.11 The guide Preapproval vs. prequalification covers the rest of the path.
When a lender checks your score to approve a mortgage, it also has to give you that score.19 That notice tells you which number you are being judged by. If your reports have hardly any accounts, read nontraditional credit for a mortgage, where we explain what Fannie Mae and HUD publish for borrowers without a score.
How to see what is moving your score
There are several ways to see your score without paying. The CFPB mentions your credit card statement (many companies show it every month), the scoring notice you get when you apply for a mortgage, the adverse action notice if you are turned down or offered worse terms, and nonprofit credit counselors and HUD-approved housing counseling agencies, which can often give you your report and score for free and help you review them.18
Be careful with “free score” services: some charge you every month if you do not cancel in time.18 If you decide to buy a score, you do not have to buy other services offered with it.17 And check what kind of score it is: for most people an “educational” score is similar to what lenders use,17 but a CFPB study found a meaningful difference for one out of four people.18
Read your score in this order
1. Get your three reports
Today
Your score comes from them, and checking them does not lower it. The guide AnnualCreditReport.com step by step walks you through it.11
2. Get a score at no cost
This week
Look on your card statement or ask a HUD-approved housing counselor.18
3. Read the reason codes
When you see your score
They tell you what is pulling it down: for example, balances too high compared to your limits, or too many inquiries.6
4. Start at the top of the list
Month by month
If the codes seem to conflict, work down the list and handle the most important factors first.5
5. Fix what is wrong
As soon as you see it
If an item is an error, disputing it is free and you can do it yourself.12
If this is you
You have little or no history
The FICO score comes only from what is in your report.3 A secured credit card is one way to start.
You pay rent every month
The newer models FHFA approved take rent history into account.20 See how to report your rent to the credit bureaus.
You share a card with your partner
A joint account affects both people's scores, for better and for worse.15
You are buying a home
Compare lenders within 45 days and do not apply for other cards or loans during the process.11

Mistakes that lower your score
Mistake: Closing your oldest card to 'clean up' your credit.
Instead: Closing it can raise your utilization and lower your score; the CFPB says not to assume it helps.9
Mistake: Leaving a balance on the card so it 'shows activity'.
Instead: You do not need to carry a balance: paying in full each month helps you get the best scores.7
Mistake: Applying for several cards in a row to see which one approves you.
Instead: Many applications in a short time weigh on your score; apply only for the credit you need.7
Mistake: Opening a store card in the middle of shopping for a mortgage.
Instead: Avoid other credit applications right before or during the mortgage process.11
Mistake: Paying for a subscription to see a 'free' score.
Instead: Your card company or a HUD-approved housing counselor can often give it to you at no cost.18
Mistake: Mailing the payment on the day it is due.
Instead: On time means it arrives that day: mail it a few days early or use autopay.8
What to do this week
- Get your three reports at AnnualCreditReport.com; checking them does not lower your score.11
- Find a free score on your card statement, or ask a housing counselor for one.18
- Add up your card balances and limits, and work out your utilization.9
- Set up an automatic payment or a reminder for each account.7
- If you plan to buy a home soon, do not open new accounts before you apply for your loan.11
- If you want to go over your numbers with someone, a HUD-approved housing counselorHUD-approved housing counselorA HUD-approved housing counselor works at an agency HUD has approved to provide housing counseling: independent, expert advice customized to your situation about buying a home, renting, a missed mortgage payment, a foreclosure or credit problems. The agencies usually charge little or nothing; many serve in Spanish and offer the homebuyer education course several assistance programs require. They are not lenders or real estate agents and sell you nothing. Your county page lists the official agencies with phone numbers.See the full definition gives independent advice on credit, often at little or no cost.21 To put your steps in order, use the credit plan.
Your situation
If you have never had a card or a loan in the U.S., choose "None".
Your credit plan
12 steps
You have done 0 of 12.
This week
Get your three credit reports for free
At AnnualCreditReport.com you can get the Equifax, Experian and TransUnion reports for free once a week. Checking your own report does not lower your score. If it comes up empty, that is not an error: you simply have no history yet.
Source: CFPB: How do I get a free copy of my credit reports? ↗ · CFPB: Does requesting my credit report hurt my credit score? ↗
Dispute any error in writing
Write to the credit bureau and to the company that reported the item, with copies of your proof, by certified mail. By law, the bureau must investigate again for free and resolve it within 30 days of receiving your notice.
Source: CFPB: How do I dispute an error on my credit report? ↗ · Congreso de EE. UU. (texto en Cornell LII): Fair Credit Reporting Act, 15 U.S.C. §1681i, Procedure in case of disputed accuracy ↗
Talk to a HUD-approved housing counselor
They give independent advice on buying, renting, defaults and credit, often free or at low cost. You can go over your report and your plan with them.
Source: CFPB: Find a Housing Counselor ↗
This month
Open a secured card
You deposit an amount (for example, $500) and can spend up to that amount. With on-time payments, the limit can go up, and the deposit comes back. Before signing, ask whether they report to all three bureaus and compare the annual fee and the rate: they can be high.
Source: CFPB: What are some ways to start or rebuild a good credit history? ↗ · CFPB: How to rebuild your credit ↗
Or a credit builder loan
The bank or credit union holds the money as savings while you make small payments, usually for six to 24 months; when you finish, you get it. You build history and savings at the same time.
Source: CFPB: What are some ways to start or rebuild a good credit history? ↗
Ask for your rent to be reported
On-time rent payments can help build your credit. Ask your landlord whether they take part in a rent reporting program (often through a payment app) and check its fees.
Set up automatic payments
An automatic payment or a reminder before the statement date prevents the costliest kind of slip: payment history is the main factor in most models.
What does not build credit
Paying with a debit card or cash, prepaid cards and payday loans do not build history, according to the CFPB. They are ways to pay, not accounts that get reported.
From here on
Do not close your first account
A long history of on-time payments helps your score. When a better card comes along, keep the first one open and current.
Only apply for the credit you need
Opening several accounts in a short time is a risk signal for lenders, and each application leaves a hard inquiry that does affect your score.
Source: CFPB: How do I get and keep a good credit score? ↗ · CFPB: What is a credit inquiry? ↗
Watch your debt-to-income ratio
Lenders divide your monthly debt payments by your gross monthly income to see whether you can handle a new loan. While you prepare, avoid new payments, such as a car.
Watch out for "credit repair"
It is a scam if they charge before doing anything, promise to remove accurate negative information, tell you not to contact the bureaus or to dispute everything. Disputing errors is free by law, and if you already signed up for something like this, you can cancel within three business days.
Source: CFPB: How can I tell a credit repair scam from a reputable credit counselor? ↗
An educational plan built on what the CFPB, the NCUA and the federal credit reporting law publish; not individual advice. We recommend no brands and are paid for no product.
Ready to see the numbers? Find your county here
See how this applies in your county: its loan limits, prices and rents, from the official data.
Printable checklist
Frequently asked questions
How much does one late payment lower my score?
The sources we checked do not give a fixed number: it depends on your whole report. FICO says an overall good history can outweigh one or two late credit card payments, and the CFPB says recent negative information weighs more than older information. Negative payment information can be reported for up to seven years.
Does checking my score or my report lower it?
No. Checking your own credit does not affect your scores: it is a soft inquiry. The ones that count are hard inquiries, made by a lender when you apply for credit.
Will closing a credit card raise my score?
Do not assume so. The CFPB explains that closing a card can raise your utilization, because your total limit goes down, and that can lower your score. Closing it can make sense if it charges an annual fee or helps you avoid debt, especially if you do not plan to apply for credit soon.
How much of my card should I use?
Little. Experts cited by the CFPB advise using no more than 30% of your total limit, and others say less than 10%. You do not need to carry a balance: paying in full every month helps you get the best scores and saves you interest.
Why do I have a different score in every app?
Because you do not have just one score. Each depends on the model, the credit reporting agency the data comes from and the day it is calculated, and lenders use different scores for different loans. Some apps also show an educational score: for most people it is close to what lenders use, but not always.
Do my income or my country of origin count in my score?
Not in the score. FICO says it does not use your national origin, salary or employer, and VantageScore says the same about its model, adding your age and where you live. A lender can still look at your income and job when deciding whether to lend to you.
Will getting preapproved with several lenders hurt my score?
According to the CFPB, multiple mortgage lender inquiries within 45 days count as a single inquiry. You can compare several preapprovals and Loan Estimates; what you should avoid is applying for other cards or loans right before or during the process.
Does paying rent on time raise my score?
Only if it gets reported. FHFA says the newer models approved for Fannie Mae and Freddie Mac take rent payment history into account. Our guide to reporting rent explains the options and the fees to watch.
Sources
Every figure in this guide comes from one of these official sources. The number next to a sentence leads to the source behind it.
Each source on one line: who publishes it, its title, its address and the date we read it.
- 1. CFPB · What is a credit score? · consumerfinance.gov · Accessed October 17, 2026
- 2. CFPB · What is a FICO score? · consumerfinance.gov · Accessed October 17, 2026
- 3. FICO (myFICO.com) · What's in your credit score? · myfico.com · Accessed October 17, 2026
- 4. VantageScore Solutions · How Credit Scores Work · vantagescore.com · Accessed October 17, 2026
- 5. VantageScore Solutions · Consumer FAQs · vantagescore.com · Accessed October 17, 2026
- 6. VantageScore Solutions · Consumer Education · vantagescore.com · Accessed October 17, 2026
- 7. CFPB · How do I get and keep a good credit score? · consumerfinance.gov · Accessed October 17, 2026
- 8. CFPB · How to rebuild your credit · consumerfinance.gov · Accessed October 17, 2026
See the other 13 sources
- 9. CFPB · Does it hurt my credit to close a credit card? · consumerfinance.gov · Accessed October 17, 2026
- 10. CFPB · What is a credit inquiry? · consumerfinance.gov · Accessed October 17, 2026
- 11. CFPB · What happens when a mortgage lender checks my credit? · consumerfinance.gov · Accessed October 17, 2026
- 12. CFPB · How long does information stay on my credit report? · consumerfinance.gov · Accessed October 17, 2026
- 13. CFPB · Does my history of paying utility bills, like telephone, cable, electricity, or water, go in my credit report? · consumerfinance.gov · Accessed October 17, 2026
- 14. CFPB · Can I opt out of having creditors report my accounts to credit reporting companies? · consumerfinance.gov · Accessed October 17, 2026
- 15. CFPB · Do joint credit card accounts with my spouse affect my credit score? · consumerfinance.gov · Accessed October 17, 2026
- 16. CFPB · What is a credit freeze or security freeze on my credit report? · consumerfinance.gov · Accessed October 17, 2026
- 17. CFPB · Where can I get my credit scores? · consumerfinance.gov · Accessed October 17, 2026
- 18. CFPB · Do I have to pay for my credit score? · consumerfinance.gov · Accessed October 17, 2026
- 19. CFPB · I got my free credit reports, but they do not include my credit scores. Can I get my credit score for free too? · consumerfinance.gov · Accessed October 17, 2026
- 20. FHFA · Credit Scores · fhfa.gov · Accessed October 17, 2026
- 21. CFPB · Find a Housing Counselor · consumerfinance.gov · Accessed October 17, 2026
Keep reading
Related guides
If this guide helped, these follow the same path.
Credit 16 minute read
Credit from zero: how to start your history in the U.S.
What credit reports and scores are, how to get them for free, and how to start a history from nothing with a secured card or a credit-builder loan.
- Your report is free once a week from each bureau, and requesting it does not lower your score.
- Paying on time, every time, is the number one factor in most scores; using little of your limit counts too.
- To start with no history: a secured card, a credit-builder loan or a store card with a low limit, as long as they report to the three bureaus.
- Credit How to read your credit report, line by line Where to get your free credit reports, what each part says, how long negative items can stay and how to spot errors or identity theft. 13 minute read
- Credit How to dispute errors on your credit report How to fix credit report errors for free: what to send each bureau and the company that reported it, legal deadlines, and credit repair scams. 14 minute read
- Credit AnnualCreditReport.com step by step: your free reports How to get your free credit reports online, by phone or by mail, what information they ask for, what to check and how to freeze your credit. 15 minute read
Tools for this topic
Was this guide useful?
Thank you. Your answer stays in your browser; nothing is sent.