Credit unions vs. banks: how they differ
Credit unions and banks: who can join, NCUA and FDIC insurance, fees and overdrafts, accounts with an ITIN, small-dollar loans and CDFIs.
Verified against official sources on October 17, 2026 16 official sources
Show contents
In short
What you need to know
Quick answer
Both keep your money safe, lend and offer similar services. A credit union is not-for-profit and owned by its members: to join you need a common bond, such as your job, your family, where you live or a group. Your money is federally insured to at least $250,000 per person and account category, by the FDIC at insured banks and by the NCUA at insured credit unions; check it before you open an account. Both must give you fee disclosures before you open the account and cannot charge you overdraft fees on debit or ATM transactions unless you opted in.
What matters most
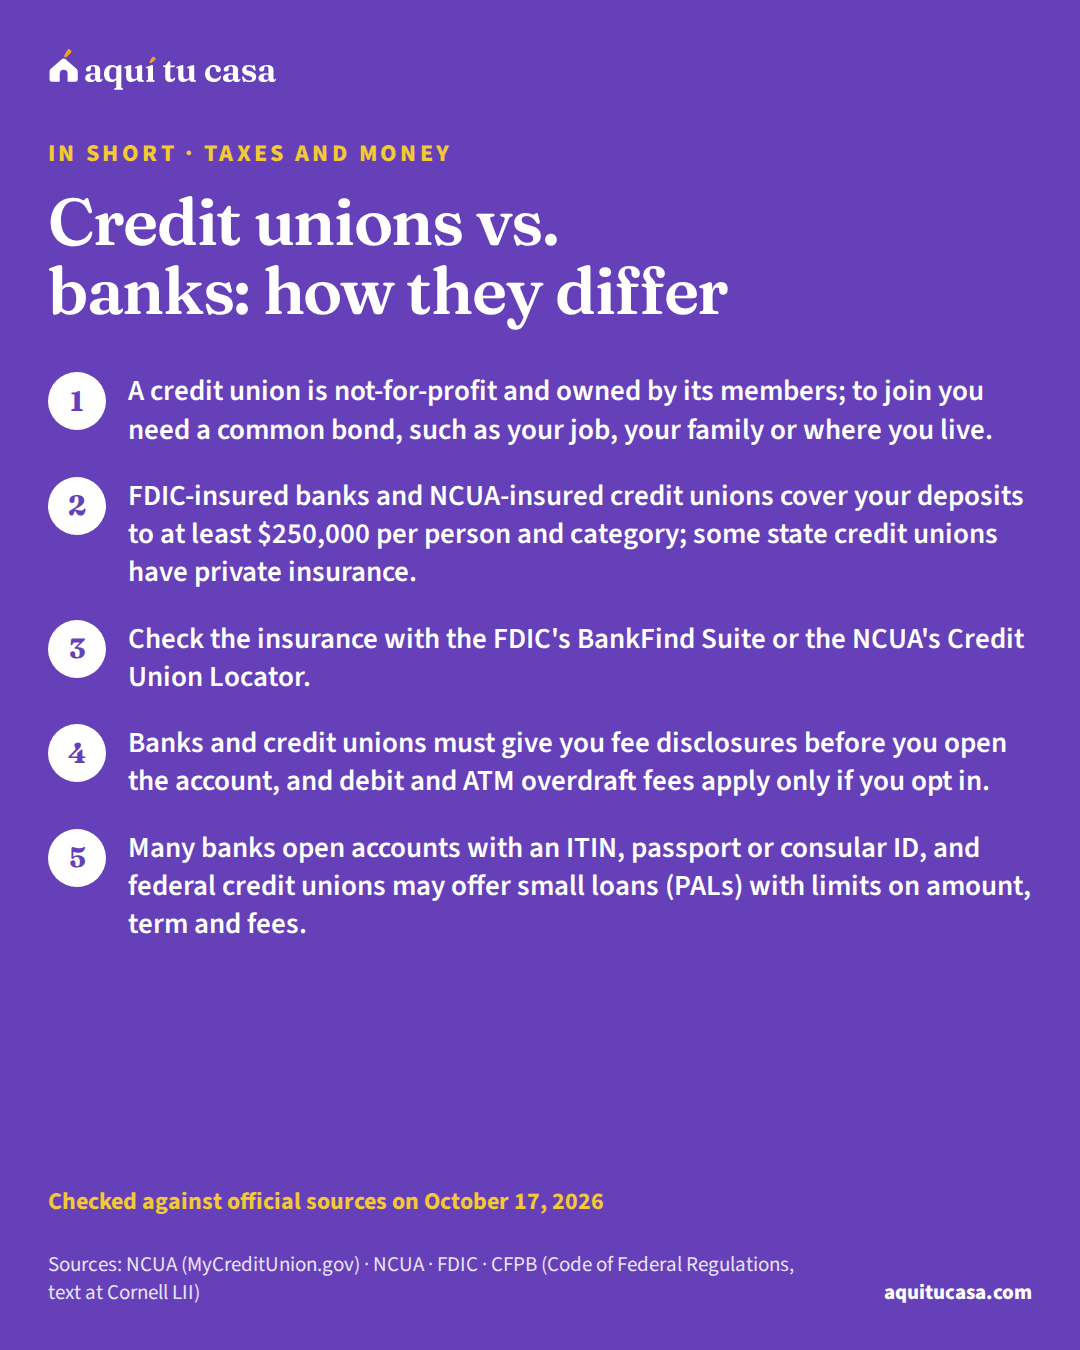
- A credit union is not-for-profit and owned by its members; to join you need a common bond, such as your job, your family or where you live.
- FDIC-insured banks and NCUA-insured credit unions cover your deposits to at least $250,000 per person and category; some state credit unions have private insurance.
- Check the insurance with the FDIC's BankFind Suite or the NCUA's Credit Union Locator.
- Banks and credit unions must give you fee disclosures before you open the account, and debit and ATM overdraft fees apply only if you opt in.
Is this for you?
This guide is for you if…
- You want to open your first account and are not sure whether to choose a credit union or a bank.
- You have an ITIN, a passport or a matricula consular and want to know which documents you may be asked for.
- You want to know whether your money is insured and how to check.
Get direct help first if…
- You want a certified low-cost account: the Bank On accounts guide explains which standards they meet.
- You were denied an account because of your banking history: the guide to opening an account without a Social Security number explains what to do.
- You want to invest in stocks or funds: FDIC and NCUA insurance does not cover investments.
This guide is for you if you want to open an account, or switch, and are not sure whether to choose a credit union or a bank. You will see how they are alike and how they differ, who can join a credit union, how federal insurance protects your money and how to check it, which rules protect you on fees, which documents you may be asked for if you have an ITIN or a passport, and what PAL loans and CDFIs are. We do not recommend any institution: we report what official sources say.
- Minimum federal insurance per depositor and ownership category at each FDIC-insured bank
- $250,0004
- At an NCUA-insured credit union, each member has at least the same coverage.2
- What you may be able to open a bank account with, according to the FDIC
- $2510
- The amount of a PAL I loan at a federal credit union
- $200 to $1,00013
- When you can be charged overdraft fees on debit purchases or at ATMs
- Only if you opt in7
What a credit union is and how it compares to a bank
According to the NCUA (the National Credit Union Administration), a credit unioncredit unionA credit union is a not-for-profit financial institution that, like a bank, accepts deposits, makes loans and offers other services, but is owned by its members. Members elect a volunteer board of directors, and profits go back to them as lower fees, higher savings rates and lower loan rates. To join you need a common bond, such as your employer, your family, where you live or a group you belong to. It is chartered by the NCUA, a federal agency, or by a state. If the credit union is federally insured, your deposits are protected by the NCUA's insurance fund.See the full definition is a not-for-profit financial institution that accepts deposits, makes loans and offers other financial services, just like a bank. The difference is ownership: a credit union belongs to its members, who control it, and a volunteer board they elect runs it.1
Its profits go back to members as lower fees, higher savings rates and cheaper loans. Unlike banks, it returns surplus income to members as dividends. The NCUA says that, on average, credit unions offer higher savings rates and lower loan rates, and tend to charge lower fees and require lower balances.1 Those are averages: compare the fee disclosures of each one.6
Credit union and bank, side by side
Owned by its members
Credit union
Both must give you fee disclosures before you open the account6 and neither can charge you debit or ATM overdraft fees without your consent.7
Who can join a credit union
To join a credit union you need to share its common bond, called its field of membership. According to the NCUA, you may be able to join:1
- Through your job: many employers sponsor their own credit union.
- Through your family: most credit unions let members’ families join.
- Through where you live: many serve anyone who lives, works, worships or attends school in a certain area.
- Through a group: belonging to a place of worship, a school or a labor union may qualify you.
Ask the credit union about its field of membership before you bring your papers. If your partner, parents or siblings are already members, mention it.1
Your money, insured: FDIC and NCUA
At an FDIC-insured bank (the Federal Deposit Insurance Corporation), your deposits are insured to at least $250,000 per depositor, per ownership category, at each bank. The fund is backed by the full faith and credit of the U.S. government. It covers only deposits and only if your bank is FDIC-insured; it does not cover investments, even if the bank sells them to you.4
At a federally insured credit union, insurance is automatic when you join, and each member has at least $250,000 in total coverage for their accounts. It is also backed by the U.S. government.2 The NCUA says no one has lost a single penny of insured deposits at a federally insured credit union.3
How to check. For a bank, the FDIC asks you to look it up in its BankFind Suite tool.4 For a credit union, use the NCUA’s Credit Union Locator. Insured credit unions must display the official NCUA sign at their teller stations and on their website, and they cannot drop federal insurance without notifying members. A federal credit union’s official name includes the words “federal credit union.”2
What is not covered. Neither the FDIC nor the NCUA covers investments such as stocks, bonds or mutual funds, or life insurance and annuities, even if your bank or credit union sells them.42 The NCUA does not insure cryptocurrencies either.3 If you have more money than the limit, the FDIC’s EDIE calculator estimates how much is covered.4

Fees, overdrafts and the disclosures you must receive
Before opening an account, ask for the disclosures. The law requires banks and credit unions to give them to you before you open an account or receive a service, and they must state each fee that may be charged, or how it is calculated, and when it applies.56 At credit unions these are called Truth in Savings disclosures, and they list fees for dormant accounts, returned checks or insufficient funds. Some institutions lower fees if you bank online.9
Overdrafts. Under Regulation E, the institution holding your account may not charge you for covering an ATM withdrawal or a one-time debit card purchase through its overdraft service unless it explains the service in writing, gives you the chance to accept it, you opt in and it confirms your choice in writing. You can revoke your consent.7 The rule applies to banks and credit unions alike: under Regulation E, a financial institution includes banks and credit unions.8 That is why, when you open a checking account, a credit union will ask whether you want its overdraft program; if you say yes, it will charge the fee on its schedule.9
Example with real numbers
How to compare two accounts using their disclosures
An example in words; fill in each row with what each institution's disclosure says.
- Monthly fee
- How much it is and what conditions waive it
- Minimum balance
- How much you have to keep in the account
- Overdraft and insufficient funds
- What they charge and whether you opted in for debit and ATM
- Other fees
- Dormant accounts, returned checks and other services you would use
- What you would pay in a year
- Add up the fees you would actually use, for each institution
Banks and credit unions must give you these disclosures before you open the account.56 Debit and ATM overdraft fees apply only if you opted in.7 What you save on fees can go into your savings plan.
Run it with your numbersDown payment savings planOpening an account with an ITIN, passport or matricula
According to the FDIC, to open an account you bring your Social Security number or ITIN and an ID such as a driver’s license, a state or military ID, or a passport; some banks accept other IDs. Many banks let you open an account even if you are not a citizen, with a foreign passport, a consular ID or an ITINITIN (Individual Taxpayer Identification Number)An ITIN is a nine-digit number the IRS, the federal tax agency, issues to people who need a U.S. taxpayer identification number to file taxes and are not eligible for a Social Security number. It is for tax purposes only: it does not authorize you to work in the United States, does not qualify you for Social Security benefits or the Earned Income Tax Credit, and says nothing about your immigration status. You apply with Form W-7, and it expires if it goes unused for several years. Some lenders accept an ITIN for a mortgage.See the full definition. And you may be able to open one with as little as $25.10
The federal customer identification rule for banks says that, for a non-U.S. person, the identification number can be a taxpayer identification number, a passport number and country, an alien ID card number or the number of another government document showing nationality or residence and bearing a photo.11 Some banks accept other IDs, so ask before you go.10
In a legal opinion, the NCUA said it saw no legal impediment to a federal credit union lending to members who use an ITIN and a matricula consularconsular ID cardA Matricula Consular is an official Mexican government ID document issued by Mexico's consulates in the United States. Other countries offer similar IDs, sometimes called consular identification (CID) cards. According to the CFPB, many banks require a U.S. or state government-issued photo ID; if you do not have one, some banks and credit unions accept foreign passports and consular IDs such as the Matricula, but not all, and the CFPB suggests asking first. You usually also need another document, such as a bill with your name and address, and an interest-bearing account requires an SSN or ITIN.See the full definition instead of a Social Security number, although the credit union must address the risks. It also said it knew of no law that prohibits a creditor from reporting borrower data to credit reporting agencies by a number other than the Social Security number. The question involved a plan to help members without a Social Security number establish a credit historycredit historyYour credit history is the record of your credit accounts and of whether you paid them on time, as shown in your credit report. Credit reporting companies collect and update this information and provide it to other businesses, which use it to make decisions about you. A good history helps you get housing, bank accounts, cards and loans, and lowers the interest you pay. If you have no history, or very little (a thin file), there may not be enough information to produce a score. Paying with a debit card, cash or a prepaid card usually does not build it.See the full definition.12
The guide to opening a bank account without a Social Security number explains what to do if you are denied an account, and the Bank On low-fee accounts guide shows low-cost accounts. If you send money to family abroad, the remittance tax guide explains how it applies depending on how you pay.
Small-dollar loans and CDFIs
PAL loans. Federal credit unions may offer paydaypayday loanA payday loan is, according to the CFPB, a small, short-term, high-cost loan that is usually due on your next payday. To collect, the lender usually asks for a post-dated check or permission to take the money from your account. It generally does not check whether you can repay it and still cover your other bills. Its fees, expressed as an annual percentage rate (APR), can be much higher than a credit card's. Some states do not allow payday loans or cap them, and in others you may be offered a rollover in which you pay only the fees.See the full definition alternative loans. For PAL I, the NCUA’s rule sets conditions including: $200 to $1,000; a term of one to six months; no more than three in six months to the same person and one at a time; no rollovers; fully repaid in installments; membership for at least one month first; and an application fee that reflects actual costs and never exceeds $20.13 Not every credit union offers them: ask yours.
CDFIs. A CDFICommunity Development Financial Institution (CDFI)A CDFI (Community Development Financial Institution) is an organization whose primary mission is community development. It provides loans, investments and other financial services in low-income communities and to people who lack access to financing. It can be a community development bank or credit union, or a loan fund that is not a bank. The law requires that it not be a government agency, that it be accountable to the community it serves and that it offer services such as financial and credit counseling along with its loans. The Treasury Department's CDFI Fund certifies them.See the full definition (Community Development Financial Institution) is an organization certified by the Treasury’s CDFI Fund that provides financial services in low-income communities and to people who lack access to financing. It can be a community development bank or credit union, or a loan fund. There are certified CDFIs in all 50 states, the District of Columbia, Guam and Puerto Rico, and the Fund publishes the list. Its awards finance, among other things, mortgage lending for first-time homebuyers.14 The ITIN mortgages guide explains what to ask if you plan to buy a home.

If this is you
You have an ITIN or your home country's passport
Many banks open accounts with a foreign passport, consular ID or ITIN; ask which ones they accept.10
You have no credit history
The NCUA saw no impediment to a federal credit union lending with an ITIN and reporting your payments under that number.12
Someone in your family is already a member
Most credit unions let members' families join.1
If you have a problem with your bank or credit union
First try to resolve it directly with the institution. For a credit union, the NCUA recommends exactly that; if it is not resolved, its Consumer Assistance Center (CAC) helps resolve disputes with credit unions, and when it can help, it asks the credit union to try to resolve the complaint within 60 calendar days.15 For questions about deposit insurance at a bank, the FDIC answers at 877-275-3342.4
If you want to get your accounts, credit or budget in order before buying a home, a HUD-approved housing counselorHUD-approved housing counselorA HUD-approved housing counselor works at an agency HUD has approved to provide housing counseling: independent, expert advice customized to your situation about buying a home, renting, a missed mortgage payment, a foreclosure or credit problems. The agencies usually charge little or nothing; many serve in Spanish and offer the homebuyer education course several assistance programs require. They are not lenders or real estate agents and sell you nothing. Your county page lists the official agencies with phone numbers.See the full definition gives independent advice, often for free or at low cost.16
Mistakes that cost you money
Mistake: Assuming every credit union is federally insured.
Instead: Look it up in the NCUA's Credit Union Locator: some state credit unions have private insurance.32
Mistake: Thinking insurance covers investments or cryptocurrency.
Instead: It covers only deposits; investments are not insured even if your bank or credit union sells them.43
Mistake: Opting in to overdraft without reading what it costs.
Instead: Debit and ATM overdraft fees apply only if you opt in, and you can revoke your consent.7
Mistake: Opening the account without asking for the fee disclosures.
Instead: Ask first: banks and credit unions must give them to you.56
Mistake: Taking a payday loan without asking your credit union.
Instead: Ask whether your federal credit union offers PAL loans, with limits on amount, term and fees.13
What to do this week
- Write down where you live, work, study or worship, and any family members who already belong to a credit union.1
- Look up each institution you are considering in the FDIC’s BankFind Suite or the NCUA’s Credit Union Locator.43
- Ask for the fee disclosures for two accounts and compare them line by line.56
- Ask which IDs they accept if you have an ITIN, a passport or a matricula consular.10
- Decide whether you want the overdraft service for debit and ATM transactions.7
- Use the savings plan to set a monthly goal for your new account.
Your numbers
We start with the typical home value in the United States ($332,700). Enter the price you are looking at.
Adjust advanced details
The minimum for this loan is 3.5%. A larger down payment lowers the monthly payment but takes longer to save.
As a share of the price. It is an example; your lender's Loan Estimate has the real figure.
Annual interest of the account where you keep the money. Leave it at zero if you do not know.
Let's do the math
Time to reach your goal
Enter how much you can save each month.
Your goal
- Down payment (3.5% of the price)
- $11,645
- Closing costs (3% of the price)
- $9,981
- Savings target
- $21,626
- You already have
- $0
- Still missing
- $21,626
What helps
- Set up an automatic transfer on payday into a separate account you do not use for spending.
- Ask about your state's and city's assistance programs before setting the goal: many cover part of the down payment or closing costs.
- If family gives you part of it, the lender usually asks for a gift letter and the transfer record; ask beforehand how they want it.
- Revisit the goal whenever the price you are looking at, the loan type or what you can save changes.
An educational estimate, not a loan offer. Closing costs are an example (3% of the price); the real figure comes in the Loan Estimate. We do not count the reserves some lenders require after closing.
Ready to see the numbers? Find your county here
See how this applies in your county: its loan limits, prices and rents, from the official data.
Printable checklist
Frequently asked questions
Is a credit union or a bank safer?
If the bank is FDIC-insured or the credit union NCUA-insured, your deposits are covered to at least $250,000 per person and account category, backed by the U.S. government. Watch out: some state-chartered credit unions have private insurance, which does not have that backing.
How do I know whether my credit union or bank is federally insured?
For a bank, look it up in the FDIC's BankFind Suite. For a credit union, use the NCUA's Credit Union Locator. Insured credit unions must also display the official NCUA sign at their teller stations and on their website.
Who can join a credit union?
People who share its common bond: many accept anyone who lives, works, worships or attends school in an area; others serve an employer or a group, such as a school or labor union; and most let members' families join.
Can I open an account with an ITIN or my home country's passport?
According to the FDIC, many banks let you open an account even if you are not a citizen, with a foreign passport, a consular ID or an ITIN. The federal customer identification rule allows, for non-U.S. persons, a taxpayer identification number, a passport number or another government document with a photo.
Can they charge me an overdraft fee when I pay with my debit card?
Under Regulation E, a bank or credit union may not charge you for covering an ATM withdrawal or a one-time debit card purchase through its overdraft service unless you opted in to that service. You can revoke your consent.
What is a PAL loan?
It is a payday alternative loan a federal credit union may offer. For PAL I, the rule sets conditions including: $200 to $1,000, one to six months, no rollovers, membership for at least one month first and an application fee that never exceeds $20.
What is a CDFI?
It is a Community Development Financial Institution certified by the Treasury's CDFI Fund: it provides financial services in low-income communities and to people who lack access to financing. It can be a bank, a credit union or a loan fund, and there are CDFIs in every state and in Puerto Rico.
Sources
Every figure in this guide comes from one of these official sources. The number next to a sentence leads to the source behind it.
Each source on one line: who publishes it, its title, its address and the date we read it.
- 1. NCUA (MyCreditUnion.gov) · What is a Credit Union? · mycreditunion.gov · Accessed October 17, 2026
- 2. NCUA (MyCreditUnion.gov) · Share Insurance · mycreditunion.gov · Accessed October 17, 2026
- 3. NCUA · Share Insurance Coverage · ncua.gov · Accessed October 17, 2026
- 4. FDIC · Understanding Deposit Insurance · fdic.gov · Accessed October 17, 2026
- 5. CFPB (Code of Federal Regulations, text at Cornell LII) · Regulation DD, 12 CFR §1030.4, Account disclosures · law.cornell.edu · Accessed October 17, 2026
- 6. NCUA (Code of Federal Regulations, text at Cornell LII) · 12 CFR §707.4, Account disclosures (Truth in Savings for credit unions) · law.cornell.edu · Accessed October 17, 2026
- 7. CFPB (Code of Federal Regulations, text at Cornell LII) · Regulation E, 12 CFR §1005.17, Requirements for overdraft services · law.cornell.edu · Accessed October 17, 2026
- 8. CFPB (Code of Federal Regulations, text at Cornell LII) · Regulation E, 12 CFR §1005.2, Definitions · law.cornell.edu · Accessed October 17, 2026
See the other 8 sources
- 9. NCUA (MyCreditUnion.gov) · Credit Union Accounts & Services · mycreditunion.gov · Accessed October 17, 2026
- 10. FDIC · GetBanked · fdic.gov · Accessed October 17, 2026
- 11. FinCEN, U.S. Department of the Treasury (Code of Federal Regulations, text at Cornell LII) · 31 CFR §1020.220, Customer identification program requirements for banks · law.cornell.edu · Accessed October 17, 2026
- 12. NCUA · Individual Taxpayer Identification and Matricula Consular Numbers for Credit Reporting Purposes (legal opinion) · ncua.gov · Accessed October 17, 2026
- 13. NCUA (Code of Federal Regulations, text at Cornell LII) · 12 CFR §701.21, Loans to members and lines of credit to members · law.cornell.edu · Accessed October 17, 2026
- 14. CDFI Fund, U.S. Department of the Treasury · CDFI Certification · cdfifund.gov · Accessed October 17, 2026
- 15. NCUA (MyCreditUnion.gov) · Complaint Process · mycreditunion.gov · Accessed October 17, 2026
- 16. CFPB · Find a Housing Counselor · consumerfinance.gov · Accessed October 17, 2026
Keep reading
Related guides
If this guide helped, these follow the same path.
ITIN 11 minute read
How to open a bank account without a Social Security number
What banks and credit unions ask for to open an account without a Social Security number (ITIN, passport or consular ID) and which account to pick.
- Federal law allows opening an account with an ITIN, a passport, an alien identification card or another government document; the bank chooses which it accepts.
- Bring a photo ID, a second proof (a bill or birth certificate), your ITIN if you have one and the opening deposit, usually between $25 and $100.
- Without a Social Security number or an ITIN you may only be able to open a no-interest account; with an ITIN, you sign the W-9 with that number.
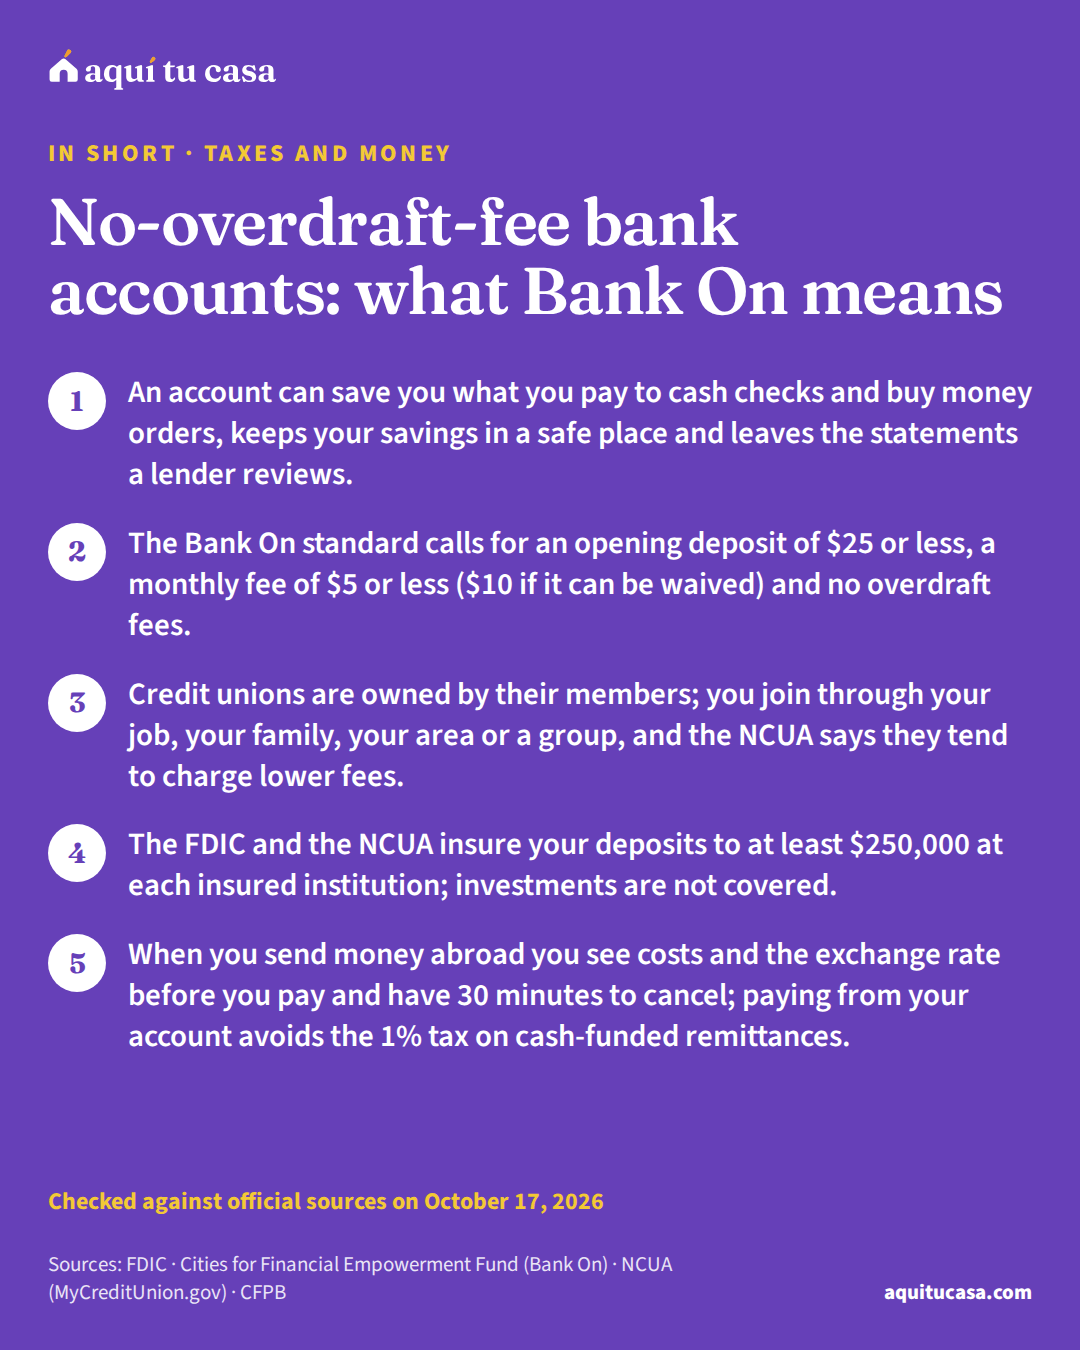
- Taxes and money No-overdraft-fee bank accounts: what Bank On means What a Bank On certified account is, why an account helps you save and buy a home, credit unions, FDIC/NCUA insurance, check cashing and remittances. 13 minute read
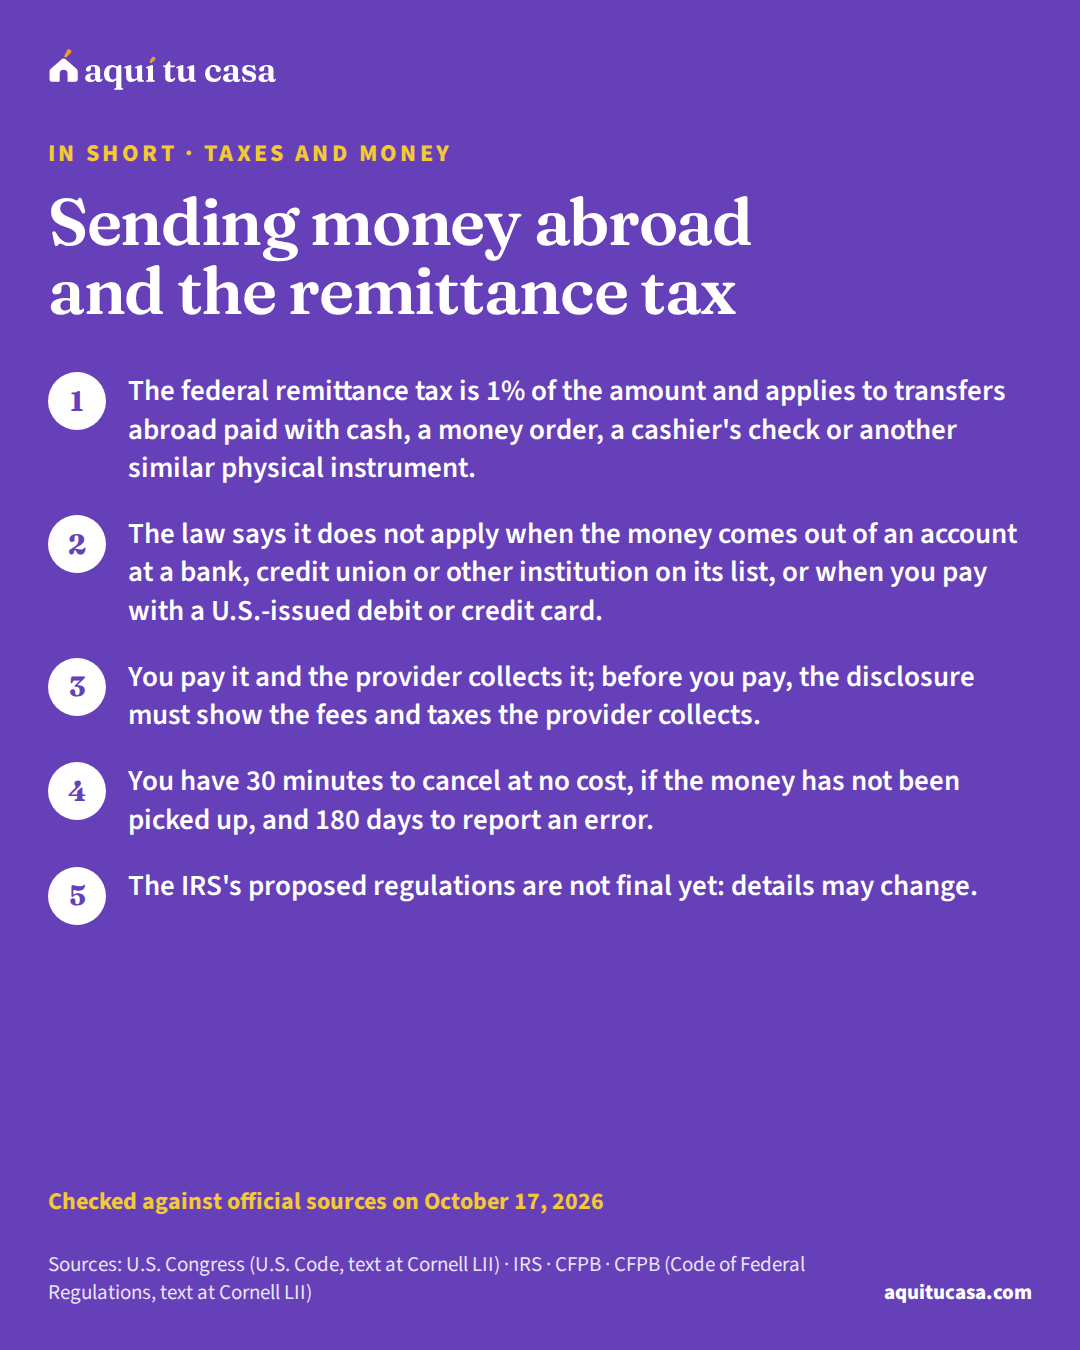
- Taxes and money Sending money abroad and the remittance tax The federal tax on cash-funded remittances: which transfers it applies to, which it does not, who collects it and your rights when you send money abroad. 10 minute read
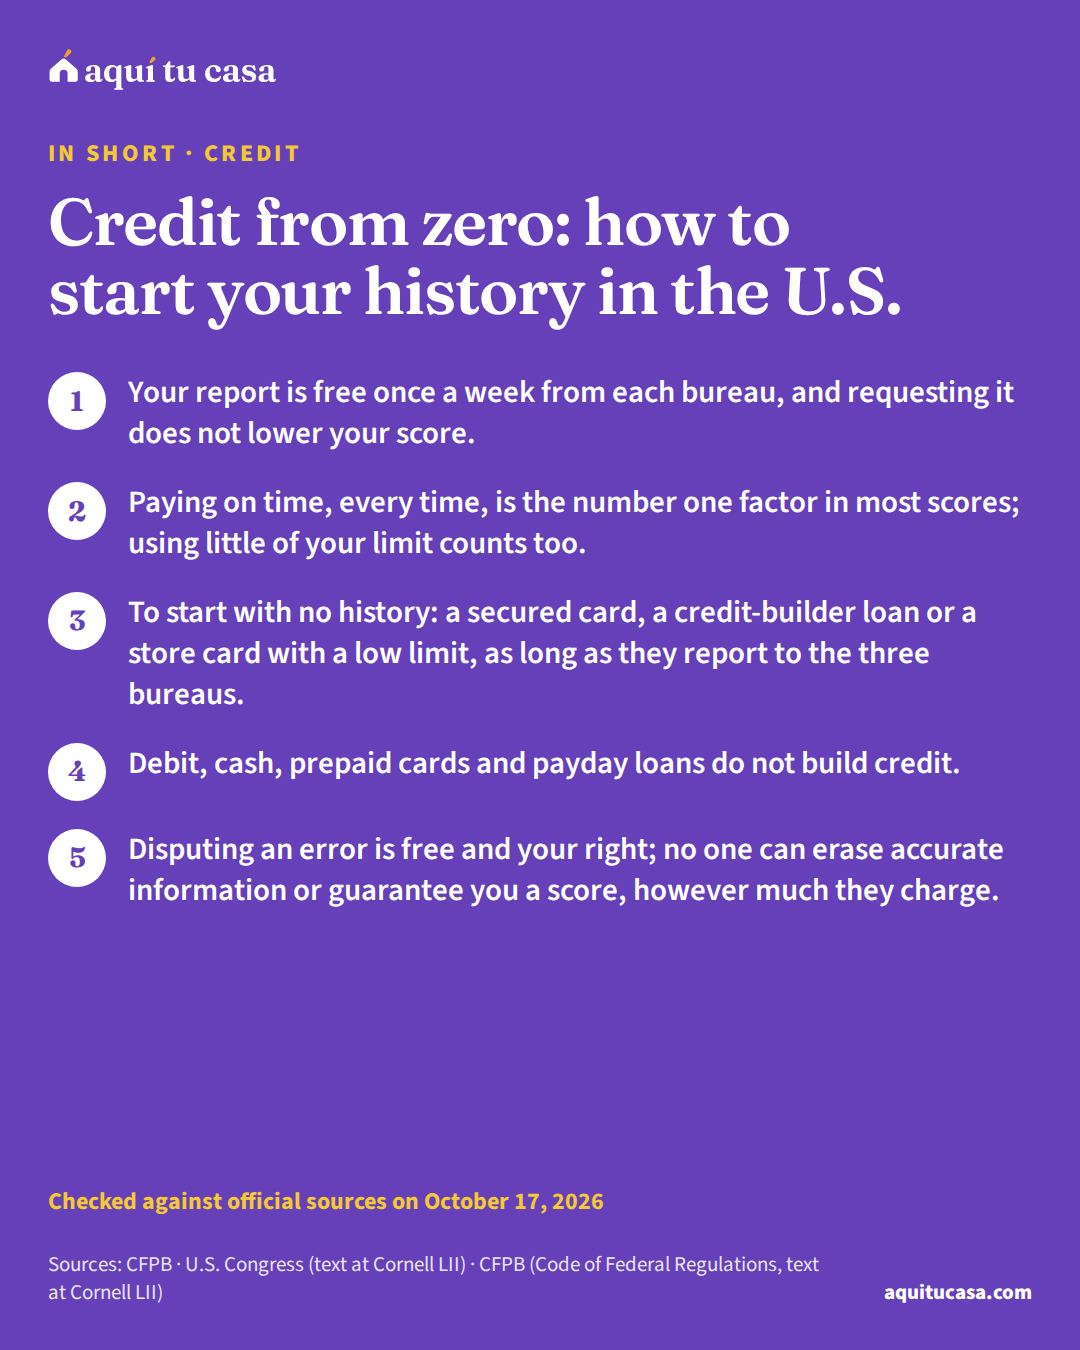
- Credit Credit from zero: how to start your history in the U.S. What credit reports and scores are, how to get them for free, and how to start a history from nothing with a secured card or a credit-builder loan. 16 minute read
Tools for this topic
Was this guide useful?
Thank you. Your answer stays in your browser; nothing is sent.