Car title loans and pawn loans: what you can lose
How car title loans and pawn loans work, what the CFPB found, what you can lose and which cheaper alternatives exist before you hand over your car title.
Verified against official sources on October 31, 2026 9 official sources
Show contents
In short
What you need to know
Quick answer
With a title loan you hand over your car title in exchange for cash for 15 or 30 days. The FTC says they often charge fees of up to 25% a month, an APR of about 300%, and that you can lose the car even after partial payments; the CFPB found that one in five single-payment borrowers has the vehicle seized. With a pawn loan, the shop keeps your item and can sell it if you do not repay as agreed. Before you sign, look at alternatives such as a PAL loan from a federal credit union.
What matters most
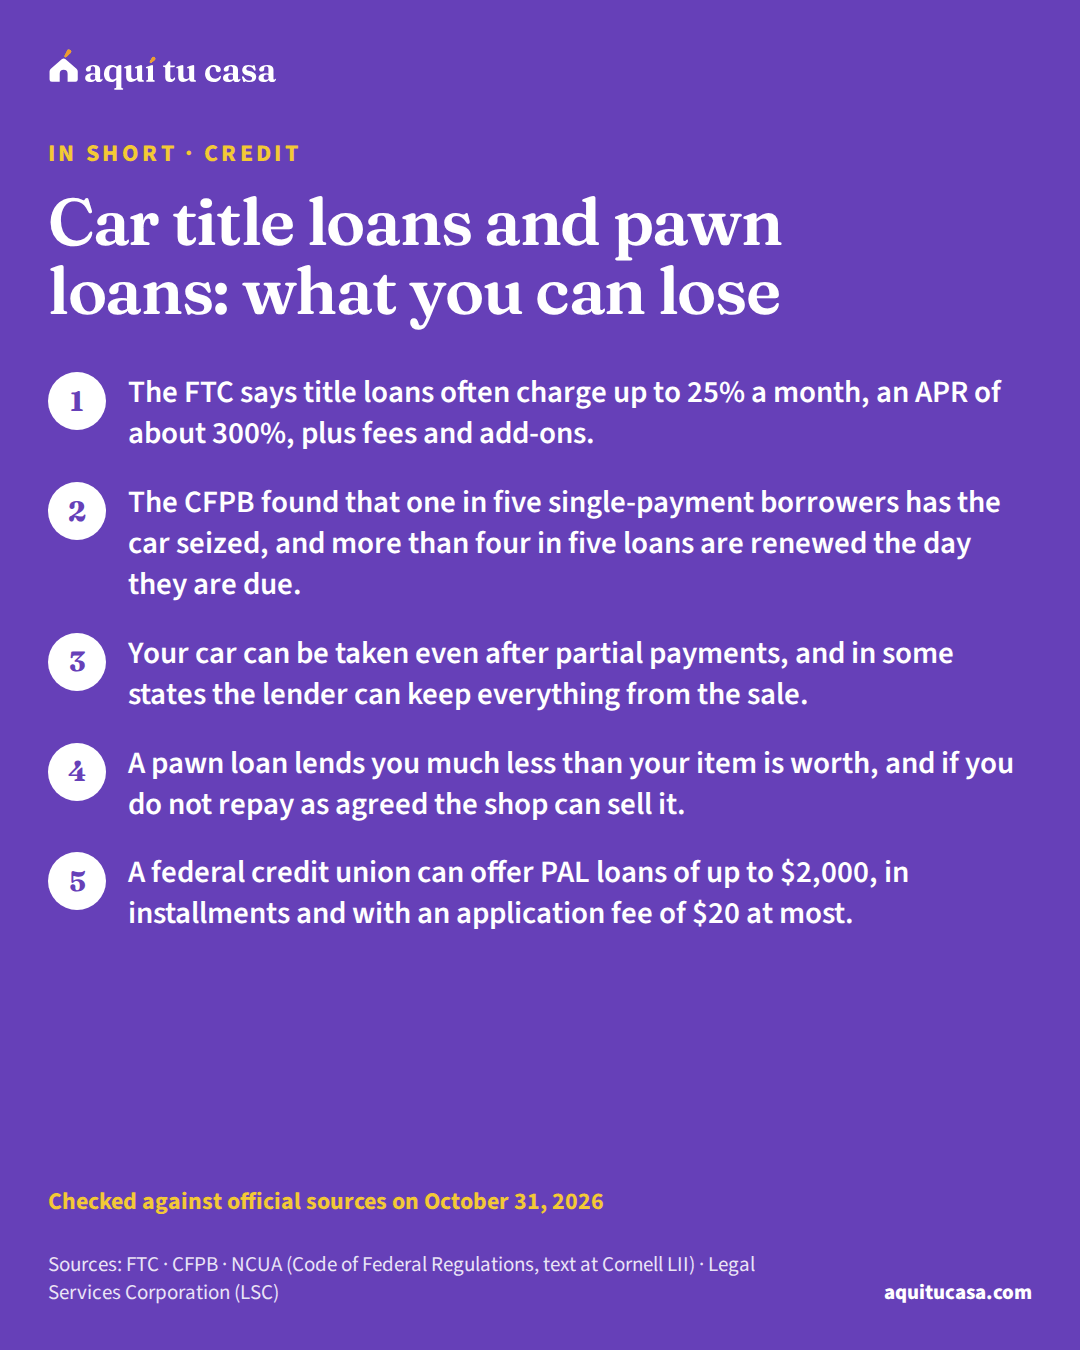
- The FTC says title loans often charge up to 25% a month, an APR of about 300%, plus fees and add-ons.
- The CFPB found that one in five single-payment borrowers has the car seized, and more than four in five loans are renewed the day they are due.
- Your car can be taken even after partial payments, and in some states the lender can keep everything from the sale.
- A pawn loan lends you much less than your item is worth, and if you do not repay as agreed the shop can sell it.
Is this for you?
This guide is for you if…
- You were offered quick cash in exchange for your car title or for a piece of jewelry or an appliance.
- You already have a title loan and fear losing the car you need to get to work.
- You want to compare these loans with other options before deciding.
Get direct help first if…
- Your car has already been taken and you want it back or want to challenge the sale: read the repossession section and look for free legal aid today; the laws vary by state.
- You are on active military duty: the Military Lending Act protects you; your legal assistance (JAG) office can help.
When money runs short, your car or a piece of jewelry can look like the fastest way to get some. This guide is for you if you were offered a loan against your car title or are thinking of pawning something: it explains how these loans work, what the CFPB and the FTC found, what you can lose, what rights you have if your car is taken and which cheaper alternatives exist.
How a car title loan works
According to the FTC, a title loan is a short-term loan, typically 15 or 30 days, that uses your car, truck, motorcycle or other vehicle as collateral. It is usually for 25% to 50% of the vehicle’s value. To get one, you give the lender your vehicle title, and you usually need to own the vehicle free and clear, though some lenders take the title if you have paid off most of your car loan. The lender wants to see the vehicle, a photo ID and proof of insurance, and many want a duplicate set of keys. You do not get the title back until you repay what you borrowed, plus the finance charge and other fees.1
The CFPB’s tool for choosing financial products sums it up the same way: you borrow money for a short time and give up your car title until you repay. Some are repaid in installments and others all at once, and if you cannot pay, the lender can repossess your car and sell it.3
Until you pay in full, the title, which is the paper that proves the car is yours, stays with the lender.1
What it costs
The FTC says these loans are expensive. They often have monthly finance fees of up to 25%, which translates to an APRannual percentage rate (APR)The annual percentage rate (APR) is a broader measure of the cost of borrowing money than the interest rate. Besides the interest, it includes certain loan charges, such as discount points and some lender fees, spread over the life of the loan and expressed as a yearly percentage. That is why the APR is almost always a little higher than the interest rate. It is useful for comparing offers: if two loans have the same interest rate but a different APR, the one with the higher APR charges more in fees.See the full definition of about 300%. Lenders often add other charges, such as processing, document and origination fees, and you may have to buy add-ons, such as a roadside service plan.1
Example with real numbers
The FTC's example
A $1,000 loan for 30 days with a 25% finance fee.
- What you borrow
- $1,000
- The finance fee
- $250
- What you owe at 30 days
- $1,250, plus other fees
- If you roll it over another 30 days
- $1,500, plus rollover fees
- What it costs to borrow $1,000 for 60 days
- At least $500
That is the FTC's math.1 Try the family budget to see what you could pay each month.
Run it with your numbersFamily budgetThe CFPB studied nearly 3.5 million single-payment title loans. It found the typical loan is about $700 with a typical APR of about 300%, and that more than four in five are renewed the day they are due, because borrowers cannot repay them all at once. Only in about 12% of cases is everything repaid in one payment without quickly borrowing again. In more than half of cases borrowers take out four or more loans in a row, and more than two-thirds of the business comes from people who take out seven or more.2
What you can lose: your car
The FTC is clear: you could lose your vehicle. If you cannot repay, the lender may repossess it even if you have been making partial payments. Some require installing a GPS and a starter interrupt device, to find the vehicle and disable the ignition remotely. Once they repossess it, they can sell it, and in some states the lender can keep all the money from the sale, even if it is more than you owe.1
The CFPB found that one in five single-payment title loan borrowers has their car or truck seized for failing to repay. And it warns that losing the vehicle can cost people their way to get to work or the doctor.2
Title loan, pawn loan and a PAL
The lender keeps your title
Title loan
The shop keeps your item
Pawn loan
Before handing over your car title, ask a federal credit union about a PAL.1
Pawn shops
With a pawn loan, according to the CFPB, you are paid cash in exchange for an item the pawn shop keeps during the loan, such as jewelry or electronics. The loan is often much less than the item’s actual value, and if you do not repay as agreed, the shop can sell the item to cover the debt.3
A CFPB research brief explains that payday, title and pawn loans are called alternative financial services because the typical lender is not a bank. They are generally for less than $1,000, with high rates and terms of a month or less, and pawn loans usually use a valuable item, such as a computer or jewelry, as collateral. In the CFPB’s survey, 73% of people who had taken out a pawn loan in the previous six months still owed money, and 83% for title loans: many people roll them over or borrow again.4
Watch for the fees you do not see. In a lawsuit against a pawnbroker, the CFPB explained that every fee on the loan, whatever it is called, is a finance charge that must be included in calculating the APR. In its example, a $200 loan due in a month with a $10 finance charge, a $10 storage fee and a $20 processing fee totals $40 and yields an APR of 240%, although the shop showed only 120%. The CFPB noted that its complaint is not a finding that the law was violated. And in another action against pawnbrokers it said those fees are called, for instance, “appraisal,” “interest,” “storage” or “setup” charges.5 Add them all up before you sign.

If your car is taken
The CFPB explains the rights that commonly exist when a lender repossesses a car. Many depend on your state’s law:6
- Notice. In many states, the lender can repossess the car without warning or a court order after a missed payment; other states require notice first.
- No “breaching the peace.” Under some state laws, it cannot take the car with threats or physical force, by removing it from a closed garage without permission or by continuing after you refused.
- Your belongings. If you left things in the car, contact the lender right away to get them, and write down what was there and what it is worth.
- Catching up. In some states you have the right to pay what is overdue plus costs to get the car back.
- Before the sale. You have the right to be notified before it is sold; for a public sale, of the date, time and place. You may be able to buy it back by paying the full loan plus costs before the sale.
- After the sale. The lender must sell it in a commercially reasonable manner. If it sells for less than you owe, you may owe the difference; if it sells for more, you may be entitled to the surplus.
Be careful with that last point on a title loan: the FTC warns that in some states the lender can keep all the money from the sale, even if it is more than you owe.1 That is why your state’s law matters so much. The CFPB suggests asking your state attorney general or consumer protection office, or your local legal services office.6 You find free legal aid by address on the Legal Services Corporation website.9
If a debt remains after the sale and it goes to a collection agency, the guide on debt collection explains your rights.
Cheaper alternatives
The FTC lists options that are less expensive and less risky than title loans:1
- Ask your creditors for more time, and ask whether they will charge you for the extension.
- A credit union. Credit unionscredit unionA credit union is a not-for-profit financial institution that, like a bank, accepts deposits, makes loans and offers other services, but is owned by its members. Members elect a volunteer board of directors, and profits go back to them as lower fees, higher savings rates and lower loan rates. To join you need a common bond, such as your employer, your family, where you live or a group you belong to. It is chartered by the NCUA, a federal agency, or by a state. If the credit union is federally insured, your deposits are protected by the NCUA's insurance fund.See the full definition typically have lower rates, and some federal credit unions offer a payday alternative loanpayday alternative loan (PAL)A payday alternative loan (PAL) is a small loan that federal credit unions can offer their members instead of a payday loan, which costs much more. According to the NCUA, the federal rule limits the amount and the term, which is short; the application fee may only cover the real cost of processing it, and there is a cap on how many you can have in a period. It is paid off in full in installments and cannot be rolled over. For one type of PAL, you must be a member for some time before applying. Some lenders that are not credit unions use the name, so read the fine print.See the full definition (PAL), which is much less expensive. Some state-chartered credit unions have similar loans.
- A local bank, which can offer smaller loans with easier repayment, or a large bank that offers small loans to customers with low or no credit scores.
- Your tax refund, if you expect one: file as soon as you can.
- Credit counseling, free or low cost, from a nonprofit group, your employer, your credit union or your housing authority.
- Family, friends, charities and places of worship, which often help at no cost.
Under NCUA rules, a federal credit union PAL runs from $200 to $1,000 for one to six months (PAL I) or up to $2,000 for one to 12 months (PAL II), is never rolled over, is repaid in full in installments and carries an application fee that never exceeds $20.7 The guide on payday loans and their alternatives explains all the rules, and the one on credit unions vs. banks explains how to join.
If you are on active military duty or a dependent of someone who is, the Military Lending Act covers vehicle title loans: you cannot be charged more than a 36% Military Annual Percentage Rate (MAPR), which includes fees and add-ons, or be required to accept mandatory arbitration, and your legal assistance (JAG) office can help.8
Before you hand over your car title
1. Write down how much you need and by when
Today
Ask your creditor first whether it will give you more time.1
Try it with your numbersFamily budget2. Ask a federal credit union about a PAL
This week
From $200 up to $2,000, in installments, with an application fee of $20 at most.7
3. If you still consider it, get every fee in writing
Before you sign
The APR, processing fees and add-ons such as roadside service.1
4. Ask what happens if you do not pay on time
Before you sign
Whether they can take the car and what happens to the sale money in your state.1
5. Keep copies of everything
The day you sign
If the car is ever taken, you have rights that depend on your state.6
If this is your situation
You need the car to work
The CFPB warns that losing the vehicle can cost you your way to work or the doctor;2 look first for an alternative that does not use your title.1
You have no credit history
Some large banks offer small loans to customers with low or no credit scores.1
You are on active military duty
The Military Lending Act caps title loans at a 36% MAPR.8
You are going to pawn a family piece of jewelry
They will lend you much less than it is worth, and if you do not repay as agreed, the shop can sell it.3
Costly mistakes
Mistake: Rolling over the title loan every month.
Instead: Each rollover adds another fee; in the FTC's example, two months cost at least $500 on $1,000.1
Mistake: Thinking partial payments protect your car.
Instead: The FTC says it can be repossessed even after partial payments.1
Mistake: Accepting add-ons without asking what they add up to.
Instead: Processing and document fees and add-ons raise the cost of the loan.1
Mistake: Looking only at the 'interest' at the pawn shop.
Instead: Add up every fee: storage and processing belong in the APR too.5
Mistake: Leaving your things in the car and not claiming them.
Instead: Contact the lender right away to get them, and write down what was there.6
Mistake: Not asking about your rights when the car is sold.
Instead: Ask your state attorney general or legal services: you may have a right to notice, to buy it back or to the surplus.6
What to do this week
- Before handing over a title or an item, write down how much you need and ask your creditor for more time.1
- Ask a federal credit union in your area about a PAL.7
- If you already have a title loan, gather the agreement and add up every fee.1
- Look up the number for your state attorney general or consumer protection office, in case you need it.6
- Start an emergency fund, even a small one, and organize your debts with the credit plan.
Your household this month
Let's do the math
Left each month
Enter what at least one person takes home to see the result.
What helps
- Pay savings first: set the goal aside the day the money arrives, before flexible spending.
- Add up the bills that come every few months (car insurance, school) and divide by twelve.
- If income changes, plan on a low month and save the extra from good months.
- A HUD-approved housing counselor can go over the budget with you, often for free.
This is a planning tool with your numbers, not a credit evaluation or an approval. The split reference is only a guide.
Ready to see the numbers? Find your county here
See how this applies in your county: its loan limits, prices and rents, from the official data.
Printable checklist
Frequently asked questions
How much does a car title loan cost?
The FTC says they often have monthly fees of up to 25%, an APR of about 300%, plus processing, document or origination fees and add-ons such as a roadside service plan. In its example, borrowing $1,000 for 30 days leaves you owing $1,250, and rolling it over another 30 days raises the cost to at least $500.
Can they take my car if I have made payments?
Yes. The FTC warns that the lender may repossess the vehicle even if you have been making partial payments, and that some install GPS and starter interrupt devices to locate and disable it remotely.
If my car sells for more than I owed, do I get the difference?
It depends on your state. The CFPB explains that, when a car is repossessed, if it sells for more than you owe you may be entitled to the surplus. But the FTC warns that, with a title loan, in some states the lender can keep everything from the sale. Ask your local legal services office or your state attorney general.
What happens if I do not repay a pawn loan?
The CFPB explains that the pawn shop keeps your item during the loan and, if you do not repay as agreed, can sell it to cover the debt. It also says the loan is often much less than the item's actual value.
How do I know what the pawn shop really charges?
Ask for the annual percentage rate (APR). In a lawsuit, the CFPB explained that every fee on the loan, whether called storage, appraisal or processing, is part of the finance charge and must be included in the APR. Add up all the fees before you sign.
What alternatives do I have if I need money quickly?
The FTC suggests asking your creditors for more time, a PAL loan from a federal credit union, small loans from local banks, nonprofit credit counseling, help from family or friends, and charities and places of worship.
Are there protections if I am in the military?
Yes. The CFPB explains that the Military Lending Act covers vehicle title loans: active-duty members and their dependents cannot be charged more than a 36% MAPR or be required to accept mandatory arbitration. Your JAG office can help.
Sources
Every figure in this guide comes from one of these official sources. The number next to a sentence leads to the source behind it.
Each source on one line: who publishes it, its title, its address and the date we read it.
- 1. FTC · What To Know About Payday and Car Title Loans · consumer.ftc.gov · Accessed October 31, 2026
- 2. CFPB · CFPB Finds One-in-Five Auto Title Loan Borrowers Have Vehicle Seized for Failing to Repay Debt · consumerfinance.gov · Accessed October 31, 2026
- 3. CFPB · Your Money, Your Goals: Finding financial products and services · files.consumerfinance.gov · Accessed October 31, 2026
- 4. CFPB · Consumer use of payday, auto title, and pawn loans (research brief) · files.consumerfinance.gov · Accessed October 31, 2026
- 5. CFPB · CFPB Takes Action Against B&B Pawnbrokers For Deceiving Consumers About Loan Costs · consumerfinance.gov · Accessed October 31, 2026
- 6. CFPB · What happens if my car is repossessed? · consumerfinance.gov · Accessed October 31, 2026
- 7. NCUA (Code of Federal Regulations, text at Cornell LII) · 12 CFR §701.21, Loans to members and lines of credit to members · law.cornell.edu · Accessed October 31, 2026
- 8. CFPB · What is covered under the Military Lending Act? · consumerfinance.gov · Accessed October 31, 2026
See the other 1 sources
- 9. Legal Services Corporation (LSC) · I Need Legal Help · lsc.gov · Accessed October 31, 2026
Keep reading
Related guides
If this guide helped, these follow the same path.
Credit 12 minute read
Payday loans: what they cost and the alternatives
How a payday loan works, what the CFPB says it costs, what a federal credit union payday alternative loan (PAL) is and what to do if you already have one.
- The CFPB says a typical two-week payday loan equals an APR of almost 400%, and a rollover does not reduce what you owe.
- Four out of five payday loans are rolled over or renewed within 14 days, according to a CFPB study.
- Federal credit unions can offer PAL loans of $200 to $2,000, for one to 12 months, with no rollovers and an application fee of $20 at most.
- Taxes and money Emergency fund: how to start one even on a small income What an emergency fund is, how much to save for your situation, how to start with little money, where to keep it safe and what it costs not to have one. 10 minute read
- Taxes and money Credit unions vs. banks: how they differ Credit unions and banks: who can join, NCUA and FDIC insurance, fees and overdrafts, accounts with an ITIN, small-dollar loans and CDFIs. 11 minute read
- Credit Debt collection: your rights with debt collectors What a debt collector must tell you, how to dispute in writing, when and how often they can call, old debts, and what to do if you are sued. 16 minute read
Tools for this topic
Was this guide useful?
Thank you. Your answer stays in your browser; nothing is sent.