Student loans and getting a mortgage
How FHA and Fannie Mae count your student loan: income-driven payments, $0 payments, deferment, past-due federal debt and which papers to ask for.
Verified against official sources on October 31, 2026 5 official sources
Show contents
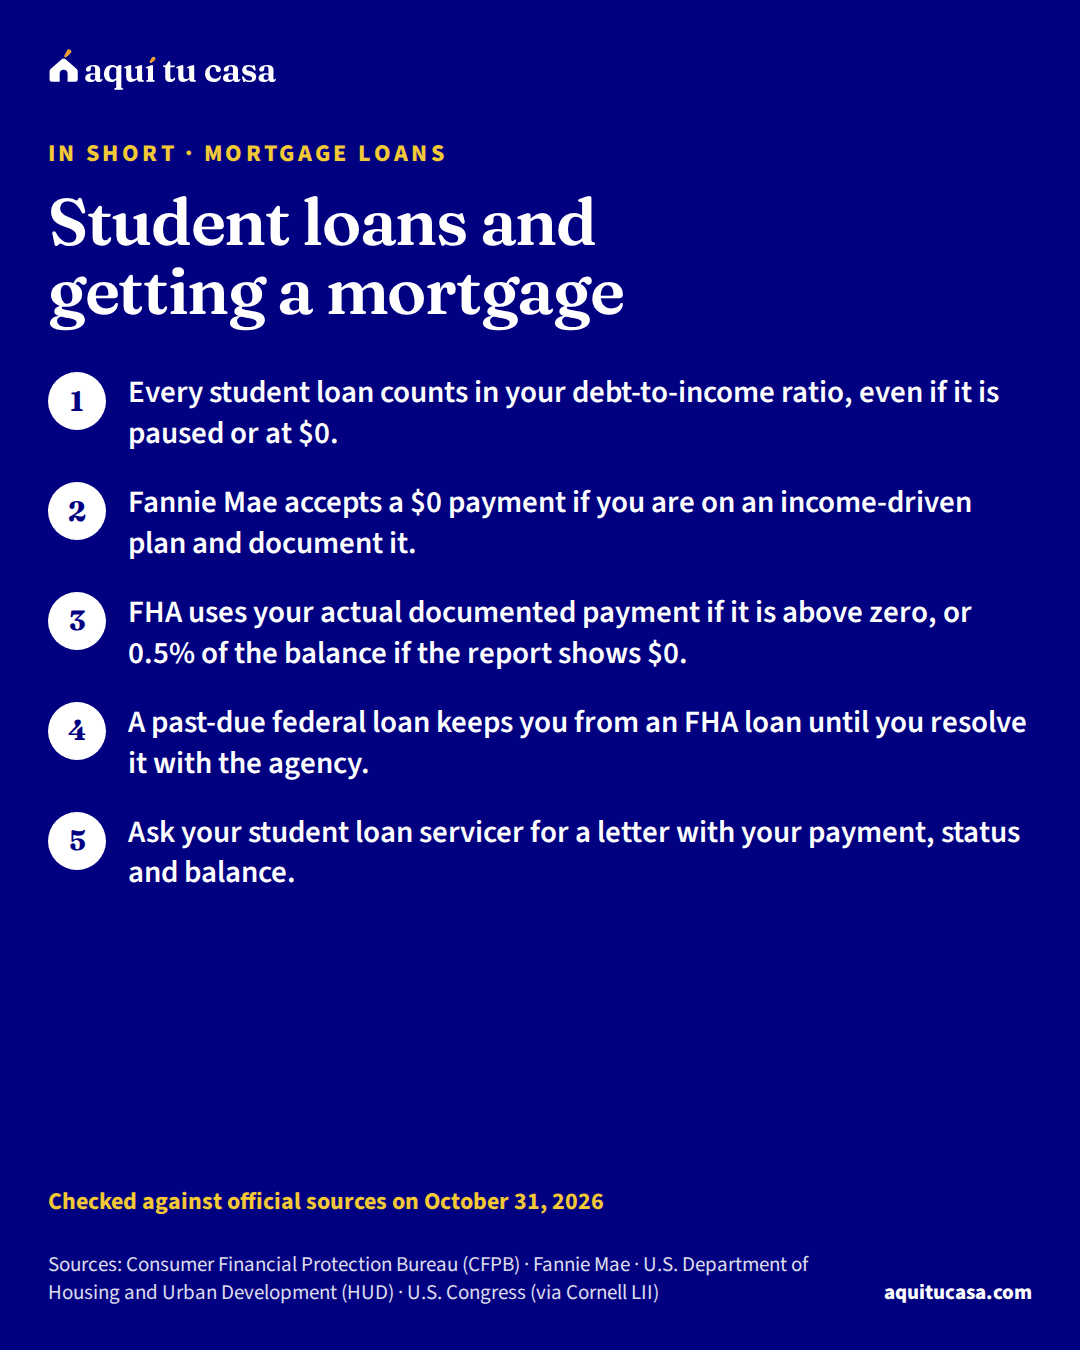
In short
What you need to know
Quick answer
Your student loan counts as debt when you apply for a mortgage, even if it is paused. What changes is the payment that gets used. With Fannie Mae (a conventional loan), if you are on an income-driven plan and document an actual payment of $0, you can be qualified with $0; if the loan is deferred or in forbearance, the lender uses 1% of the balance or the full payment. With FHA, the actual documented payment is used when it is above zero, or 0.5% of the balance when the report shows $0. And if you have a past-due federal loan, FHA cannot approve you until you resolve it.
What matters most
- Every student loan counts in your debt-to-income ratio, even if it is paused or at $0.
- Fannie Mae accepts a $0 payment if you are on an income-driven plan and document it.
- FHA uses your actual documented payment if it is above zero, or 0.5% of the balance if the report shows $0.
- A past-due federal loan keeps you from an FHA loan until you resolve it with the agency.
Is this for you?
This guide is for you if…
- You have student loans and want to buy a home.
- Your student loan payment is income-driven, paused or $0, and you do not know how the lender will see it.
- A family member pays your student loan for you.
Get direct help first if…
- Your federal student loans are in default and being collected: get help catching up first.
- You want to know which student loan repayment plan fits you: that is for your student loan servicer, not this guide.
Many families who want to buy a home have student loans, their own or their children’s. Those loans do not keep you from buying, but they do change how much you can borrow, because the lender adds them to your other debts. The key question is which monthly payment the lender will use: the one on your credit report, your income-driven plan payment, a percentage of the balance or zero. Each program has its own rule. This guide explains FHA’s and Fannie Mae’s with their sources, so you ask for the right papers before you apply.
Why your student loan changes what you can borrow
Lenders measure your ability to pay with the debt-to-income ratiodebt-to-income ratio (DTI)Your debt-to-income ratio (DTI) is all your monthly debt payments divided by your gross monthly income, that is, income before taxes. If you pay a certain amount each month across a car, cards, student loans and the mortgage you are asking for, and you earn three times that, your DTI is one third. Lenders use it to measure whether you can manage the payment; each loan type and lender sets its own limit, and assistance programs usually publish theirs. Paying down debt before applying improves your DTI.See the full definition, or DTI: all your monthly debt payments divided by your grossgross incomeGross income is the total you earn before taxes and other deductions are taken out. On your pay stub it shows up as gross pay, not as what lands in your account. Lenders use it to figure your debt-to-income ratio (DTI): they add up your monthly debt payments and divide them by your gross monthly income. When you apply for a mortgage, your annual pre-tax income can include full-time or part-time work, self-employment, tips, commissions, overtime and bonuses; the lender looks at whether you can reasonably expect that income to continue.See the full definition monthly income. Each product and each lender has its own limits.1 Your student loan payment goes into that sum. If the lender uses a high payment, your DTI rises and you may be able to borrow less. If it uses a low, documented payment, your DTI drops.
That is why knowing how much you owe is not enough. What matters is which monthly payment appears on your credit report and which papers you can show. The guide Debt-to-income ratio and how to lower it walks through the full math.
Before you compare offers, ask each lender which student loan payment it used to calculate your DTI. Two lenders can reach different numbers with the same loan: one may offer you an FHA loan and another a conventional one, and each product and each lender has its own limits.1 If the difference is large, ask why. Sometimes handing in the right statement is enough to lower the payment that gets used, and that changes how much you can borrow.
How Fannie Mae counts it (conventional loan)
Fannie Mae’s Selling Guide, which many conventional loans follow, gives the lender these options:2
- If the credit report shows a payment, the lender may use that payment.
- If the report shows the wrong payment, it may use the payment on your most recent statement.
- If the report shows no payment or $0, it must determine one:
- If you are on an income-driven plan and the lender verifies with documents that your actual payment is $0, it can qualify you with $0.
- If your loan is deferred or in forbearance, it may use 1% of the balance, even if that is less than the fully amortizing payment, or a fully amortizing payment under the documented terms.
So with Fannie Mae, an income-driven plan with a well-documented $0 payment can help you a lot. A pause, on the other hand, is not counted as zero. The guide to the conventional loan explains the rest of the program.
How FHA counts it
For an FHA loan, HUD Handbook 4000.1 requires including all your student loans in your debts, regardless of the payment type or whether you are paying now.3 The payment used is:
- The credit report payment or your actual documented payment, when it is above zero.
- 0.5% of the balance, when the report shows a payment of zero.
If the lender wants to use a payment lower than the one on the report, it needs written documentation from the creditor or student loan servicer with your actual payment, account status, balance and terms. And if the balance was forgiven, canceled, discharged or paid in full, it can leave the payment out with a letter saying so.3 The guide to the FHA loan explains the full program.
The same student loan, two programs
Selling Guide B3-6-05
Fannie Mae (conventional)
- Uses the report payment or the one on your statement
- Income-driven plan with a documented actual payment of $0: can qualify you with $0
- Deferred or in forbearance: 1% of the balance or the full payment
HUD Handbook 4000.1
FHA
- Includes every student loan, whatever its status
- Payment above zero: the report payment or your actual documented payment
- Report at $0 (for example, during a pause): 0.5% of the balance
With a documented $0 payment, Fannie Mae can be more favorable; with a paused loan, FHA's 0.5% is less than Fannie Mae's 1%.
Example with real numbers
How much each rule weighs per $1,000 of balance
An example with this guide's rules, per $1,000 you owe; multiply it by your balance.
- Paused loan, FHA loan (0.5% of the balance)
- $5 a month per $1,000
- Paused loan, Fannie Mae (1% of the balance)
- $10 a month per $1,000, or the full payment
- Income-driven plan with a documented $0, Fannie Mae
- $0
- Income-driven plan with a payment above zero, FHA or Fannie Mae
- Your actual documented payment
- What to bring
- A letter from the servicer with your payment, status and balance
The rules come from Fannie Mae and HUD.23 Try the how-much-house calculator with the payment your lender uses.
Run it with your numbersHow much house can I afford?
The new federal repayment plan and your application
Federal law created an income-based repayment plan that the Department of Education offers since July 1, 2026: the Repayment Assistance Plan (RAP). In that plan, if the calculated payment comes out below $10, the monthly payment is $10. Also, each year it is determined whether you still qualify, and your annual income is verified for that.4
What does this mean for your mortgage? In RAP your payment does not reach $0, so the lender will use your actual documented payment, the one on your statement or in the servicer’s letter.23 Since the payment can change each year with your income, check that the letter you hand in shows the current payment. If you change plans while your loan is in process, tell the lender and give them the new document.

If you have a past-due federal loan
This is the point that can stop an FHA loan most. According to HUD’s Handbook, the lender cannot process an FHA loan if you have delinquent federal non-tax debt, and a federal student loan in default is one of those debts. The lender must check every borrower in a government system called CAIVRS. If a debt shows up, it must confirm it with the agency that is owed.3
If the agency confirms the debt is valid and delinquent, you are not eligible for FHA until you resolve it with that agency. But there is a protection: you cannot be denied solely because of CAIVRS information that has not been verified.3 If you think the information is wrong, ask the lender to confirm it with the agency. If you know you are behind, start resolving it months before you go house hunting.
Get your student loan ready before you apply
1. Check your credit reports
3 months before
See which payment appears on each student loan and whether any shows $0.2
2. Ask for the servicer's letter
2 months before
With your actual monthly payment, account status, balance and terms.3
3. Confirm your repayment plan
Before applying
If you are on an income-driven plan, keep the letter showing your current payment.4
4. Resolve any past-due federal debt
As soon as possible
A past-due federal loan keeps you from FHA until you resolve it with the agency.3
5. Ask how your payment is counted
When you seek preapproval
Ask which payment the lender will use and under which rule.1
Try it with your numbersHow much house can I afford?
If someone else pays your loan
It is common for a parent or spouse to pay someone else’s student loan. With Fannie Mae, if you owe the loan but another person is the one actually paying it, the lender can leave that payment out of your debts. For that it needs that person’s canceled checks or bank statements for the last 12 months, with no late payments. This does not apply if the payer is an interested party to the purchase, such as the seller or the agent.2
The same rule works the other way around. If you co-signed your son’s or daughter’s student loan and they are the one paying it, that loan also shows up as your debt. Fannie Mae applies this policy whether or not the other person is also obligated on the loan, so 12 months of your child’s on-time payments from their own account can leave it out of your debts.2
If you plan to use this rule, ask the person who pays to always do it from their own account, on time and with a clear record. A cash payment with no trail cannot document it.
If this is your situation
Your loan is paused
It does not count as zero: if the report shows $0, FHA uses 0.5% of the balance; Fannie Mae, 1% or the full payment.32
Your income-driven plan gives you $0
With Fannie Mae you can be qualified with $0 if it is documented; with FHA, a $0 report leads to 0.5%.23
Your parents pay your loan
With Fannie Mae, 12 months of their payments with no late ones can leave it out of your debts.2
Your federal loan is past due
You are not eligible for FHA until you resolve it with the agency; start before you go house hunting.3
Your loan was forgiven
With FHA, a forgiveness or discharge letter leaves the payment out of your debts.3
Costly mistakes
Mistake: Thinking a paused loan does not count.
Instead: It does: with a $0 report, 0.5% of the balance with FHA; 1% or the full payment with Fannie Mae.32
Mistake: Showing up without the servicer's letter.
Instead: FHA needs written documentation if the payment used is lower than the one on the report.3
Mistake: House hunting with a past-due federal loan.
Instead: Resolve it first with the agency; otherwise FHA cannot approve you.3
Mistake: Handing in a letter with an old payment.
Instead: Your payment can change each year with your income; give the current document.4
Mistake: Letting your relative pay in cash.
Instead: Leaving it out of your debts takes 12 months of checks or bank statements.2
Free help
A HUD-approved housing counselorHUD-approved housing counselorA HUD-approved housing counselor works at an agency HUD has approved to provide housing counseling: independent, expert advice customized to your situation about buying a home, renting, a missed mortgage payment, a foreclosure or credit problems. The agencies usually charge little or nothing; many serve in Spanish and offer the homebuyer education course several assistance programs require. They are not lenders or real estate agents and sell you nothing. Your county page lists the official agencies with phone numbers.See the full definition can review your budget and debts with you before you apply, often at little or no cost. You search by ZIP code on the CFPB’s website.5 The guide HUD-approved housing counselors explains what to expect. When you are ready, Preapproval vs. prequalification helps you take the next step.
What to do this week
- Check your credit reports and write down the payment shown on each student loan.2
- Ask your servicer for a letter with your actual payment, status, balance and terms.3
- If you are on an income-driven plan, keep the letter with your current payment.4
- If any federal loan is past due, start resolving it with the agency.3
- Estimate how much you can borrow with the how-much-house calculator and organize your spending in the family budget.1
- Read How to read your credit report to check that each loan is reported correctly.
Your numbers
The minimum for this loan is 3.5%. More down lowers the monthly payment.
Adjust advanced details
First number: share of income for housing. Second: housing plus debts. Lender references, not fixed rules.
Let's do the math
Estimated top price
National figure$227,000
Limited by the housing payment: at that price it would be about $1,883 a month, 28% of your income.
- By the housing payment (28% of income)Limits you$227,000
- By your total debts (36% of income)$292,000
- By your cash (down payment + closing)$330,500
- Typical home in the United States
- $332,700
- Your cap is 68% of the typical home.
What changes if…?
- …you save $10,000 more$227,000
- …you cut $200 a month in debts$227,000
Your maximum price with four loans
Same income, debts and savings; only the down payment and the loan type change. ITIN uses an example down payment and rate.
| FHA 3.5% | Conventional 5% | Conventional 20% | ITIN 15% (example) | |
|---|---|---|---|---|
| Maximum price | $227,000 | $232,000 | $93,000 | $119,000 |
| Payment per month | $1,883 | $1,882 | $616 | $898 |
Educational estimate, not a pre-approval. Uses example insurance (0.5% of value per year) and example closing costs (3% of price); the tax is the place’s typical rate.
Ready to see the numbers? Find your county here
See how this applies in your county: its loan limits, prices and rents, from the official data.
Printable checklist
Frequently asked questions
Does my student loan count even if it is paused?
Yes. FHA includes every student loan, whether or not you are paying. Fannie Mae, for a deferred or paused loan, uses 1% of the balance or the full payment under the terms.
My income-driven payment is $0. Will they count $0?
With Fannie Mae, it can be, if the lender verifies with documents that your actual payment is $0. With FHA, when the report shows $0, 0.5% of the balance is used.
What about the new 2026 repayment plan?
The law created the Repayment Assistance Plan starting July 1, 2026. In that plan the minimum payment is $10, so it does not reach $0. The lender uses your actual documented payment.
Which document do I give the lender?
Your most recent statement or a letter from your student loan servicer with your monthly payment, account status, balance and terms. FHA requires that document in writing if the payment used is lower than the one on the report.
My parents pay my student loan. Is it counted as my debt?
With Fannie Mae, the lender can leave it out if someone else actually pays it and provides 12 months of checks or bank statements with no late payments. It does not apply if the payer is the seller or the agent.
I have a past-due federal loan. Can I apply for an FHA loan?
Not until you resolve it. According to HUD's Handbook, if the agency confirms the federal debt is valid and delinquent, you are not eligible for FHA until you resolve it with that agency.
My loan was forgiven. Do they still count it?
With FHA, the lender can leave the payment out if you have written documentation that the balance was forgiven, canceled, discharged or paid in full. Keep that letter.
Sources
Every figure in this guide comes from one of these official sources. The number next to a sentence leads to the source behind it.
Each source on one line: who publishes it, its title, its address and the date we read it.
- 1. Consumer Financial Protection Bureau (CFPB) · What is a debt-to-income ratio? · consumerfinance.gov · Accessed October 31, 2026
- 2. Fannie Mae · Selling Guide B3-6-05, Monthly Debt Obligations · selling-guide.fanniemae.com · Accessed October 31, 2026
- 3. U.S. Department of Housing and Urban Development (HUD) · Handbook 4000.1, FHA Single Family Housing Policy Handbook · hud.gov · Accessed October 31, 2026
- 4. U.S. Congress (via Cornell LII) · 20 U.S.C. §1087e, Terms and conditions of loans; reimbursement · law.cornell.edu · Accessed October 31, 2026
- 5. Consumer Financial Protection Bureau (CFPB) · Find a housing counselor · consumerfinance.gov · Accessed October 31, 2026
Keep reading
Related guides
If this guide helped, these follow the same path.

Buying a home 14 minute read
Debt-to-income ratio (DTI): what it is and how to lower it
What the debt-to-income ratio (DTI) is, how to calculate it, which payments count, the caps FHA, Fannie Mae, VA and USDA publish and how to lower it.
- DTI = monthly debt payments ÷ gross monthly income; the new home's payment is part of the math.
- There are two ratios: housing (front-end) and total (back-end); each program uses one or both.
- Caps vary by program: Fannie Mae, FHA, VA and USDA publish their own, and the lender can be stricter.
- Mortgage loans FHA loan: down payment, insurance, limits and who qualifies How an FHA loan works: the down payment and credit score HUD requires, MIP mortgage insurance, your county limit, the home and the residency rules. 14 minute read
- Mortgage loans Conventional loan: 3% down, PMI and credit scores How a conventional loan works: HomeReady and Home Possible from 3% down, the credit score Fannie Mae requires, PMI and when the law ends it. 12 minute read
- Buying a home Preapproval vs. prequalification: what each letter means What prequalification and preapproval letters are, what lenders check, why neither one is a loan, and how to compare lenders without hurting your credit. 14 minute read
Tools for this topic
Was this guide useful?
Thank you. Your answer stays in your browser; nothing is sent.